Tag: Credit Union Membership

  • Credit Union vs Bank: What’s the Difference? (2026 Guide)

    Credit Union vs Bank: What’s the Difference? (2026 Guide)

    Credit Union vs Bank: What’s the Difference?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    Credit Union vs Bank: What’s the Difference?

    Credit Union vs Bank What's the Difference 2026If you’re comparing a credit union vs bank, the difference goes deeper than the name on your debit card. Both can provide checking accounts, savings accounts, loans and other everyday financial services. The bigger distinction is how each institution is structured and who owns it. Credit unions are member-owned cooperatives, while banks generally operate as for-profit businesses.

    That ownership difference can shape the way you experience an account, but it does not tell the whole story. Membership eligibility, interest rates, fees, branch networks, ATM access, digital tools and loan terms can vary widely from one institution to another. A national bank may offer broad access across the country, while a credit union may have a more limited footprint but serve a specific community, employer group or association.

    The right comparison starts with your own banking habits. Do you need frequent branch visits? Is a large ATM network important? Are you mainly looking for a checking account, a savings account or a loan? Once you know what matters, comparing the actual account terms becomes much easier. For the broader picture, see our complete Credit Unions Explained guide.

    THE BIG IDEA

    A bank and a credit union can look similar from a customer’s perspective. The meaningful differences usually appear in ownership, membership, rates, fees, access and account protections.

    What You’ll Learn

    • How credit unions and banks are structured and owned.
    • Why credit union membership can have eligibility requirements.
    • How rates, fees, branches and digital banking may differ.
    • How NCUA share insurance compares with FDIC deposit insurance.
    • Which account features deserve attention before you open an account.
    • Common mistakes to avoid when comparing the two.

    Quick Answer: Credit Union vs Bank

    The simplest credit union vs bank difference is ownership. A credit union is a member-owned cooperative, while a bank generally operates as a for-profit financial institution. Yet both can handle everyday needs such as checking, savings, payments and borrowing. What matters is how the specific institution’s terms fit your needs.

    KEY TAKEAWAYS

    • Credit unions are member-owned financial cooperatives.
    • Banks and credit unions can offer many similar financial products.
    • Credit union membership usually depends on eligibility rules.
    • Interest rates, fees and account requirements vary by institution.
    • Branch, ATM and online banking access can differ significantly.
    • Qualifying accounts at federally insured credit unions can receive NCUA share insurance, subject to coverage rules and limits.

    BOTTOM LINE

    There isn’t one universal answer for every household. Compare the actual rates, fees, account features, access and applicable insurance before deciding where to keep your money.

    Credit Union vs Bank at a Glance

    A credit union and a bank can look similar when you use them day to day. Both may offer checking, savings, debit cards, online banking and loans. The bigger differences involve ownership, eligibility, governance and insurance.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeOwnership structure varies by bank
    EligibilityUsually requires meeting the credit union’s field-of-membership rulesUsually based on the bank’s account-opening requirements
    GovernanceMembers elect the board under applicable rulesGoverned according to the bank’s corporate or ownership structure
    Account TermsRates, fees and requirements vary by credit unionRates, fees and requirements vary by bank
    Federal InsuranceNCUA share insurance may apply at federally insured credit unionsFDIC deposit insurance may apply at FDIC-insured banks

    QUICK TAKE

    The institution’s label is only the starting point. Before opening an account, compare the APY, interest rate, fees, minimums, ATM access, digital features and applicable federal insurance for the specific product.

    Credit Union vs Bank: Complete Beginner Guide

    Credit Union vs BankFor a beginner, the easiest way to understand a credit union vs bank comparison is to follow the customer journey. You start by finding an institution that fits your needs, open an account, use its services and then compare how well the account works for you over time.

    1. Check Whether You Can Join

    With a credit union, eligibility comes first. A credit union generally has a defined field of membership. Depending on its charter, eligibility may be connected to where you live, where you work, a family relationship or membership in a qualifying organization. Once you qualify, the institution will explain its membership and account-opening requirements.

    2. Compare the Account Before Opening It

    Whether you choose a bank or credit union, look at the actual account rather than relying on the institution’s name. Check the monthly fee, minimum balance, opening deposit, transaction rules, ATM access and digital banking features. For checking accounts, our guide to how checking accounts work covers the basics beginners should understand.

    3. Use the Account for Everyday Money

    After opening an account, your daily routine may look similar at either type of institution. You might receive a debit card, set up direct deposit, pay bills, transfer money, deposit checks and manage your balance through online or mobile banking. The available features depend on the specific institution and account.

    4. Apply for Loans When Needed

    Banks and credit unions can both provide loans to qualified borrowers. The application process can involve reviewing income, credit history, existing obligations and other information. Rates, fees, approval standards and repayment terms vary by lender, so compare the complete cost rather than focusing only on the advertised rate.

    5. Recheck the Fit Over Time

    Your banking needs can change. A convenient account today may become less useful if fees increase, your location changes or you need different services. Review your account periodically and compare the rates, fees, access, features and applicable federal insurance with other available options.

    BEGINNER TIP

    Don’t start with “Which institution is better?” Start with “Which account meets my needs?” That shift makes the comparison more practical and easier to evaluate.

    How Credit Unions and Banks Work

    A useful way to understand the difference is to look at how each institution is organized and manages money. Both banks and credit unions can hold customer funds, provide payment services and make loans. However, their ownership structures and governing rules are different.

    How a Credit Union Works

    A credit union operates as a member-owned cooperative. Eligible individuals join under the institution’s field-of-membership rules and may need to maintain a required share account. The credit union manages member shares along with its other funding, investments, liquidity and capital. It can use its financial resources to make loans and provide services, while interest income, fees and other revenue help cover operating costs and support financial strength. Members also have a governance role under applicable rules.

    How a Bank Works

    A bank also manages deposits, lending, payments and other financial services. Deposits are part of the bank’s broader funding structure, while loans and investments are managed as part of its overall balance sheet. Interest income, fees and other revenue help the bank pay operating expenses and run its business. Banks can range from small community institutions to large national organizations, so the products and services available can vary widely.

    Where the Difference Becomes Visible

    For customers, the structural difference can show up in practical areas such as eligibility, account terminology, governance, rates, fees and access. Credit unions may also use shared-branch or cooperative ATM networks, while individual banks may operate their own branch and ATM networks or participate in other networks. The actual experience depends on the institution.

    THE PRACTICAL DIFFERENCE

    Both models manage money through funding, lending, payments and financial services. The key distinction is the structure behind those activities: a credit union is organized as a member-owned cooperative, while a bank follows its own ownership and corporate structure.

    Credit Union vs Bank: Benefits & Drawbacks

    Both credit unions and banks can be useful for everyday banking. The important point is that the experience can vary significantly between individual institutions. A feature that matters to one household may be less important to another.

    Potential Credit Union Benefits

    • Member ownership: Eligible members have an ownership interest in the cooperative.
    • Member participation: Eligible members may have voting rights under the institution’s governing rules.
    • Everyday services: Many credit unions offer checking, savings, cards and lending products.
    • Cooperative structure: The institution is organized around its membership rather than outside stockholders.

    Potential Credit Union Drawbacks

    • Eligibility limits: You may need to meet specific membership requirements.
    • Access differences: Branch and ATM availability depends on the institution and its networks.
    • Technology differences: Mobile and online banking features can vary.
    • Product selection: Some institutions may offer a narrower range of products than larger financial institutions.

    AND WHAT ABOUT BANKS?

    Banks can offer broad product selections, branch networks and digital services, but those features differ by institution too. Fees, minimum requirements, rates and account features also vary. That is why the most useful comparison is between the actual accounts and services you would use.

    Credit Union vs Bank: Side-by-Side Comparison

    The basic difference is easy to remember: credit unions are member-owned cooperatives, while banks follow their own ownership and corporate structures. The more useful comparison, however, is what those structures mean for the accounts and services you actually use.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeOwnership structure varies by institution
    EligibilityGenerally requires meeting the credit union’s field-of-membership rulesGenerally requires meeting the bank’s account-opening requirements
    GovernanceEligible members may vote under applicable governing rulesGoverned according to the institution’s ownership and corporate structure
    AccountsChecking, savings and other products may use share terminologyChecking, savings and other deposit products are commonly available
    Rates & FeesVary by institution, account and productVary by institution, account and product
    Branch & ATM AccessDepends on the credit union and available networksDepends on the bank and its branch or ATM networks
    Digital BankingFeatures and tools vary by institutionFeatures and tools vary by institution
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUA share insurance, subject to coverage rulesQualifying deposits at FDIC-insured banks may receive FDIC deposit insurance, subject to coverage rules

    What This Means for Your Decision

    The ownership difference matters, but it should not be the only thing you compare. If you rarely visit branches, digital features may matter more. If you use ATMs frequently, network access can become important. For borrowing, compare the full APR, fees and repayment terms. For savings, look at the APY and account requirements.

    COMPARE THE ACTUAL PRODUCT

    Before opening an account, compare the APY, APR, fees, minimum balance, ATM access, branch availability, digital features and applicable federal insurance. Those details tell you more about the account than the words “bank” or “credit union” alone.

    Credit Union vs Bank: Costs, Risks & Expert Tips

    The words “credit union” or “bank” don’t tell you what an account will cost. Both types of institutions can have fees, minimum requirements and different rates. Before opening an account, review the current fee schedule, account disclosures and terms for the specific product.

    Costs to Check

    • Monthly maintenance or service fees.
    • Minimum balance and opening deposit requirements.
    • Out-of-network ATM fees and other transaction charges.
    • Overdraft, returned-payment or other account fees.
    • Loan origination, late-payment and other borrowing costs.

    Risks and Practical Limitations

    Access can vary significantly. A credit union may have fewer physical branches than a large bank, although shared-branch arrangements or ATM networks may provide additional access. Banks also differ in branch coverage, ATM availability and digital features. You should also verify the institution’s federal insurance status and understand which accounts qualify for coverage.

    Expert Tips Before You Open an Account

    • Compare the APY or loan APR with the related fees.
    • Check minimum balances and recurring requirements.
    • Review ATM, branch and digital access based on your routine.
    • Read overdraft and transaction rules before relying on the account.
    • Confirm the applicable federal insurance program and coverage terms.

    EXPERT TIP

    Put the numbers side by side before deciding. A useful comparison includes the rate, recurring fees, one-time charges, access and account requirements for the exact products you are considering.

    Common Credit Union vs Bank Mistakes + Illustrative Example

    Choosing between a credit union and a bank can become confusing when the institution’s reputation gets more attention than the account itself. A few practical checks can make the comparison much clearer.

    Mistakes to Avoid

    • Assuming one type always costs less: Rates and fees vary by institution and product.
    • Skipping eligibility checks: A credit union may have membership requirements you must satisfy before opening an account.
    • Looking only at the headline rate: Check fees, minimum balances and other account conditions too.
    • Ignoring everyday access: Consider ATM availability, branches and digital features based on your normal routine.

    An Illustrative Example

    Suppose Daniel needs a new checking account. He qualifies for a nearby credit union, while a national bank is also available to him. Instead of choosing based on the institution’s name, he compares the monthly fee, minimum balance, ATM access, mobile banking features, overdraft terms and direct-deposit options offered by each account.

    That comparison gives Daniel a clearer picture of how each account would fit his routine. The example does not make one institution type the automatic winner. It shows why looking at the actual account terms can be more useful than relying on general assumptions about banks or credit unions.

    THE LESSON

    Start with your real banking habits. List the features you need, compare the specific accounts and then review their costs, access and applicable protections.

    Who Should Choose a Credit Union or Bank?

    There is no single option that fits every household. Your priorities may point toward one institution, while someone with different banking habits may choose another. Start by identifying what you need most from the account.

    A Credit Union May Fit Your Needs If:

    • You meet the institution’s membership eligibility requirements.
    • You value having an ownership role in a cooperative institution.
    • Its rates, fees and account features match your needs.
    • Its branches, ATMs, shared networks or digital services are convenient for you.

    A Bank May Fit Your Needs If:

    • You need access to a particular bank’s branch or ATM network.
    • You prefer the digital tools or account features offered by a specific bank.
    • You need a product or service available through that institution.
    • Its rates, fees and account requirements work for your situation.

    A SIMPLE WAY TO COMPARE

    Write down your top three priorities—such as low fees, convenient ATM access, digital banking or competitive loan terms. Then compare actual accounts against those priorities instead of choosing based only on the institution’s name.

    Frequently Asked Questions About Credit Unions vs Banks

    1. What is the main difference between a credit union and a bank?

    The main structural difference is ownership. A credit union is a member-owned cooperative, while a bank operates according to its own ownership and corporate structure. Both can offer many similar financial services.

    2. Are credit unions and banks insured in the same way?

    No. Qualifying shares at federally insured credit unions may receive NCUA share insurance, while qualifying deposits at FDIC-insured banks may receive FDIC deposit insurance. Coverage depends on the institution, account ownership category, account type and applicable limits.

    3. Do credit unions usually have lower fees than banks?

    Fees vary by institution and account. Some credit unions may offer competitive fees, but you should compare the actual fee schedule rather than assume one type of institution will always cost less.

    4. Can anyone join a credit union?

    Not necessarily. Credit unions generally have a defined field of membership. Eligibility may depend on factors such as location, employment, family relationships or membership in a qualifying organization.

    5. Are credit union accounts FDIC insured?

    No. Federally insured credit unions use NCUA share insurance through the National Credit Union Share Insurance Fund. FDIC insurance applies to qualifying deposits at FDIC-insured banks. These are separate federal insurance programs with their own coverage rules.

    6. Can a credit union offer checking and savings accounts?

    Yes. Many credit unions offer both. They may use terms such as share savings and share draft accounts for products that function similarly to savings and checking accounts.

    7. Which usually has more branches, a credit union or bank?

    There is no universal answer. A particular bank may have a large branch network, while a credit union may provide access through its own locations, shared branches or ATM networks. Compare the access available where you live and travel.

    8. What should I compare before choosing between a credit union and bank?

    Compare eligibility, APY or APR, fees, minimum balances, ATM and branch access, digital banking features, account terms and applicable federal insurance. Then match those details with the way you plan to use the account.


    Final Verdict: Credit Union vs Bank

    The credit union vs bank comparison is ultimately about how each institution fits your financial needs. A credit union is a member-owned cooperative for eligible members, while a bank operates under its own ownership and corporate structure. Both can provide checking, savings, payments, lending and digital banking services.

    The practical differences can appear in membership eligibility, rates, fees, branch and ATM access, digital tools and available products. Insurance also depends on the institution’s federal insurance status, the account involved and the applicable coverage rules.

    Before opening an account, compare the specific products you would actually use. Look at the APY or APR, fees, minimum requirements, access, digital features and applicable federal insurance. Those details give you a clearer basis for comparing institutions than the label alone.

    BOTTOM LINE

    Banks and credit unions can both serve everyday banking needs. Compare the actual institution, account terms and available services against the way you plan to manage your money.

    For a broader explanation of membership, accounts, fees and NCUA insurance, continue with our complete Credit Unions Explained guide.

    Related Resources & Authority Sources

    If you’re comparing banks, credit unions and other account options, these FinanceInvestment guides can help you explore the details that matter beyond the basic ownership difference. Start with the complete Credit Unions Explained guide for a broader look at membership, accounts, fees and NCUA insurance.

    FINANCEINVESTMENT GUIDES

    Official Authority Sources

    RESEARCH TIP

    Banking terms and account features can change. Before opening an account, check the institution’s current disclosures and official regulator information for rates, fees, eligibility and applicable insurance coverage.

    Have a Money Question? Keep Exploring.

    Your banking choice is only one part of a larger money plan. Keep exploring the account features, costs, access and protections that can shape your everyday financial decisions.

    📩 Get in Touch With FinanceInvestment

    Have a personal-finance question or a topic you’d like FinanceInvestment to explain?

    Email FinanceInvestment

  • How Do Credit Unions Work? Complete Beginner Guide 2026

    How Do Credit Unions Work? Complete Beginner Guide 2026

    How Do Credit Unions Work? Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    How Do Credit Unions Work?

    How Do Credit Unions WorkIf you’ve ever wondered how do credit unions work, the simplest answer is this: members save, borrow and use financial services through a cooperative institution they collectively own. Credit unions can accept member savings, make loans and provide services much like banks, but their ownership structure is different. The NCUA describes credit unions as member-owned, member-controlled cooperatives.

    The money flow is at the heart of the model. Members put money into savings and other share accounts. The credit union uses its available funds to support lending and day-to-day operations. When members borrow, their loan payments bring money back into the institution. Revenue from loans, fees and other activities helps cover operating costs and maintain the credit union’s financial strength.

    Membership is another important piece. A credit union usually has a defined field of membership, which can be based on factors such as employment, location, family or association membership. So before opening an account, you need to determine whether you qualify.

    THE SIMPLE IDEA

    A credit union creates a cooperative financial cycle: members save → the credit union lends → borrowers repay → the institution serves its members and covers its costs.

    For the bigger picture, see our complete Credit Unions Explained guide, which covers accounts, membership, fees, NCUA insurance and other important details.

    What You’ll Learn

    • How credit union membership and ownership work.
    • How member savings and loans connect inside the cooperative model.
    • How checking, savings and other share accounts fit into the system.
    • How revenue, fees and operating costs affect the credit union.
    • How credit unions differ from traditional banks.
    • What to consider before joining or opening an account.

    Quick Answer: How Do Credit Unions Work?

    How do credit unions work? They operate as member-owned financial cooperatives. People who qualify for membership can place money into share accounts, use checking and savings services, and apply for loans. The credit union earns revenue, pays its operating expenses, manages financial reserves and provides services for its members.

    The biggest difference from a traditional bank is the ownership structure. Eligible members become part of the cooperative and may have voting rights under the credit union’s rules. Credit unions also use different terminology: a savings account may be called a share account, while a checking account may be called a share draft account.

    KEY TAKEAWAYS

    • You generally need to meet the credit union’s membership eligibility rules.
    • Members can use share accounts, checking services, loans and other financial products.
    • Membership gives eligible individuals an ownership interest in the cooperative.
    • Credit unions generate revenue to cover expenses, maintain financial strength and serve members.
    • Accounts at federally insured credit unions can receive NCUA share insurance, subject to applicable coverage limits and rules.

    Credit Unions at a Glance

    FeatureWhat It Means
    OwnershipEligible members have an ownership interest in the cooperative.
    MembershipYou generally must qualify under the credit union’s field-of-membership rules.
    AccountsProducts may include share savings, share draft checking and share certificates.
    LoansCredit unions can provide financing for needs such as vehicles, personal expenses and homes.
    Share InsuranceAccounts at federally insured credit unions may receive NCUA share insurance, subject to coverage limits and applicable rules.

    QUICK TAKE

    A credit union brings membership, saving, borrowing and financial services together under a cooperative structure. The exact products, fees, eligibility rules and insurance arrangements vary, so compare the specific credit union before opening an account.

    How Credit Unions Work: Complete Beginner Guide

    How Do Credit Unions WorkTo understand how credit unions work, it helps to follow the process from eligibility to everyday financial services. The experience can look familiar if you’ve used a bank before: you may save money, make payments, use a debit card, manage your account online and apply for a loan. The main difference is the cooperative ownership structure.

    1. You Qualify for Membership

    A credit union generally serves a defined field of membership. Depending on its charter, eligibility may be connected to your community, employer, family relationship, association or another qualifying group. Once you qualify, the credit union explains the steps and minimum share requirements for becoming a member.

    2. You Open Accounts and Use Services

    Credit unions can offer many of the same everyday services available at banks. A share savings account can hold savings, while a share draft account can provide checking features. Depending on the institution, members may also have access to share certificates, debit cards, digital banking, credit cards and other products.

    3. The Credit Union Manages Its Resources

    The credit union manages member shares along with other funding sources, investments, liquidity and financial reserves. It can use available resources to make loans to qualified borrowers and provide other services. Interest from loans, fees and other revenue help the institution pay operating expenses and maintain financial strength.

    4. Members Have an Ownership Role

    The members are the owners of the cooperative. Eligible members generally have voting rights under the credit union’s governing rules and elect a board of directors to oversee the institution. This member-owner structure is one of the clearest differences between a credit union and an investor-owned bank.

    BEGINNER TIP

    Before joining, check the credit union’s eligibility rules, minimum share requirement, account fees, digital access, ATM options and applicable insurance coverage. If you’re comparing digital institutions with cooperative options, our guide to digital banks vs. credit unions can help you compare the basic models.

    How Credit Union Money Flow Works

    To understand how money moves through a credit union, think beyond a simple “savings account funds a loan” model. A credit union manages member shares together with its other funding sources, investments, liquidity and capital. Its goal is to provide financial services while meeting withdrawals, loan demand, operating expenses and other obligations.

    Step 1: Members Keep Money in Share Accounts

    Members may keep money in share savings, share draft and other eligible accounts. These balances become part of the credit union’s overall funding base. The institution manages that money rather than treating each member’s balance as a separate pool reserved for a particular purpose.

    Step 2: The Credit Union Provides Financing

    Credit unions evaluate loan applications and may provide financing to qualified borrowers. Depending on the institution, loans can include auto loans, personal loans, mortgages and credit cards. Borrowers then make principal and interest payments according to their agreements.

    Step 3: Revenue Covers Costs and Supports Financial Strength

    Interest from loans and revenue from other activities help the credit union pay employee, technology, facility, insurance and regulatory expenses. The institution also manages capital, liquidity and reserves to remain financially sound and ready to meet member needs.

    Step 4: The Cycle Continues

    Members continue saving, borrowing, making payments and using financial services. Because the institution is member-owned, its financial activities are organized around serving its membership rather than outside stockholders. The exact rates, fees and financial products vary by credit union.

    MONEY-FLOW SNAPSHOT

    Members provide funding → the credit union manages its resources → qualified borrowers receive financing → borrowers make payments → revenue supports operations, liquidity and financial strength. This is a simplified view of a much more detailed balance sheet.

    Credit Union Benefits & Drawbacks

    Credit unions can offer a different banking experience because members own the cooperative and eligible members can participate in its governance. At the same time, a credit union is not automatically the right fit for everyone. Products, rates, fees, technology and access can vary considerably between institutions.

    Potential Benefits

    • Eligible members have an ownership role in the cooperative.
    • Members can access checking, savings, loans and other financial services.
    • Some credit unions may offer competitive rates or fees on particular products.
    • Members may have voting rights under the credit union’s governing rules.

    Potential Drawbacks

    • Eligibility rules can limit who is able to join.
    • Branch and ATM access may vary by location and network.
    • Digital banking tools and product selection can differ between institutions.
    • Rates and fees are not automatically better than those offered by banks.

    WHAT TO CHECK

    Before joining, compare the specific credit union’s APYs, loan rates, account fees, minimum balances, ATM access, digital banking features, membership rules and applicable share insurance. The cooperative structure is only one part of the decision.

    Credit Union vs. Bank Comparison

    Credit unions and banks can both provide checking, savings, payment services and loans. The clearest structural difference is ownership: a credit union is a member-owned cooperative, while a bank may be shareholder-owned or privately owned. That distinction can affect governance and membership rules, but it does not by itself determine the rates, fees or services available to customers.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeMay be shareholder-owned or privately owned
    EligibilityGenerally requires meeting the credit union’s membership rulesMust meet the bank’s account-opening and customer requirements
    GovernanceEligible members may vote under applicable rulesGoverned according to the bank’s ownership and corporate structure
    Deposit/Share InsuranceFederally insured credit unions can have NCUA share insurance, subject to applicable limits and rulesFDIC-insured banks provide FDIC deposit insurance, subject to applicable limits and rules

    COMPARE THE ACTUAL ACCOUNT

    When comparing a credit union with a bank, look beyond the label. Check the APY, interest rate, fees, minimum balance, ATM access, digital tools, branch availability and applicable insurance coverage for the specific account.

    Credit Union Costs, Risks & Expert Tips

    A credit union can offer useful financial services, but joining does not automatically mean lower costs or better terms. Depending on the institution and account, you may encounter monthly maintenance fees, overdraft charges, ATM fees, minimum-balance requirements, loan interest and other service charges. Always review the specific account terms before joining.

    Risks and Limitations to Consider

    Access can vary significantly between credit unions. One institution may have convenient branches and shared-branch access, while another may rely more heavily on digital banking. Product selection, ATM availability and mobile features can also differ. You should also verify the institution’s share-insurance status and understand which accounts are covered and what limits apply.

    Expert Tips Before You Join

    • Read the account agreement and current fee schedule.
    • Check minimum opening deposits and balance requirements.
    • Compare loan APRs, fees and total borrowing costs.
    • Review branch, ATM, shared-branch and digital access.
    • Verify the credit union’s applicable share-insurance coverage before depositing significant funds.

    SMART CHECK

    Don’t judge an account by its headline rate alone. Compare the rate, fees, requirements, access and applicable insurance coverage together before making a decision.

    Common Credit Union Mistakes + Illustrative Example

    Knowing how credit unions work is useful, but the account details matter just as much. Many mistakes happen when people focus on the cooperative label and skip the practical terms that affect their everyday banking.

    Mistakes to Avoid

    • Not checking eligibility: Confirm that you qualify before spending time comparing accounts.
    • Ignoring account requirements: Review monthly fees, minimum balances, opening deposits and transaction rules.
    • Assuming all credit unions are alike: Products, rates, technology, branches and ATM access can differ.
    • Comparing only the advertised rate: Consider fees and other account conditions alongside the rate.

    A Simple Example

    Imagine Maria qualifies for a credit union and needs a checking account. She expects to use ATMs several times a month and deposits her paycheck electronically. Before opening the account, she compares the monthly fee, minimum balance, ATM access, mobile deposit features and overdraft terms with another financial institution. The credit union may meet her needs, but if ATM availability or another account feature is less convenient for her routine, she has a practical factor to weigh before joining.

    THE LESSON

    Don’t choose an account based only on the institution’s label. Compare the specific fees, requirements, access, services and applicable insurance coverage against how you actually plan to use the account.

    Who May Benefit From a Credit Union?

    A credit union may fit your needs when its membership rules, account terms, services and access align with how you manage money. The cooperative structure gives eligible members an ownership role, but that feature is only one part of the decision. Your everyday costs, account features and access should also match your priorities.

    A Credit Union May Fit If You:

    • Meet the institution’s membership eligibility requirements.
    • Want checking, savings, lending or other financial services from the same institution.
    • Value having an ownership and voting role under the cooperative’s governing rules.
    • Can conveniently use the credit union’s branches, ATMs, shared-branch network or digital services.
    • Find its fees, rates, minimum requirements and account features suitable for your needs.

    The same comparison process applies whether you’re managing everyday spending, saving for a goal or looking for borrowing options. If you’re comparing online banking with cooperative banking, see our guide to digital banks vs. credit unions.

    A PRACTICAL RULE

    Eligibility determines whether you can join. After that, compare the account terms, costs, access, services and applicable insurance coverage before opening an account.

    Frequently Asked Questions About How Credit Unions Work

    1. How do credit unions work?

    Credit unions operate as member-owned financial cooperatives. Eligible members can use savings, checking, lending and other financial services. The institution manages its resources, earns revenue and uses that revenue to cover operating expenses and maintain financial strength.

    2. Are credit unions banks?

    No. Credit unions and banks can offer many similar financial products, but their organizational structures differ. Credit unions are member-owned cooperatives, while banks may be shareholder-owned or privately owned.

    3. How does a credit union generate revenue?

    Credit unions can generate revenue from loan interest, fees and other financial activities. That revenue helps pay operating expenses, support financial operations and maintain the institution’s financial condition.

    4. Do credit unions have checking and savings accounts?

    Yes. Many credit unions offer both. They may use different terminology, such as share accounts for savings and share draft accounts for checking.

    5. Are credit union accounts insured?

    Accounts at federally insured credit unions may receive NCUA share insurance, subject to applicable coverage limits and rules. Check the institution’s insurance status and account coverage before depositing money.

    6. Can anyone join a credit union?

    Not necessarily. Credit unions generally have a defined field of membership. Eligibility can depend on factors such as location, employment, family relationships or membership in a qualifying organization.

    7. Can credit unions offer loans?

    Yes. Depending on the institution, credit unions may offer auto loans, personal loans, mortgages, credit cards and other financing. Approval, rates and terms depend on the specific product and borrower.

    8. What should I check before joining a credit union?

    Check eligibility, fees, minimum balances, APYs, loan rates, ATM and branch access, digital banking features, account terms and applicable share insurance. Compare those details with your actual banking needs.


    Final Verdict: How Do Credit Unions Work?

    So, how do credit unions work? The model is built around eligible members who use and collectively own a cooperative financial institution. The credit union manages member shares and other resources, provides financial services, makes loans to qualified borrowers and uses revenue to cover operating expenses and maintain financial strength.

    For someone considering membership, the ownership structure is only the starting point. The practical details can differ by institution, including membership eligibility, account fees, rates, minimum balances, ATM access, digital banking features, loan terms and applicable share insurance.

    BOTTOM LINE

    A credit union combines cooperative ownership with everyday financial services. Before joining, review the specific institution’s terms and compare them with the way you actually plan to save, spend or borrow.

    Related Resources & Authority Sources

    If you want to continue researching credit unions, start with our complete Credit Unions Explained guide. You can also compare different banking models with our guide to digital banks vs. credit unions.

    Official Authority Sources

    RESEARCH TIP

    Before opening an account, use the institution’s current disclosures and official regulator information to verify membership eligibility, fees, rates, account terms and applicable insurance coverage.

    Have a Money Question? Keep Exploring.

    Credit unions are just one part of the banking landscape. As you compare your options, keep looking at the details that affect your everyday money decisions, including fees, account features, access, rates and applicable protections.

    📩 Get in Touch With FinanceInvestment

    Have a personal-finance question or a topic you’d like FinanceInvestment to explain?

    Email FinanceInvestment

  • What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    What Is a Credit Union?

    What Is a Credit UnionIf you’ve ever wondered what is a credit union and how it differs from a bank, the basic idea is straightforward. A credit union is a member-owned, not-for-profit financial cooperative that provides services such as savings, checking, certificates and loans to people who qualify for membership. NCUA explains the credit union structure here.

    The difference becomes clearer when you look beyond the account itself. When you join a credit union, you become a member of the cooperative. That relationship can give you access to everyday banking, savings products and borrowing options offered by the institution.

    There is one important checkpoint before choosing an account: eligibility. Credit unions generally operate within a defined field of membership. Depending on the institution, qualification may be connected to your employer, association, geographic community or another permitted relationship. NCUA’s field-of-membership guide explains how these eligibility rules work.

    THE BIG IDEA

    A credit union can look much like a bank when you use it day to day. The meaningful differences are usually found in ownership, membership, account terms, fees, access and insurance. Understanding those details makes the comparison much easier.

    If you want the wider picture after this beginner guide, continue to our complete Credit Unions Explained guide, which brings together accounts, fees, NCUA insurance, membership and other important questions.

    What You’ll Learn

    • What a credit union is and what makes its ownership structure different.
    • Why membership eligibility matters before you open an account.
    • How common credit union accounts work.
    • How credit unions compare with banks.
    • What to check when reviewing fees, access and insurance.
    • The potential benefits and drawbacks of joining a credit union.

    Quick Answer: What Is a Credit Union?

    THE SHORT ANSWER

    A credit union is a member-owned, not-for-profit financial cooperative. People who meet its membership requirements can join and use services such as checking, savings, certificates and loans. The cooperative structure is one of the main differences between a credit union and a traditional bank.

    Key Takeaways

    • Eligibility matters: You need to qualify under the credit union’s membership rules.
    • Members own the cooperative: The institution is organized around its members rather than outside stockholders.
    • Everyday services are available: Many credit unions offer checking, savings, certificates and loans.
    • Account terms vary: Fees, rates, minimum balances and access can differ from one credit union to another.
    • Federal insurance may apply: Qualifying shares at federally insured credit unions can receive NCUSIF coverage, subject to applicable limits and ownership rules.
    • The institution still matters: Compare the actual account and services instead of relying only on the credit union label.

    BOTTOM LINE

    Think of a credit union as a financial cooperative with membership rules. Before joining, compare eligibility, costs, account features, access and applicable insurance.

    Credit Union at a Glance

    Before we get into the details, here is the quick picture. A credit union can provide many familiar financial services, but membership rules, account terms and insurance status are worth checking before you open an account.

    Quick Facts

    FactorWhat to Know
    OwnershipA credit union is a member-owned cooperative.
    MembershipYou generally need to meet the institution’s eligibility requirements.
    Common ServicesChecking, savings, certificates, payment services and loans may be available.
    AccessBranches, ATMs, shared branching and digital banking depend on the institution.
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable rules.

    Key Numbers

    For federally insured credit unions, the standard maximum share-insurance amount is generally $250,000 per share owner, per federally insured credit union, for each ownership category. The actual coverage calculation can depend on ownership structure and other applicable rules.

    There is no single nationwide fee, minimum balance or savings rate for all credit unions. Those figures belong to individual institutions and accounts, so current terms should always be checked before opening an account.

    Who May Find a Credit Union Relevant?

    Credit unions can be relevant to people who qualify for membership and want access to everyday banking, savings or borrowing through a cooperative institution. Families, retirees, students and other consumers may all encounter credit unions, but the useful comparison depends on the products and services they actually need.

    QUICK TAKE

    The first checkpoint is eligibility. Once you qualify, compare the actual account’s fees, rates, minimum balance, access, services and applicable insurance rather than judging the institution by its name alone.

    What Is a Credit Union? A Beginner Guide

    What Is a Credit UnionA credit union is a member-owned, not-for-profit financial cooperative that provides financial services to people who qualify for membership. Like a bank, it may offer checking, savings, certificates, loans and other financial products. The important difference is the ownership structure behind those services. Members join the cooperative and have a membership relationship with the institution. NCUA explains the credit union structure and how it differs from other financial institutions.

    What Does “Member-Owned” Mean?

    When you qualify and join a credit union, you become a member of the cooperative. That is different from simply being a customer of a financial institution. In a federal credit union, members generally have voting rights in the governance of the cooperative, including the ability to participate in the election of the board of directors, subject to the credit union’s governing rules.

    The phrase not-for-profit can also be misunderstood. It does not mean a credit union operates without revenue or earnings. It still has employees, technology, branches, compliance costs and other expenses. Revenue helps cover those costs and supports the institution’s financial strength. NCUA’s guidance on credit-union earnings explains why earnings remain important to a cooperative financial institution.

    Why Do Credit Unions Have Membership Rules?

    A credit union generally serves a defined field of membership. In simple terms, that means there are rules describing who is eligible to join. Depending on the institution, eligibility may be connected to an employer, association, geographic community, family relationship or another qualifying connection. NCUA’s field-of-membership information provides more detail.

    This is why membership should be checked before comparing an account’s rate or fee. If you qualify, the same membership may give you access to several products offered by that credit union.

    Credit Union Terms You May See

    Credit Union TermOften Compared WithTypical Purpose
    Share AccountSavings accountHolding savings and, depending on the credit union, establishing the membership relationship.
    Share Draft AccountChecking accountEveryday spending, payments and other transactions.
    Share CertificateCertificate of deposit (CD)Holding money for a stated term under the certificate’s conditions.

    BEGINNER TIP

    The word “share” can make credit union accounts sound unfamiliar. In practice, many of these products serve purposes similar to accounts you may already know. Focus on the account’s actual fees, rates, access rules and other terms before opening it.

    How Do Credit Unions Work?

    A simple way to understand a credit union is to look at how members save, borrow and use financial services. Members place money into share accounts and other available products. The credit union manages those funds and other resources while making loans to eligible members and providing additional services. Interest from loans and other revenue help pay operating costs and support the institution’s financial strength.

    This creates a cooperative financial cycle. Member savings can help provide part of the funding used for lending, although individual deposits are not directly matched to individual loans. The credit union manages the overall pool of funds, assets and liabilities. NCUA’s explanation of credit union operations describes how federally chartered credit unions allow members to save, borrow and participate in the cooperative.

    Who Runs a Credit Union?

    For a federal credit union, members elect a board of directors from the membership. The board oversees the institution, while management and employees handle day-to-day operations. This gives members a formal role in the governance of the cooperative. NCUA’s operations guidance explains the role of the elected board and member ownership.

    What Happens to Credit Union Earnings?

    Not-for-profit does not mean a credit union can operate without earnings. NCUA explains that credit unions need revenue to cover the cost of serving members and maintain an appropriate level of net worth. Depending on the institution’s financial position, earnings may be retained to strengthen the credit union or may support member value through products, rates, fees or dividends. NCUA’s earnings guidance explains this balance.

    StepWhat Happens
    1. JoinAn eligible person becomes a member under the credit union’s membership rules.
    2. SaveMembers can place funds into available share accounts and other products.
    3. BorrowEligible members can apply for loans under the credit union’s lending requirements.
    4. ManageThe institution manages its funds, expenses, risks, capital and member services.

    HOW IT CONNECTS

    The cooperative model connects membership, saving, lending and shared financial services. The exact rates, fees, products and member benefits depend on the individual credit union and its financial condition.

    Credit Union Benefits & Drawbacks

    A credit union can fit well into one person’s banking setup and be less convenient for another. The important part is to compare the specific institution, because account features, fees, rates and access can vary.

    Potential Benefits

    • Member ownership: Joining creates an ownership relationship within the cooperative.
    • Several banking services: Many credit unions offer checking, savings, certificates and loans through the same membership.
    • Competitive terms may be available: Some institutions offer attractive rates or fees on particular products, although there is no guarantee across all credit unions.
    • Multiple access options: Depending on the institution, members may have access to branches, shared branches, ATMs and digital banking.
    • Federal share insurance: Qualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable limits and ownership rules.

    Potential Drawbacks

    • Membership eligibility: You generally need to meet the credit union’s field-of-membership requirements.
    • Branch availability can vary: Some credit unions have fewer physical locations than larger banking networks.
    • Digital features differ: Mobile apps, online banking tools and remote services are not identical across institutions.
    • Product selection varies: A particular credit union may not offer every financial service you want.
    • Rates and fees are not automatically better: The credit-union structure alone does not guarantee a lower fee or higher savings rate.

    EXPERT TIP

    Don’t compare a credit union with a bank using the name alone. Put the actual accounts side by side and check eligibility, APY or dividend terms, fees, minimum balances, ATM access, digital features and applicable insurance.

    Credit Union vs. Bank: What’s the Difference?

    Credit unions and banks can both provide checking, savings, payment services and loans. The differences become clearer when you look at how each institution is organized, who can use it and which insurance system applies to eligible accounts.

    FactorCredit UnionBank
    OwnershipMember-owned cooperativeBanks have their own ownership and corporate structures.
    EligibilityYou generally need to meet membership requirements.Banks generally do not use a credit-union field-of-membership system.
    InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage.Qualifying deposits at FDIC-insured banks may receive FDIC coverage.
    Accounts & ServicesProducts and features vary by credit union.Products and features vary by bank.
    AccessBranches, ATMs, shared networks and digital tools depend on the institution.Branch, ATM and digital access also depend on the institution.

    What Should You Compare?

    For everyday banking, compare the actual account rather than the institution label. Look at monthly fees, minimum balances, savings APY, checking features, ATM access, branch locations and digital banking. If borrowing is important, compare loan APRs, fees, repayment periods and total costs using similar loan amounts and terms.

    Insurance is another important checkpoint. NCUA explains federal share insurance for qualifying shares at federally insured credit unions, while the FDIC explains deposit insurance for qualifying deposits at insured banks.

    COMPARISON TIP

    A useful comparison starts with your actual needs. Put the specific credit union account and bank account side by side and compare their current terms, access and applicable insurance.

    Credit Union Costs, Risks & Expert Tips

    A credit union is not automatically fee-free. Costs depend on the specific account, services you use and the institution’s current terms. Before joining, review the fee schedule and account disclosures instead of focusing only on the advertised rate.

    Costs Worth Checking

    CostWhat to Check
    Monthly FeeWhether a recurring fee applies and whether the credit union offers a waiver.
    Minimum BalanceAny required opening or ongoing balance and the consequences of falling below it.
    ATM ChargesWhich ATMs are available and whether out-of-network fees may apply.
    Other Service FeesReview overdraft, insufficient-funds, wire, transfer and other applicable charges.

    Risks and Important Checks

    The main risk is assuming that all credit unions offer the same rates, fees, technology or access. They do not. A credit union with attractive savings terms may have different ATM coverage or digital features, while another may offer a broader service network. Compare the details that matter to you.

    You should also confirm the institution’s insurance status. At a federally insured credit union, qualifying shares are generally insured through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. Do not treat every financial product offered by a credit union as an insured share account.

    IMPORTANT CHECK

    Federal share insurance generally applies to qualifying share accounts, not investments such as stocks, bonds or mutual funds. Always confirm what you are purchasing and what protection applies before moving money.

    EXPERT TIP

    Before opening an account, save the fee schedule, rate information, account disclosures and insurance details. These documents give you a clear reference point when reviewing the account later.

    Common Credit Union Mistakes to Avoid

    Opening an account without checking the details can lead to avoidable fees or access problems. A few simple checks can make the process easier and help you understand what you are actually getting.

    Mistakes Beginners Often Make

    1. Skipping the eligibility check: Confirm that you qualify for membership and understand any required opening deposit or membership conditions.
    2. Ignoring the fee schedule: Review monthly, ATM, overdraft, transfer and other applicable service fees.
    3. Assuming every credit union works the same way: Branch locations, ATM access, digital tools and account features can vary significantly.
    4. Focusing only on the advertised rate: Check the APY or dividend rate along with minimum balances, fees and other account conditions.
    5. Overlooking insurance status: Confirm whether the institution is federally insured and understand which qualifying shares may receive NCUSIF coverage.

    Illustrative Example: Comparing a Credit Union Account

    Suppose Sarah is looking for a new checking account. She finds a credit union with a low monthly fee and is interested in joining. Instead of opening the account immediately, she first confirms that she qualifies for membership, checks the minimum balance requirement and reviews the fee schedule.

    Next, Sarah checks the credit union’s ATM network and digital banking features. She also verifies its federal insurance status and compares the account with a bank checking account that she could use instead. The comparison shows her the practical differences in fees, access and features.

    This example shows why the account details matter more than the label. A credit union may fit her needs, but she can make that decision only after reviewing the actual terms.

    LESSON FROM THE EXAMPLE

    Before moving your money, check eligibility, fees, rates, access, account conditions and applicable insurance. A few minutes of comparison can reveal details that an advertised offer may not show.

    Who Should Choose a Credit Union?

    A credit union may be worth considering if you qualify for membership and its accounts, services and costs match the way you manage your money. The right fit depends on your individual needs, so compare the actual terms rather than choosing based only on the institution’s name.

    A Credit Union May Fit If You:

    • Qualify for membership: You meet the credit union’s eligibility requirements.
    • Want several services: You can access the checking, savings, borrowing or other products you need through the institution.
    • Value cooperative membership: You prefer an institution organized around a member-owned structure.
    • Find suitable account terms: The fees, rates, minimum balances and features fit your financial needs.
    • Have convenient access: The available branches, ATMs, shared networks and digital tools work for your routine.

    When Should You Compare Other Options?

    Another financial institution may be worth comparing if you cannot qualify for membership or if the credit union’s fees, account features, ATM access, digital tools or product selection do not meet your needs. Comparing similar accounts can help you see the practical differences before opening an account.

    QUICK CHECK

    Before joining, ask three questions: Can I qualify? Does the account meet my needs? Do the costs, access and protections make sense for me?

    Frequently Asked Questions About Credit Unions

    Here are answers to common beginner questions about credit unions, membership, accounts, fees and federal share insurance.

    1. What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative. Eligible members can use services such as checking, savings, certificates and loans. The specific products and terms depend on the institution.

    2. Are Credit Unions Banks?

    No. Credit unions and banks are different types of financial institutions, although they can offer many similar financial products. Credit unions are member-owned cooperatives and generally have membership eligibility requirements.

    3. Can Anyone Join a Credit Union?

    Not necessarily. You generally need to meet the credit union’s field-of-membership requirements. Eligibility can depend on factors such as where you live, where you work, an association or another qualifying relationship.

    4. Are Credit Unions Safe?

    Federally insured credit unions provide federal share insurance for qualifying shares through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. You should verify the credit union’s insurance status before depositing money.

    5. What Accounts Do Credit Unions Offer?

    Many credit unions offer share savings accounts, share draft accounts that work much like checking accounts, share certificates, money market products and loans. The exact product lineup varies by institution.

    6. Do Credit Unions Have Lower Fees Than Banks?

    Not necessarily. Fees vary by institution and account. Compare monthly maintenance fees, minimum balance requirements, ATM charges, overdraft policies and other service costs before opening an account.

    7. What Is NCUSIF Insurance?

    NCUSIF stands for the National Credit Union Share Insurance Fund. It provides federal share insurance for qualifying shares at federally insured credit unions, subject to applicable coverage limits and ownership categories. It does not insure investments such as stocks, bonds or mutual funds.

    8. How Should I Choose Between a Credit Union and a Bank?

    Start with your actual needs. Compare membership eligibility, account fees, rates, minimum balances, ATM and branch access, digital banking, product selection and applicable insurance. Looking at specific accounts side by side can give you a clearer picture than relying on the institution type alone.

    FAQ TAKEAWAY

    The key is to understand membership, account terms, fees, access and applicable insurance before opening a credit union account.


    Final Verdict: What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative that can offer checking, savings, certificates, loans and other financial services. Its membership structure and eligibility rules are what set it apart from a typical bank.

    If you are considering one, start with the basics: Can you qualify, and does the account fit your needs? Then review the actual fees, rates, minimum balances, ATM access, digital tools and available services. These details can vary significantly from one institution to another.

    For federally insured credit unions, also verify the applicable NCUSIF coverage for qualifying shares and understand the relevant ownership limits. This gives you a clearer picture of both the account and the protection attached to it.

    THE BOTTOM LINE

    A credit union is one financial option among several. The useful comparison comes down to eligibility, account terms, costs, access, services and applicable insurance.

    Related Resources & Authority Sources

    If you want to continue learning, our complete Credit Unions Explained guide covers accounts, membership, fees and NCUA insurance in greater detail. You can also explore digital banks vs. credit unions to understand how digital banking models compare with credit-union services.

    Trusted Authority Sources

    • NCUA Share Insurance Coverage — explains federal share insurance, coverage limits, ownership categories and products that are not covered.
    • NCUA Field of Membership — provides information about credit union membership eligibility and field-of-membership rules.
    • FDIC Deposit Insurance — provides information about federal deposit insurance for qualifying deposits at FDIC-insured banks.

    RESEARCH TIP

    Use regulator information to understand insurance and membership rules, then review the credit union’s current account disclosures for its specific rates, fees, minimums and conditions.

    Have a Money Question? Keep Exploring.

    Your banking needs can change over time. Keep learning about accounts, fees, insurance and other money topics so you can evaluate your options with greater confidence.

    📩 Get in Touch With FinanceInvestment

    Have a finance question, topic suggestion or feedback? Send us a message.

    Email FinanceInvestment

    Continue Your Research

  • Credit Unions Explained: Accounts, Fees, NCUA Insurance & Membership (2026)

    Credit Unions Explained: Accounts, Fees, NCUA Insurance & Membership (2026)

    Credit Unions Explained: Complete Beginner Guide to Accounts, Fees, NCUA Insurance & Membership (USA 2026)

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 28, 2026Updated: Sep 28, 2026Reading Time: 25–30 min


    What Is a Credit Union?

    Credit Unions ExplainedA credit union is a financial institution owned and controlled by its members. It can provide many of the same everyday financial services people use at banks, including checking accounts, savings accounts, certificates, debit cards and loans. The key difference is the cooperative structure behind the institution.

    The National Credit Union Administration (NCUA) describes credit unions as not-for-profit, member-owned and member-controlled cooperatives organized to provide financial services to their members. Members typically share a qualifying connection known as a field of membership. Depending on the credit union, that connection may be based on an employer, geographic area, family relationship or qualifying association.

    This membership requirement is one of the first things beginners should understand. You generally cannot choose a credit union solely because you like its rates or branch location. First, you need to determine whether you qualify for membership under that credit union’s charter and field of membership. If you qualify, you can then review its available accounts, fees, services and loan products.

    Credit unions can serve different financial needs under one membership relationship. You might use one for everyday checking, build savings through a share account, open a certificate for a defined period, or apply for a loan. However, products, rates, fees, technology and access can vary from one credit union to another.

    BEGINNER TAKEAWAY

    Think of a credit union through three basic questions: Who owns it? Who can join it? What services does it provide? Once those questions are clear, it becomes easier to compare accounts, fees, insurance, ATM access and loans.

    What You’ll Learn

    • How credit unions work and how their cooperative structure differs from banks.
    • Who can join a credit union and what membership requirements may apply.
    • How checking, savings, share accounts and certificates work.
    • What NCUA insurance is and how applicable coverage limits work.
    • How credit union fees, ATMs, shared branching and digital banking work.
    • How credit union loans compare with bank loans.
    • What to consider before choosing a credit union for everyday banking, saving or borrowing.

    Quick Answer: How Do Credit Unions Work?

    A credit union works as a member-owned financial cooperative. Eligible people join the institution and can then use the financial products and services it offers. These may include savings, checking, certificates, debit cards and loans. The exact products, fees, rates and account requirements vary from one credit union to another.

    For beginners, four terms make the model easier to understand: membership, shares, accounts and loans. Membership gives you access to the credit union. A share account is commonly used to establish the member relationship, while other accounts can be designed for everyday spending or saving. Loans allow eligible members to borrow under the credit union’s stated terms.

    TermSimple MeaningWhy It Matters
    MemberA person who qualifies and joins the credit union.Membership determines access to the institution’s services.
    Share AccountA savings-type account associated with credit-union membership.It may establish the member relationship and can have its own terms.
    Share Draft AccountA checking-type account offered by many credit unions.It can be used for everyday transactions, payments and debit-card purchases.
    LoanMoney borrowed under an agreed repayment arrangement.Rates, fees, terms and approval standards vary by credit union.

    Credit Union vs. Bank: The Basic Difference

    Both credit unions and banks can offer checking, savings, certificates and loans. The structural difference is important: a credit union is organized as a member-owned cooperative and generally has membership eligibility requirements, while a bank operates under a different ownership and regulatory structure. Product availability and pricing still vary by institution.

    QUICK TAKE

    When comparing a credit union, look beyond its name or location. Check membership eligibility, account terms, fees, rates, access and applicable insurance. For federally insured credit unions, the NCUA Share Insurance Coverage guide explains how federal share insurance works.

    How Do Credit Unions Work?

    A credit union brings eligible members together through a cooperative financial institution. Members can save, borrow and use other financial services offered by the credit union. The institution manages its assets, funding, expenses and capital so it can continue providing services while maintaining financial strength.

    Unlike a shareholder-owned bank, a credit union is member-owned and member-controlled. Members of a federally chartered credit union elect a volunteer board of directors from the membership. The board oversees the institution, while management and employees handle day-to-day operations.

    How the Credit Union Model Works

    The basic model connects member savings, lending and financial services. Members may place money into share accounts and other available products. The credit union can use its financial resources to make loans and provide services. Loan interest and other revenue help pay operating costs and support the institution’s capital and long-term financial stability.

    Part of the ModelWhat HappensWhy It Matters
    MembershipEligible people join under the credit union’s field-of-membership rules.Membership provides access to eligible products and services.
    SavingMembers can place funds into share accounts and other available products.Member shares are an important part of the cooperative structure.
    LendingEligible members can apply for loans under the credit union’s terms.Loan interest is an important source of credit-union revenue.
    Financial ManagementRevenue is used for operating costs, member services and appropriate capital needs.Financial strength supports continued service to members.

    What Does “Not-for-Profit” Mean?

    Not-for-profit does not mean a credit union operates without revenue or earnings. It still has employees, technology, branches, compliance requirements and other costs. NCUA explains that credit unions need revenue to cover the cost of providing financial services and to maintain a safe and sound level of net worth. Earnings may be retained to strengthen the institution or, when appropriate, provide value to members through benefits such as dividends, lower fees or competitive loan and savings terms. NCUA’s explanation of credit-union earnings provides more detail.

    KEY IDEA

    The credit-union model connects members, savings, lending and financial services, but each institution has its own charter, policies and financial condition. Rates, fees, products and member benefits can therefore vary.

    Who Can Join a Credit Union?

    Credit Unions ExplainedNot everyone can automatically join every credit union. Eligibility is generally determined by the credit union’s field of membership—the rules that define which people, groups or communities the institution is authorized to serve. Before opening an account, check whether you meet that specific credit union’s eligibility requirements.

    For federally chartered credit unions, NCUA identifies different field-of-membership structures. Depending on the charter, eligibility may be connected to an occupation or employer, membership in a qualifying association, a defined geographic community, or multiple qualifying groups. The exact requirements can differ significantly from one credit union to another. 1

    Common Ways People May Qualify

    Eligibility PathHow It Can WorkWhat to Check
    Employer or OccupationThe field of membership may include employees of a qualifying employer or occupational group.Employer name, location and any stated eligibility conditions.
    AssociationMembership in a qualifying association may provide an eligibility path.Whether the specific association is included in the credit union’s field of membership.
    CommunitySome credit unions serve people who live, work, worship or attend school within a defined community, subject to applicable charter rules.The geographic area specified by the credit union.
    Family or HouseholdSome fields of membership include eligible immediate family or household members.The credit union’s specific membership provisions.

    What Do You Usually Need to Join?

    The exact documents and opening requirements vary. A credit union may ask for identification, personal information and proof that you qualify for membership. A federally chartered credit union generally requires an eligible person to subscribe to at least one share, with the applicable par value established by the credit union.

    That means the membership process is more than simply choosing an account. First confirm eligibility, then review the minimum opening deposit, account requirements, fees and available services.

    MEMBERSHIP CHECK

    Before applying, ask three questions: Do I qualify? What do I need to prove eligibility? What is required to establish membership? If the answers are unclear, contact the credit union before submitting an application. Continue with our How to Join a Credit Union guide for the practical steps.

    Credit Union Accounts Explained

    Once you understand membership, the next step is learning how credit union accounts work. Credit unions can offer different share accounts for saving, everyday spending and longer-term goals. The terminology may look different from what you see at a bank, but the purpose of each account is usually straightforward.

    Common credit union account types include regular share accounts, share draft accounts, money market share accounts and share certificates. Availability, rates, minimum balances, fees and withdrawal rules vary by institution, so the account name alone should not determine your choice.

    Credit Union Checking Accounts

    A credit union checking account is commonly called a share draft account. It is designed for everyday transactions such as debit-card purchases, bill payments, transfers and other withdrawals. Before opening one, compare monthly fees, overdraft policies, ATM access and transaction features. See our Credit Union Checking Accounts Explained guide.

    Credit Union Savings Accounts

    A regular share account is commonly used for saving and can also be part of the membership relationship. Depending on the credit union, the account may pay dividends according to its terms. Minimum share requirements, withdrawal rules and fees can differ. Learn more in Credit Union Savings Accounts Explained.

    Credit Union Share Accounts

    The term share is part of the cooperative language used by credit unions. A member may hold funds in different share accounts, each with its own purpose and terms. NCUA identifies regular shares, share drafts and share certificates among account types that may receive federal share insurance at federally insured credit unions, subject to applicable coverage rules. See Credit Union Share Accounts Explained.

    Credit Union Certificates

    A share certificate is designed for money you can leave in the account for a stated term. In exchange for following the certificate’s terms, the account may provide a stated dividend rate. Check the maturity date, minimum deposit, dividend terms and early-withdrawal rules before committing your money. Our Credit Union Certificates Explained guide covers the details.

    Account TypeTypical PurposeWhat to Check
    Regular ShareBasic saving and membership relationship.Minimum balance, dividend rate, fees and access.
    Share DraftEveryday spending and transactions.ATM access, fees, overdraft terms and transaction features.
    Money Market ShareSavings with terms and access features that vary by institution.Rate, minimum balance, fees and transaction rules.
    Share CertificateMoney intended for a defined period.Term, dividend rate, minimum deposit and early-withdrawal rules.

    ACCOUNT CHECK

    Compare the account’s purpose, minimum balance, fees, dividend terms, access rules and insurance before opening it. At a federally insured credit union, qualifying share savings, share draft and share certificate accounts can receive NCUSIF coverage subject to applicable limits and ownership rules. Review the official NCUA Share Insurance Coverage guide for current details.

    Credit Union Checking & Savings Comparisons

    Credit union checking and savings accounts can provide many of the same everyday functions as bank accounts. The important differences are often found in membership requirements, account terms, fees, rates, access and insurance. Instead of assuming one institution type is automatically better, compare the specific account you would actually use.

    Credit Union Checking vs. Bank Checking

    Both can support direct deposit, debit-card purchases, bill payments, transfers and other everyday transactions. At a credit union, a checking-type account is commonly called a share draft account. At a bank, it is generally called a checking account. The practical comparison should focus on monthly fees, minimum balances, overdraft policies, ATM access, branch availability and digital-banking features.

    See our Credit Union Checking vs Bank Checking guide for a deeper comparison. If you are considering an online-first account, also review Credit Union Checking vs Online Checking.

    Credit Union Savings vs. Bank Savings

    Credit unions commonly use share account terminology for savings. These accounts may pay dividends according to the credit union’s terms. Banks generally describe comparable products as savings accounts that may pay interest. For either option, compare the current rate or APY, minimum balance, fees, withdrawal rules and account access.

    Our Credit Union Savings vs Bank Savings guide explores the differences. If maximizing savings yield is an important goal, compare the account with a Credit Union Savings vs High-Yield Savings option as well.

    FactorCredit UnionBank
    EligibilityMembership eligibility generally applies.Generally does not use a credit-union field-of-membership requirement.
    CheckingOften called a share draft account.Generally called a checking account.
    SavingsOften uses share-account terminology and may pay dividends.Generally uses savings-account terminology and may pay interest.
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage.Qualifying deposits at FDIC-insured banks may receive FDIC coverage.

    Credit Union Savings vs. High-Yield Savings

    A high-yield savings account may be worth comparing when the main goal is earning a competitive rate while keeping savings relatively accessible. But rates can change, and account terms differ. Compare APY, fees, minimum balance requirements, withdrawal rules, transfer options and insurance rather than focusing on the headline rate alone.

    COMPARISON CHECK

    For credit unions, verify whether the institution is federally insured and review its applicable NCUSIF coverage. The official NCUA Share Insurance Coverage guide explains qualifying accounts and coverage limits. For banks, verify FDIC insurance and its applicable coverage rules.

    NCUA Insurance & Account Safety

    One of the most important questions to ask before opening a credit union account is whether the institution is federally insured. The National Credit Union Share Insurance Fund (NCUSIF), administered by the NCUA, provides federal share insurance at federally insured credit unions. The standard coverage amount is generally up to $250,000, subject to account ownership category and other applicable rules.

    This protection is similar in purpose to FDIC deposit insurance at an insured bank, but the systems are separate. NCUA share insurance applies to qualifying shares at federally insured credit unions, while FDIC insurance applies to qualifying deposits at FDIC-insured banks.

    Are Credit Union Accounts NCUA Insured?

    Many credit unions are federally insured, but you should verify the specific institution rather than assume coverage. NCUA says federally insured credit unions must display the official insurance sign and provide information about their insured status. Some state-chartered credit unions use private share insurance instead, so the type of insurance matters.

    For a practical explanation, see our What Is NCUA Insurance? guide and Are Credit Union Accounts NCUA Insured?.

    How Much Does NCUA Insurance Cover?

    The standard maximum is generally $250,000 per share owner, per federally insured credit union, for each ownership category. For example, individual and joint ownership are treated differently for insurance purposes. Certain retirement accounts and eligible trust accounts can have separate coverage rules. The exact calculation depends on how the accounts are owned and whether the applicable requirements are met.

    Because ownership categories can become complicated, do not simply add every account balance together and assume the first $250,000 is the only calculation that matters. NCUA provides a Share Insurance Estimator and coverage guidance for checking specific situations. You can also review NCUA Insurance Limits Explained.

    Account or ProductPotential Federal CoverageImportant Point
    Share SavingsGenerally eligible at a federally insured credit union.Coverage is subject to ownership and applicable limits.
    Share DraftGenerally eligible at a federally insured credit union.Account ownership affects total coverage.
    Share CertificateGenerally eligible at a federally insured credit union.It counts within applicable ownership-category limits.
    Stocks, Bonds & Mutual FundsNot covered by NCUSIF share insurance.Investment products carry their own market risks.

    What NCUA Insurance Does Not Cover

    NCUA share insurance does not protect investments such as stocks, bonds, mutual funds, annuities or municipal securities simply because they are offered through a credit union. NCUA also does not insure digital assets such as cryptocurrencies. These products can involve investment risk and possible loss of principal.

    That distinction matters when a credit union offers both insured share accounts and investment products. Always identify exactly what you are purchasing and which institution or entity is responsible for it.

    SAFETY CHECK

    Before depositing a large amount, verify the credit union’s federal insurance status, understand your ownership category and calculate your coverage. NCUA’s official Share Insurance Coverage resource is the best place to check the current rules.

    Credit Union Fees, Minimum Balances & ATM Access

    Credit unions can offer low-cost accounts, but membership does not automatically mean every service is free. Monthly maintenance fees, minimum-balance requirements, ATM charges, overdraft-related fees and other service costs can vary by credit union and account. Before opening an account, review the institution’s fee disclosures and account terms.

    Common Credit Union Fees

    Depending on the account, possible charges can include monthly maintenance fees, overdraft or insufficient-funds fees, out-of-network ATM fees, wire-transfer fees, stop-payment fees and other service charges. Some accounts waive certain fees when you meet conditions such as maintaining a required balance or receiving direct deposit. The CFPB explains bank and credit-union maintenance fees and how account requirements can affect them.

    For a detailed breakdown, see Credit Union Fees Explained. If your goal is to reduce unnecessary charges, also review How to Avoid Credit Union Fees.

    Credit Union Minimum Balance Requirements

    Some credit union accounts require a minimum opening deposit or ongoing minimum balance. Depending on the account terms, falling below a required balance may trigger a fee or cause you to lose a particular account benefit. Requirements can also differ between a regular share account, checking account and other products.

    Do not focus only on the amount. Check when the balance is measured, whether the requirement applies every day or under another method, and whether there are fee-waiver options. See Credit Union Minimum Balance Requirements for a deeper explanation.

    Credit Union ATM Fees

    ATM access depends on the credit union’s network, account terms and the ATM you use. An out-of-network transaction may involve a fee from the credit union, the ATM operator, or both. The CFPB explains how ATM fees can be charged.

    Before choosing an account, check which ATMs are included in the network, whether the credit union reimburses certain fees and whether shared-branch or surcharge-free ATM access is available. Our Credit Union ATM Fees Explained guide covers these costs in more detail.

    Cost to CheckWhat to AskWhy It Matters
    Monthly FeeIs there a maintenance fee, and can it be waived?Recurring fees can reduce the value of an account over time.
    Minimum BalanceWhat balance or deposit is required?A requirement may affect fees or account benefits.
    ATM FeeWhich ATMs are free, and are fees reimbursed?Out-of-network withdrawals can create additional costs.
    OverdraftWhat happens when a transaction exceeds available funds?Policies and charges vary by account and transaction.

    FEE CHECK

    Before joining, compare the monthly fee, minimum balance, ATM network, overdraft terms and other common charges. A low advertised fee is useful only if you can realistically meet the conditions required to avoid additional costs.

    Shared Branching, ATMs & Digital Banking

    A credit union does not always require you to visit your home branch for routine banking. Depending on the institution and networks it participates in, you may be able to access your account through shared branches, participating ATM networks and online or mobile banking. These access methods serve different purposes, so it is worth checking what your particular credit union actually supports.

    What Is a Credit Union Shared Branch?

    A shared branch is a participating location where members of certain credit unions can receive supported in-person services. Depending on the network and location, services can include deposits, account balance inquiries, check cashing, funds transfers or official checks. NCUA describes shared branching as a cooperative processing arrangement that accepts transactions from members of participating credit unions.

    The services available at one location may not be identical to those available at another. Your credit union may also have specific identification requirements or transaction rules. Before visiting, check the network and location details. Learn more in What Is a Credit Union Shared Branch? and Credit Union Shared Branching Explained.

    Credit Union ATM Networks

    ATM access is separate from shared-branch access. A credit union may operate its own ATMs or participate in a broader ATM network that gives members access to additional machines. Available transactions can include cash withdrawals and other supported ATM services. Network coverage, transaction limits and fees depend on the credit union and network.

    Some credit unions provide access to surcharge-free ATM networks, while others may reimburse certain ATM fees under specific conditions. Check the account terms before relying on a particular ATM network. See Credit Union ATM Networks Explained and Can You Use Any ATM With a Credit Union Account?.

    How Credit Union Mobile Banking Works

    Online and mobile banking can handle many routine tasks without a branch visit. Depending on the credit union, members may be able to check balances, transfer money, pay bills, deposit checks remotely, manage debit cards and receive account alerts. Features vary, so digital access should be part of your comparison when convenient banking matters to you.

    Digital banking also requires basic account-security habits. Use a strong, unique password, enable multifactor authentication when available, keep your banking app updated and avoid entering login information through suspicious links or messages. For a deeper look, see How Credit Union Mobile Banking Works.

    Access MethodTypical UseWhat to Check
    Home BranchIn-person services provided by your credit union.Location, hours and available services.
    Shared BranchSupported in-person transactions through a participating network.Network participation, location and available services.
    ATM NetworkCash withdrawals and other supported ATM transactions.Network coverage, transaction limits and fees.
    Mobile/Online BankingBalances, transfers, bill pay and other digital services.Available features, security and account access.

    ACCESS CHECK

    Before choosing a credit union, check three things: where you can bank in person, where you can access cash, and what you can do online or through the mobile app. A credit union with fewer traditional branches may still provide broader access through participating shared branches, ATM networks and digital services.

    Credit Union Loans & Borrowing

    Credit unions can offer several types of loans to eligible members, including auto loans, personal loans and mortgage loans. The interest rate, APR, fees, approval standards and repayment terms vary by credit union and borrower. Your credit history, income, existing debts, loan amount and other factors can affect the terms you receive.

    You generally need to qualify for membership before borrowing from a credit union, but membership does not guarantee loan approval. The credit union still evaluates your application under its lending policies and applicable regulations.

    Credit Union Auto Loans

    A credit union auto loan can finance an eligible new or used vehicle, subject to the lender’s requirements. When comparing offers, look beyond the monthly payment. Check the interest rate, APR, loan term, required down payment, fees and total repayment amount. A longer term may reduce the monthly payment while increasing the total interest paid.

    The CFPB explains the difference between an interest rate and APR and recommends comparing loan offers using consistent measures. For a credit-union-specific guide, see Credit Union Auto Loans Explained.

    Credit Union Personal Loans

    Personal loans may provide funds for eligible expenses without being tied to a specific vehicle or property. Depending on the product, a personal loan may be secured or unsecured. Compare the interest rate, APR, fees, repayment period, monthly payment and total cost before accepting an offer.

    Also check whether the loan has collateral requirements, prepayment terms or other conditions that could affect your borrowing cost. Learn more in Credit Union Personal Loans Explained.

    Credit Union Mortgage Loans

    Credit unions may also offer mortgage financing for eligible home purchases or refinancing. Mortgage costs can include the interest rate, points, lender fees and other charges. The CFPB explains that mortgage APR is a broader measure of borrowing cost than the interest rate.

    When comparing mortgage offers, review the Loan Estimate and compare equivalent loan terms rather than looking at the rate alone. Our Credit Union Mortgage Loans Explained guide covers the process in more detail.

    Loan TypeCommon PurposeKey Terms to Compare
    Auto LoanPurchase or refinance an eligible vehicle.Rate, APR, term, down payment, fees and total repayment.
    Personal LoanEligible personal expenses or permitted purposes.Rate, APR, fees, term, payment and collateral requirements.
    Mortgage LoanPurchase or refinance qualifying real estate.Rate, APR, points, fees, term and closing costs.

    Credit Union Loans vs. Bank Loans

    The useful comparison is not simply the institution type. Compare actual loan offers from credit unions and banks using similar loan amounts and repayment terms. Review the APR, fees, monthly payment, repayment period, collateral requirements and total borrowing cost. A lower advertised interest rate does not automatically mean a lower total cost when fees and loan terms differ. See Credit Union Loans vs Bank Loans for a detailed comparison.

    BORROWING CHECK

    Before accepting a credit union loan, compare the interest rate, APR, fees, repayment term, monthly payment and total cost. APR is broader than the interest rate because it can reflect certain fees associated with the loan. Always compare similar loan products on an apples-to-apples basis.

    Credit Unions for Families, Seniors, Students & Small Businesses

    Credit unions can serve a wide range of members, but the right account depends on eligibility, financial needs and the services offered by the specific institution. Families may value joint accounts and convenient access. Seniors may prioritize branch availability and simple account management. Students may look for low-cost everyday banking. Small businesses may need business accounts, payment services or financing.

    There is no universal credit union that fits every household, student or business. Start by checking whether you qualify for membership, then compare the products, fees, access and services that matter most to you. NCUA explains that a credit union’s field of membership determines who can join and access its financial products and services.

    Credit Unions for Families

    Families may use credit unions for checking, savings, certificates, auto loans and other financial services. When comparing options, look at joint-account availability, youth or minor accounts, ATM access, shared branching, mobile banking and family-related membership rules. Some credit unions allow qualifying family members to join, but eligibility depends on the credit union’s field of membership and applicable rules.

    For a focused checklist, see Best Credit Unions for Families. Confirm current eligibility and account requirements before applying.

    Credit Unions for Seniors

    For seniors, convenience and account access can matter as much as the advertised rate. Consider branch locations, shared branches, ATM availability, customer support, online banking, mobile features, account fees and security tools. If retirement funds are involved, review the specific account type and applicable insurance rules rather than assuming every financial product receives the same protection.

    Our Best Credit Unions for Seniors guide provides a more detailed comparison checklist.

    Credit Unions for Students

    Students may prioritize low or avoidable fees, convenient ATM access, mobile banking, direct deposit and a simple way to build savings. Some credit unions offer student, youth or minor accounts, but age and membership requirements vary. A student should check who can open the account, whether a parent or guardian is involved, minimum-balance rules and what happens when the student reaches the account’s age limit.

    See Best Credit Unions for Students when comparing student-focused features.

    Credit Unions for Small Businesses

    Some credit unions offer business checking, savings and business lending to eligible members or organizations. Available products vary, so business owners should compare account fees, transaction limits, digital banking, payment services, lending options and eligibility requirements.

    Credit unions can also participate in the SBA 7(a) loan program when they meet SBA requirements. The SBA confirms that credit unions can participate as 7(a) lenders, but participation is not automatic for every credit union. If SBA financing matters to your business, verify that the institution participates and compare its terms with other eligible lenders. See Best Credit Unions for Small Businesses for a focused comparison.

    Member TypeFeatures to ConsiderImportant Check
    FamiliesJoint accounts, youth accounts, savings, loans and access.Membership and family-eligibility rules.
    SeniorsBranches, shared branching, support, digital access and security.Fees, accessibility and account services.
    StudentsLow-cost checking, ATM access, mobile banking and savings.Age, membership and account requirements.
    Small BusinessesBusiness accounts, payment services and financing.Business eligibility, fees, lending terms and SBA participation.

    USE-CASE CHECK

    Choose a credit union based on the features you actually need. Membership eligibility, fees, account access, digital tools, insurance and loan options should all be checked before opening an account.

    Safety, Fraud, Failures & Account Closures

    Credit union safety involves more than checking whether an account is federally insured. Members should also understand common fraud risks, basic account-security practices and what can happen if a credit union experiences serious financial or operational problems. NCUA’s supervisory framework includes risks such as fraud, cybersecurity and payment-system security.

    How to Protect Your Credit Union Account From Fraud

    Phishing, impersonation, social engineering and account-takeover attempts can target financial-account users. Use a strong and unique password, enable multifactor authentication when available, keep your contact information current and monitor account activity. Never share passwords, PINs or one-time security codes because someone contacted you unexpectedly.

    If you receive a suspicious message, contact the credit union through a verified phone number, website or mobile app instead of using a link supplied in the message. See How to Protect Your Credit Union Account From Fraud for a practical security checklist.

    What Happens If a Credit Union Fails?

    Financial problems do not necessarily mean that a credit union immediately shuts down. NCUA may place a federally insured credit union into conservatorship when intervention is necessary. A conservatorship can allow the institution to continue operating while the NCUA or another authorized conservator works to address the credit union’s problems.

    A different outcome is liquidation, in which the credit union is closed and its assets and member claims are handled through a resolution process. Depending on the circumstances, NCUA may arrange a merger, purchase-and-assumption transaction or another resolution. Qualifying insured shares are handled under the applicable NCUSIF rules. See What Happens If a Credit Union Fails?.

    What Happens to Your Money If a Credit Union Closes?

    If a federally insured credit union is liquidated, NCUA handles the resolution and provides affected members with instructions. Depending on the resolution, another institution may assume certain accounts, loans and services, or NCUA may arrange payment of qualifying insured shares. The exact process depends on the individual liquidation.

    Members should follow official instructions about account access, direct deposits, automatic payments and any required claims or documentation. Do not rely on unsolicited messages claiming to represent NCUA or the failed credit union. For more detail, read What Happens to Your Money If a Credit Union Closes?.

    Can a Credit Union Close Your Account?

    An individual member’s account is different from a credit union-wide failure. A credit union may restrict or close an individual account according to its account agreement, applicable law and circumstances. Possible situations can include suspected fraud, unusual activity, legal or regulatory requirements, or other reasons permitted under the account terms. The exact process and notice requirements can vary.

    If you receive an account-closure notice, review it carefully and contact the credit union through an official channel. Ask how remaining funds will be returned, whether outstanding transactions must be resolved and whether any appeal or dispute process is available. See Can a Credit Union Close Your Account?.

    SituationWhat It MeansMember Focus
    Fraud ConcernSuspicious activity may lead to account restrictions, investigation or other action.Contact the credit union through verified channels.
    ConservatorshipA conservator takes control while the credit union’s problems are addressed.Follow official instructions and monitor account access.
    LiquidationThe credit union closes and its assets and member claims are handled through a resolution process.Follow NCUA instructions and arrange alternative banking access when needed.
    Individual Account ClosureOne member’s account may be restricted or closed under applicable terms and law.Review the notice and resolve remaining transactions or funds.

    SAFETY CHECK

    Think about safety in three layers: protect your login, verify your credit union’s insurance status, and know what official steps apply if an account or institution has a problem. When something unexpected happens, use verified contact information and official NCUA resources rather than responding to unsolicited messages.

    Credit Union Pros, Cons & Who Should Join

    A credit union can be a practical choice for people who qualify for membership and value a member-owned financial cooperative. But the experience depends on the specific institution. Fees, rates, account features, branch access, digital tools and loan products can differ significantly, so the credit union model itself should not be the only factor in your decision.

    Potential Benefits of Credit Unions

    Credit unions are member-owned, not-for-profit cooperatives. Their structure is designed to provide financial services to members rather than operate for stockholder ownership. That structure can be attractive to people who want a cooperative relationship with their financial institution. NCUA explains that credit unions provide members with opportunities to save, borrow and obtain related financial services.

    • Member ownership: Members have an ownership relationship with the cooperative.
    • Product choice: Many credit unions offer checking, savings, certificates and loans under one membership.
    • Potentially competitive terms: Some credit-union products may have competitive rates or fees, but this varies by institution and product.
    • Federal share insurance: Qualifying shares at federally insured credit unions can receive NCUSIF coverage subject to applicable limits and ownership rules.
    • Personal access: Some members value local branches, shared branching and member-focused service.

    Potential Drawbacks to Consider

    The cooperative structure does not guarantee that every credit union will have the lowest fees, highest savings rate or most convenient technology. A smaller branch footprint, limited product selection or less extensive digital functionality can matter if you rely heavily on those services.

    • Membership eligibility: You must qualify under the credit union’s field of membership.
    • Access can vary: Branches and ATMs may be less convenient in some locations, although shared networks can expand access.
    • Technology differences: Mobile apps, online banking and digital features vary between institutions.
    • Account requirements: Some products may have minimum balances, membership shares or other conditions.
    • Product differences: A credit union may not offer every financial product or service you want.

    For a broader breakdown, see Credit Union Pros and Cons.

    Who May Want to Consider a Credit Union?

    A credit union may be worth considering if you qualify for membership and its combination of accounts, fees, rates, access and services fits your needs. It can be especially relevant if you value a cooperative ownership structure, local or shared-branch access, or a particular savings or lending product offered by that institution.

    It may be less convenient if you need a very large branch or ATM footprint, a particular digital feature, or financial products that the credit union does not offer. The important question is not simply whether you can join, but whether the institution’s actual terms work for you.

    A Simple Comparison Checklist

    FactorQuestion to AskWhy It Matters
    MembershipDo I qualify?Eligibility comes before account access.
    FeesWhat will I actually pay?Fees can change the real cost of banking.
    RatesHow does the actual APY or APR compare?Headline rates do not tell the whole story.
    AccessCan I access my money conveniently?Branches, ATMs, shared branching and digital tools all matter.
    InsuranceIs the credit union federally insured?Insurance status and ownership category affect applicable coverage.

    DECISION CHECK

    A credit union is worth evaluating when membership eligibility, account terms, fees, rates, access and services line up with your needs. Compare the actual institution and account rather than assuming the credit-union label guarantees a particular outcome.

    If you want to take the next step, our guide Who Should Join a Credit Union? focuses specifically on membership fit and common situations where a credit union may or may not make sense.

    Credit Union FAQs, Resources & Final Takeaway

    Are Credit Unions Safe?

    A federally insured credit union can provide federal share insurance for qualifying member accounts through the National Credit Union Share Insurance Fund, subject to applicable limits and ownership rules. The standard coverage for an individual account is generally $250,000. Always verify the specific credit union’s insurance status before depositing money.

    Is NCUA Insurance the Same as FDIC Insurance?

    They serve similar purposes but cover different types of institutions. NCUA’s Share Insurance Fund covers qualifying shares at federally insured credit unions, while FDIC insurance covers qualifying deposits at FDIC-insured banks. The two systems have separate rules and coverage structures.

    Can Anyone Join a Credit Union?

    No. You generally need to meet the credit union’s membership eligibility requirements, which are defined by its field of membership. Eligibility can be based on factors such as a qualifying employer, association, geographic community or family relationship, depending on the institution.

    Do Credit Unions Have Lower Fees Than Banks?

    Not automatically. A credit union may offer competitive fees on a particular account, but fees vary by institution and product. Compare the actual monthly fee, minimum balance, ATM charges, overdraft terms and other service costs before choosing an account.

    Can I Use a Credit Union Outside My Local Area?

    Possibly. Participating credit unions may provide access through shared branches and ATM networks. Digital banking can also allow you to manage many routine transactions remotely. Availability and supported services depend on the credit union and networks it uses.

    What Should I Compare Before Joining?

    Start with membership eligibility, then compare the account’s fees, minimum balance, APY or dividend terms, ATM access, digital banking, insurance status and customer-service options. If borrowing is important, compare actual loan offers using APR, fees, repayment term and total borrowing cost. Our Who Should Join a Credit Union? guide can help with the final decision checklist.

    Official Credit Union Resources

    For information that can affect your money, use official sources in addition to comparison articles. The NCUA Share Insurance Coverage page explains federal share insurance, ownership categories and qualifying accounts. NCUA also provides a Share Insurance Estimator for checking how coverage can apply to specific account situations.

    You can also use the NCUA consumer resources to access the Credit Union Locator and Consumer Assistance Center. NCUA says its Consumer Assistance Center helps consumers with certain credit-union disputes and provides information about federal consumer financial protection laws and share insurance. 1

    FINAL TAKEAWAY

    A credit union can provide checking, savings, certificates, payment access and borrowing under a member-owned structure. But the credit-union label alone does not tell you whether a particular account fits your needs. Check eligibility, fees, rates, access, services and insurance before joining.

    Have a Money Question? Keep Exploring.

    Banking decisions are easier when you understand the rules, costs and trade-offs before opening an account. Keep exploring FinanceInvestment for practical guides designed to help you make informed financial decisions.
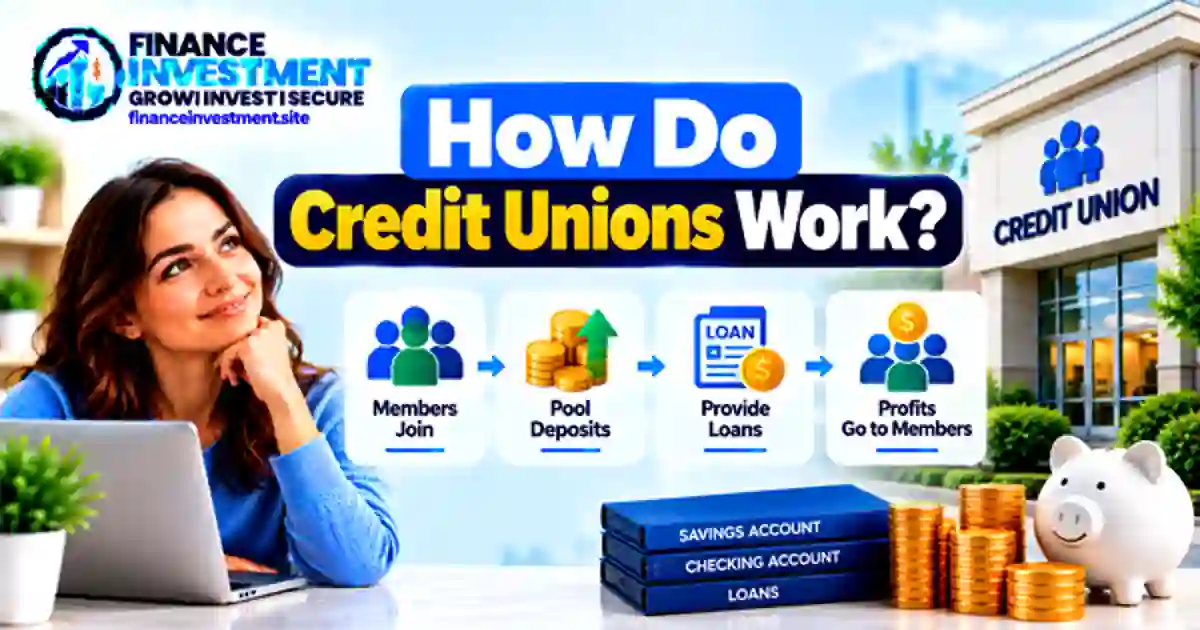
    📩 Get in Touch With FinanceInvestmentEmail FinanceInvestment