How to Protect More Than $250,000 in Bank Deposits
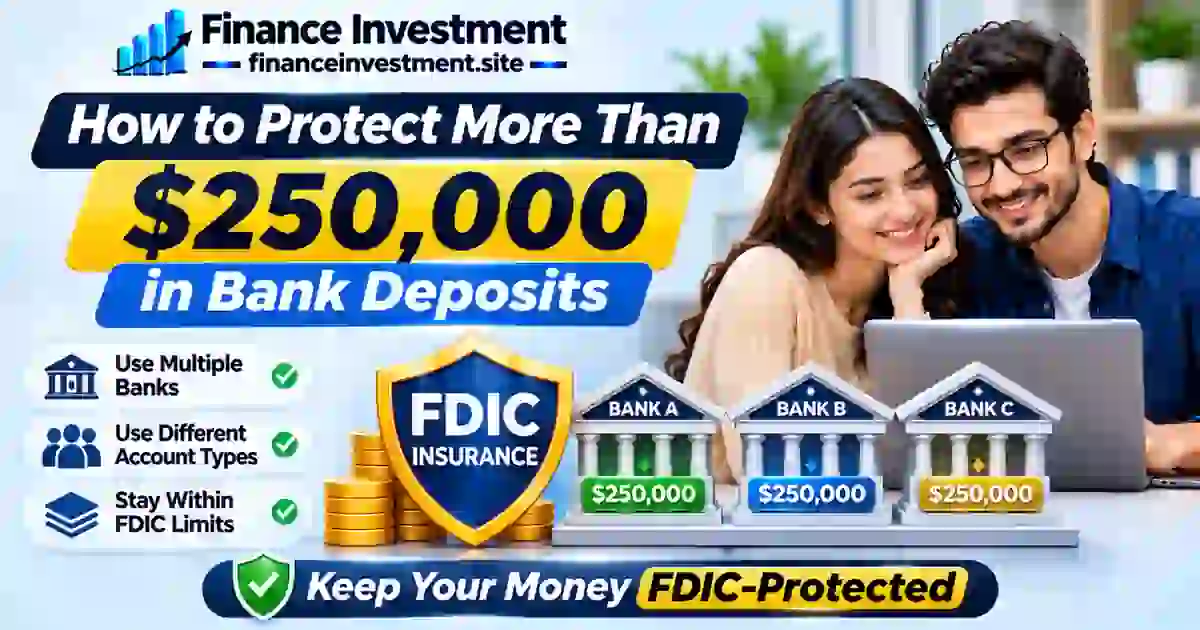
How Can You Protect Savings Above the FDIC Limit?
Imagine you’ve saved $400,000 for retirement, a home purchase or your family’s future. The money is sitting in a savings account at an FDIC-insured bank. But is the entire balance protected if that bank fails?
Not necessarily. If you own the account individually and have no other qualifying coverage at that bank, the standard $250,000 single-ownership limit could leave $150,000 uninsured, assuming the balance includes all accrued interest.
Understanding how to protect more than $250,000 in bank deposits starts with knowing how ownership categories and insured banks affect your coverage. You can review the basics in our FDIC and NCUA insurance guide.
This guide explains practical ways to arrange larger cash balances without assuming that opening another account automatically increases protection.
What You’ll Learn
- How FDIC limits apply to large deposits.
- Ways to increase eligible deposit insurance coverage.
- When multiple banks, joint accounts and trusts help.
- Which mistakes can leave part of your savings uninsured.
Quick Answer: How to Protect More Than $250,000
Quick Answer: Spread larger balances across separately FDIC-insured banks, use eligible ownership categories, or consider qualifying deposit-placement services. Properly structured joint and trust accounts may increase coverage. Check each bank’s insurance status and include accrued interest when calculating your protection.
6 Key Takeaways
- Use separate banks: Different branches of one insured bank share the same applicable limits.
- Check ownership: Qualifying single and joint accounts are insured separately.
- Review trust rules: Additional coverage depends on eligible owners, beneficiaries and FDIC requirements.
- Examine deposit networks: Confirm participating banks, allocations and overlapping deposits.
- Allow for interest: Accrued interest counts toward insured balances.
- Calculate first: Use the official FDIC EDIE calculator to estimate coverage.
Bottom Line: Protecting a large cash balance is about where your deposits are held and how they’re legally owned—not simply how many accounts you open.
Table of Contents
At a Glance: FDIC Limits for Larger Deposits
The amount insured depends on your bank, account ownership and other deposits held in the same ownership category.
Coverage Options Compared
| Account Arrangement | Potential FDIC Coverage |
|---|---|
| Single-owner deposits | Up to $250,000 per owner, per insured bank, in this category |
| Qualifying two-owner joint deposits | Up to $500,000 combined, subject to other joint deposits |
| Eligible trust deposits | Generally up to $250,000 per eligible beneficiary, per owner, capped at five beneficiaries per owner |
| Deposits at different insured banks | Separate applicable insurance limits at each bank |
Quick Take: Useful for families, retirees and high-balance savers. Include accrued interest and all deposits in the same ownership category before calculating available protection.
Understanding the $250,000 FDIC Insurance Limit
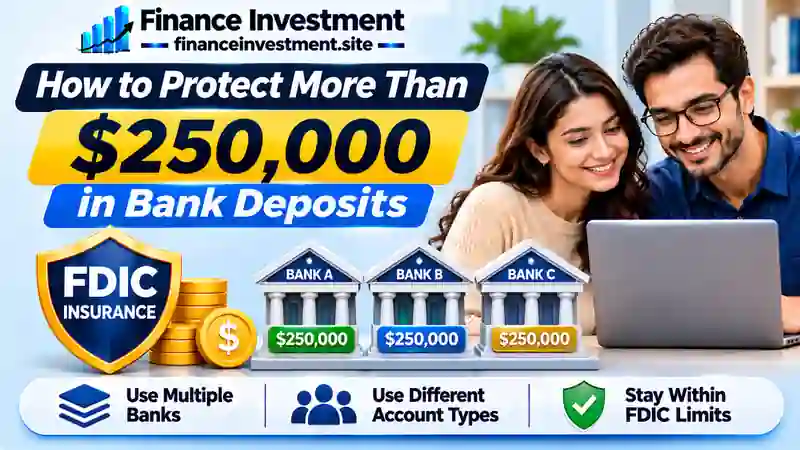
You can deposit more than $250,000 at a bank. The important question is how much of that money would be insured if the institution failed.
FDIC insurance generally covers up to $250,000 per depositor, per FDIC-insured bank, per ownership category. The limit applies to combined eligible deposits within the same category, not separately to every account.
Which Deposits Count?
Eligible products include checking accounts, savings accounts, money market deposit accounts and certificates of deposit (CDs). Accrued interest counts toward your insured balance. Stocks, mutual funds and Treasury securities are not FDIC-insured deposits.
Suppose you hold $180,000 in individual savings and $100,000 in an individual CD at one insured bank. Together, that’s $280,000. Assuming these figures include accrued interest and you have no other applicable coverage, $30,000 exceeds the single-ownership limit.
One Bank or Two?
Opening another account at a different branch of the same insured bank won’t increase your limit. Deposits at separately FDIC-insured banks receive their own applicable coverage.
See our guide to FDIC insurance at different banks for examples.
Important: FDIC insurance protects eligible deposits against insured-bank failure. It does not cover investment losses or serve as general protection against fraud.
5 Practical Ways to Protect More Than $250,000 in Bank Deposits
Large cash balances deserve a plan that protects your money without making everyday banking unnecessarily complicated. Here are five approaches worth considering.
1. Spread Money Across Separate FDIC-Insured Banks
For example, place $200,000 at each of three separately insured banks. That can protect $600,000 under the single-ownership category, assuming no other deposits reduce your available coverage and accrued interest stays within each limit. Different branches of one bank don’t count as separate institutions.
2. Use Joint Accounts When Ownership Makes Sense
A qualifying account with two eligible co-owners can receive up to $500,000 in combined joint-category coverage at one bank. Each owner’s interests in other joint accounts at that bank also count. Read our joint account FDIC coverage guide before adding an owner.
3. Review Eligible Trust Account Coverage
Qualifying trust deposits generally receive up to $250,000 per eligible beneficiary, per owner, with a maximum of five beneficiaries counted per owner. Trust deposits belonging to the same owner at one bank are aggregated. Our revocable trust insurance guide explains the requirements.
4. Ask About Insured Deposit-Placement Services
Some banks distribute large balances among participating FDIC-insured banks. Before enrolling, request the receiving-bank list, deposit allocations, fees and access terms. Existing balances at those banks can affect your coverage.
5. Consider Federally Insured Credit Unions
The NCUA separately insures eligible share deposits at federally insured credit unions, generally up to $250,000 per member, per insured credit union, per ownership category. Compare the rules in our NCUA vs. FDIC insurance guide.
Important: Verify each institution’s insurance status and account records before transferring money. Changing ownership may affect access, inheritance rights and taxes.
Benefits and Drawbacks of Protecting Large Bank Deposits
Expanding eligible deposit coverage can reduce your exposure to bank failure. However, additional accounts and ownership arrangements bring responsibilities worth considering.
Benefits: Why Additional Coverage Helps
- Reduced exposure: Less money remains uninsured if an insured bank fails.
- Flexible options: Eligible checking, savings and CD deposits can fit different goals.
- Financial confidence: Larger cash reserves can be held within applicable insurance limits.
- Choice: You can compare institutions, rates and account features.
Drawbacks: What to Consider
- More administration: Multiple accounts require balance tracking.
- Access limitations: Transfers and CDs may involve delays or penalties.
- Potential costs: Some deposit services charge fees.
- Legal complexity: Joint or trust ownership may affect control and inheritance.
Quick Perspective: Deposit insurance addresses insured-institution failure, not inflation or poor investment returns. Aim for adequate coverage without sacrificing necessary liquidity or simplicity.
Large-Deposit Protection Strategies Compared
Compare these five approaches by insurance potential, practical use and limitations before deciding how to organize a substantial cash balance.
| Strategy | Coverage Potential | Best For | Key Limitation |
|---|---|---|---|
| Separate FDIC-insured banks | Separate applicable limits at each bank | Individual savers | Balance tracking |
| Qualifying joint accounts | Up to $500,000 combined for two eligible owners | Genuine co-owners | Shared ownership rights |
| Eligible trust accounts | Based on owners and eligible beneficiaries, subject to FDIC limits | Estate-planning needs | Trust eligibility rules |
| Deposit-placement services | Combined eligible coverage across receiving banks | Very large balances | Bank overlap, fees and access |
| Federally insured credit unions | Separate NCUA share insurance limits | Eligible members | Membership and insurance eligibility |
Coverage note: Limits depend on eligible ownership, other deposits at each institution and accrued interest. NCUA share insurance is distinct from FDIC insurance.
Quick Take: Using separate insured banks is often the simplest starting point. Joint and trust accounts should serve genuine ownership or estate-planning purposes, not merely increase insurance limits.
Costs, Risks and Expert Tips for Large Bank Deposits
FDIC coverage is automatic for eligible deposits at insured banks, with no separate insurance premium charged to depositors. Still, managing substantial balances can involve expenses and practical risks.
Costs to Review
- Account charges: Maintenance fees and minimum-balance requirements.
- Transfers: Wire fees, processing times and transaction limits.
- Deposit services: Potential fees, rate differences and withdrawal conditions.
- CD withdrawals: Early-withdrawal penalties that may sometimes reduce principal.
Risks Beyond Bank Failure
Accrued interest can push balances beyond insurance limits. Existing deposits at partner banks may also reduce available coverage. Inflation affects purchasing power, while incorrect transfer instructions can expose funds to fraud.
Expert Tip: Verify Before Moving Money
Check your estimated coverage using FDIC EDIE and verify the institution through FDIC BankFind. Confirm transfer instructions using a trusted bank contact method.
For additional guidance, read our large bank transfer guide.
5 Common Mistakes When Protecting Large Bank Deposits
A deposit can exceed its insurance limit even when the account looks properly organized. Watch for these common mistakes.
- Opening extra accounts at one bank: Accounts in the same ownership category are generally combined.
- Confusing branches with separate banks: Branch locations don’t create independent insurance limits.
- Forgetting accrued interest: Interest can push an otherwise insured balance above its limit.
- Misunderstanding beneficiary rules: Naming beneficiaries doesn’t automatically guarantee additional trust coverage.
- Overlooking partner-bank deposits: Existing balances may reduce insurance available through placement networks.
Example: How a Couple Could Protect $800,000
Imagine a married couple dividing their cash between two separately FDIC-insured banks:
- Bank A: $400,000 in a qualifying joint account owned by both spouses.
- Bank B: $200,000 in each spouse’s separate individual account.
The full $800,000 could be insured if both spouses qualify, no other deposits reduce available coverage, and balances including accrued interest remain within applicable limits.
Key Lesson: Verify ownership and total deposits at each insured bank before assuming a family balance is fully protected.
Which Deposit Protection Strategy Fits Your Needs?
The most practical arrangement depends on who owns the money, when it may be needed and how much administration you’re comfortable managing.
For Families
Qualifying joint accounts can suit genuine co-owners. Trust deposits may fit established estate plans, provided the applicable insurance requirements are met.
For Retirees
Separate insured banks may help protect retirement cash reserves. Savings accounts offer easier access, while CDs may impose early-withdrawal penalties.
For Investors and High-Balance Savers
Deposit-placement services can simplify distributing cash across banks. Check fees, receiving institutions and existing deposits before enrolling.
Quick Perspective: Match insurance coverage with genuine ownership needs and the amount of cash you must keep readily available.
Frequently Asked Questions About FDIC Insurance Over $250,000
1. Can I keep more than $250,000 in one bank?
Yes. You can hold larger balances, but amounts exceeding your applicable FDIC coverage may be uninsured if the bank fails.
2. Do multiple savings accounts increase FDIC coverage?
Not by themselves. Eligible deposits owned by the same person in the same ownership category at one insured bank are combined.
3. Can a joint account insure $500,000?
Yes, if two eligible co-owners each have $250,000 of available joint-category coverage at that bank and the account meets FDIC requirements.
4. Can trust beneficiaries increase FDIC coverage?
Qualifying trust deposits generally receive up to $250,000 per eligible beneficiary, per owner, counting no more than five beneficiaries per owner at one bank.
5. Are deposits at different banks insured separately?
Yes. Separately FDIC-insured banks have independent limits. Different branches of the same insured bank do not.
6. Are insured deposit-placement services safe?
They can extend eligible coverage across participating banks. Verify allocations, existing deposits at receiving banks, fees and withdrawal terms.
7. Does FDIC insurance cover credit union deposits?
No. Eligible deposits at federally insured credit unions receive separate NCUA share insurance, generally with a $250,000 standard limit per member, per insured credit union, per ownership category.
8. How do I calculate my FDIC insurance coverage?
Use the official FDIC EDIE calculator. Enter your deposits, ownership categories and applicable beneficiary details to estimate coverage.
Final Verdict: How to Protect More Than $250,000 Safely
Learning how to protect more than $250,000 in bank deposits starts with understanding where your money is held and how each account is owned. For many individual savers, using separately FDIC-insured banks is a straightforward approach.
Joint accounts, qualifying trusts and deposit-placement services may offer additional coverage when their requirements are met. Before moving funds, check existing deposits, accrued interest, ownership records and withdrawal conditions.
Our Recommendation: Calculate your available insurance coverage first. Then address any uninsured balance using an arrangement that preserves appropriate access and avoids unnecessary complexity.
For the underlying rules, explore our complete FDIC and NCUA insurance guide.
Have a Money Question? Keep Exploring.
Have a question about protecting your savings? Explore our deposit insurance guides or get in touch with FinanceInvestment.
📩 Get in Touch With FinanceInvestment
Disclaimer: This content is for general education, not personalized financial, legal or tax advice. Insurance eligibility depends on applicable rules and account records. Confirm coverage with the FDIC or NCUA before making decisions.