Credit Union Loans vs Bank Loans
Credit Union Loans vs Bank Loans: Which Is Better for Borrowers?
When comparing Credit Union Loans vs Bank Loans, the interest rate is an important starting point, but it should not be the only number you compare. The right loan can depend on the APR, fees, repayment term, loan amount, credit profile, approval requirements, and the service you expect from the lender.
Credit unions are member-owned, not-for-profit financial cooperatives, while banks are generally for-profit financial institutions. This difference can influence how lenders structure products and serve borrowers. Still, a credit union loan is not automatically cheaper than a bank loan. Your individual offers, including the rate, fees, and total repayment cost, are what really matter.
If you are new to credit unions, our complete guide to credit unions explains how they work, who can join, and what services they provide before you compare loan options.
What You’ll Learn
- How credit union loans and bank loans work
- How APRs, fees, loan terms, and qualification can differ
- The key benefits and drawbacks of each lender type
- Which option may fit different borrowing situations
- What to compare before accepting a loan offer
Quick Answer: Credit Union Loans vs Bank Loans
Quick answer: Neither a credit union nor a bank is automatically the better choice for every borrower. A credit union may offer competitive loan pricing and more personalized service, while a bank may provide wider access, a larger branch network, and convenient digital tools. The better choice comes down to the specific loan offers, costs, and terms available to you.
Before choosing a lender, compare the APR, interest rate, total interest, fees, repayment term, monthly payment, and qualification requirements. A lower monthly payment is not always a better deal because a longer repayment term can increase the total amount you pay over the life of the loan.
Key Takeaways
- Credit unions: Member-owned institutions that may combine competitive loan offers with a more relationship-focused lending experience.
- Banks: For-profit institutions that often provide broad product choices, convenient access, and established digital banking services.
- Loan offers vary: Your credit history, loan type, amount, term, and lender can affect the rate and terms you receive.
- Membership matters: You generally must meet a credit union’s eligibility requirements before becoming a member and applying for its loans.
- Compare the full cost: Look beyond the advertised rate and consider the total amount you will repay over the entire loan term.
Table of Contents
Credit Union Loans vs Bank Loans at a Glance
| Factor | Credit Union | Bank |
|---|---|---|
| Ownership | Member-owned, not-for-profit cooperative | Generally a for-profit financial institution |
| Loan pricing | Rates and fees vary by lender, loan, and borrower | Rates and fees vary by lender, loan, and borrower |
| Eligibility | Membership eligibility generally applies | Generally open to eligible customers without a membership field-of-membership requirement |
| Access | Varies; some offer shared branching and broad ATM access | Often offers broad branch, ATM, and digital access |
| What to compare | APR, fees, term, payment, eligibility, and service | APR, fees, term, payment, access, and lender features |
QUICK TAKE: A credit union may be worth considering if you qualify for membership and its loan offer is competitive for your situation. A bank may appeal if convenient access, digital tools, or a broad product lineup matters more to you. Either way, compare the actual APR, fees, repayment term, monthly payment, and total borrowing cost before choosing.
Complete Beginner Guide to Credit Union Loans vs Bank Loans
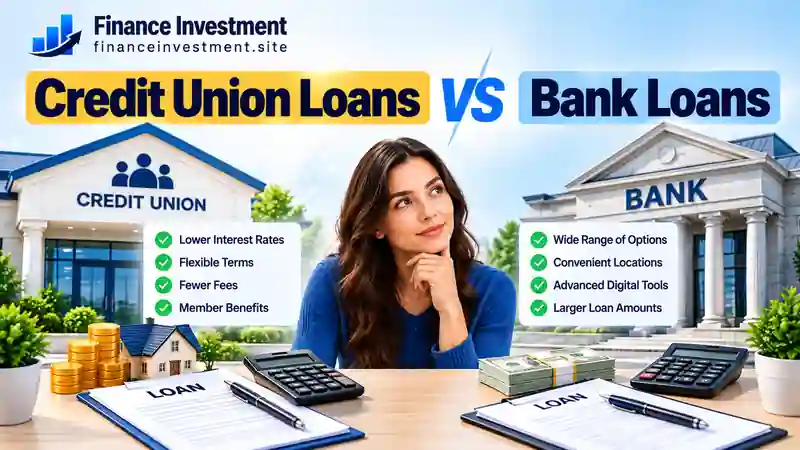
If you are comparing lenders for the first time, do not treat a loan like a simple price tag. Two lenders can offer different APRs, fees, repayment terms, approval standards, and borrower requirements. That is why Credit Union Loans vs Bank Loans deserves a broader comparison than simply asking which lender has the lowest advertised rate.
What Is a Credit Union Loan?
A credit union loan is financing provided by a member-owned, not-for-profit financial cooperative. You generally need to qualify for membership before applying. Depending on the credit union, members may have access to products such as personal loans, auto loans, credit cards, and mortgages. The cooperative structure can also support a more relationship-focused lending experience.
If you are unsure whether you qualify, our guide to credit union membership requirements explains the basic eligibility concept before you apply.
What Is a Bank Loan?
A bank loan is financing provided by a bank. Depending on the institution, borrowers may find personal loans, auto financing, mortgages, credit cards, business loans, and other lending products. Banks may also provide extensive branch networks, ATMs, mobile apps, online banking, and other services that can make borrowing and account management convenient.
What Actually Determines the Better Loan?
Start with the specific offers available to you. Compare the APR, interest rate, fees, loan term, monthly payment, total repayment amount, collateral requirements, and any prepayment or late-payment terms. Your credit history, income, debt obligations, loan amount, and other factors may affect the terms you receive. The better choice is the loan that provides an acceptable total cost and repayment structure while fitting your financial needs and lender-access preferences.
How Credit Union and Bank Loans Work
The basic borrowing process is similar at a credit union and a bank. You choose a loan, apply, provide financial information, and the lender evaluates your application. If approved, you review the offer, receive the funds according to the agreement, and make scheduled payments. The exact process can vary by lender and loan type.
1. Check Eligibility
If you choose a credit union, first check whether you meet its membership requirements. Banks generally do not have the same field-of-membership structure. Both types of lenders can set their own credit, income, debt, employment, collateral, and other qualification standards for specific loans.
2. Compare Loan Offers
Compare more than the advertised interest rate. Review the APR, fees, repayment term, monthly payment, total repayment amount, and rate structure when applicable. For personal loans, check whether an origination fee applies and whether the lender places restrictions on how you can use the funds.
3. Apply and Provide Information
Depending on the lender and loan, you may need identification, income details, employment information, housing details, and authorization for a credit review. Some applications may also require documentation related to the asset securing the loan.
4. Review, Accept, and Repay
Before accepting an offer, confirm the APR, payment amount, due dates, fees, repayment term, collateral requirements, and other important conditions. Once the loan is funded, make payments according to the agreement and keep your records until the balance is fully paid.
Benefits & Drawbacks of Credit Union and Bank Loans
Neither lender type is automatically better for every borrower. A credit union may appeal to someone who values member-focused service and receives a competitive loan offer, while a bank may be a better fit for someone who prioritizes convenience, access, or a broad range of financial products.
Credit Union Benefits
- May provide competitive loan rates or fees for qualified members.
- Member-owned structure can support a relationship-focused borrowing experience.
- Local or community-focused service may appeal to some borrowers.
- Some credit unions participate in shared branching or other cooperative services.
Credit Union Drawbacks
- You generally need to meet membership eligibility requirements.
- Branch and ATM access can vary significantly by institution.
- Some smaller institutions may have fewer products or digital features.
- Loan rates, fees, and approval standards still vary by lender.
Bank Benefits
- Many banks provide broad branch, ATM, and online access.
- May offer a wide range of lending and other financial products.
- Larger institutions may provide extensive digital banking tools.
- Banks generally do not use a credit union-style field-of-membership requirement.
Bank Drawbacks
- Loan rates and fees can vary significantly among banks and products.
- Service may feel less personalized at some larger institutions.
- Convenience does not necessarily mean the loan has the lowest total cost.
- Approval terms still depend on your financial profile and the lender’s criteria.
Bottom line: Use the lender type as a starting point, not the final decision. Compare the actual offers available to you, including APR, fees, repayment term, monthly payment, total cost, service, and access. The better loan is the one that fits your borrowing needs without putting unnecessary pressure on your budget.
Credit Union Loans vs Bank Loans: Detailed Comparison
The difference between credit union loans and bank loans goes beyond the interest rate. Ownership, membership eligibility, pricing, fees, access, digital services, and lender requirements can all affect your borrowing experience. Use this comparison as a starting point, then review the actual offers you qualify for.
| Factor | Credit Union Loans | Bank Loans |
|---|---|---|
| Ownership | Member-owned, not-for-profit cooperative | Generally a for-profit financial institution |
| Eligibility | Membership eligibility generally applies | Generally no credit-union-style field-of-membership requirement |
| Loan rates | May be competitive; actual offer varies by lender and borrower | Varies by lender, product, and borrower |
| Fees | Depend on the credit union and loan product | Depend on the bank and loan product |
| Approval | Based on lender criteria and borrower financial profile | Based on lender criteria and borrower financial profile |
| Customer service | May provide a more relationship-focused experience | Service model varies by bank and channel |
| Branches & ATMs | Access varies; some use shared or cooperative networks | Often broad at larger banks, but varies by institution |
| Digital services | Features vary by credit union | Features vary; larger banks often provide extensive digital tools |
| Best comparison metric | APR, fees, term, payment, and total repayment | APR, fees, term, payment, and total repayment |
Smart comparison tip: When two lenders offer similar loan amounts, compare the full cost of each offer rather than focusing on one number. A lower advertised rate may not produce the better deal if fees, loan terms, or other charges increase what you ultimately repay.
Costs, Risks & Expert Tips
The loan with the lowest advertised rate is not automatically the lowest-cost option. When comparing Credit Union Loans vs Bank Loans, look at the complete cost of borrowing and the risks attached to the repayment terms. APR, fees, loan length, and payment structure can all affect what you ultimately pay.
Costs to Watch
- APR and interest: Compare the APR and understand the interest terms stated in the loan agreement.
- Loan fees: Depending on the product, you may encounter origination, application, documentation, or other charges. Check the lender’s disclosures.
- Late-payment costs: A missed payment may result in fees and can potentially affect your credit history.
- Longer repayment terms: A longer term can lower the required monthly payment while increasing the total interest paid.
Risks to Consider
Taking on a payment that does not fit your budget can create financial stress and increase the risk of missed payments. With a secured loan, the pledged asset may also be at risk if you default. Before signing, understand the consequences of missed payments, the rules for paying the loan early, and any conditions that could change your cost.
Expert Tips for Comparing Offers
- Compare offers from multiple lenders when practical, rather than relying on one quote.
- Compare APR, fees, repayment term, monthly payment, and total repayment together.
- Ask whether the rate is fixed or variable when that distinction applies to the loan.
- Read the complete loan agreement and required disclosures before accepting the offer.
- Do not choose a longer term only because the monthly payment looks easier to manage.
Common Mistakes + Real-Life Example
Loan comparisons often go wrong because borrowers focus on one attractive number. A lower rate, smaller monthly payment, or familiar bank name does not tell you the full story. The better approach is to compare the complete loan offer before making a decision.
Common Mistakes to Avoid
- Choosing the lowest advertised rate: The advertised rate may not show every fee or the full borrowing cost.
- Comparing monthly payments only: A longer term can reduce the payment while increasing total interest.
- Ignoring eligibility: You generally need to meet a credit union’s membership requirements before applying for its loans.
- Borrowing beyond your budget: Approval does not mean the payment is comfortable or financially appropriate for you.
- Skipping the loan agreement: Review fees, payment terms, collateral requirements, and other conditions before accepting the loan.
Real-Life Example
Consider this hypothetical example: a borrower needs $20,000 and receives two offers. The credit union quotes a slightly lower APR but charges a fee, while the bank offers a slightly higher APR with a different term and fee structure. Instead of choosing the lower rate automatically, the borrower compares the monthly payment, total interest, fees, and total repayment amount. If the bank’s offer results in a lower overall cost or a repayment schedule that better fits the budget, it may be the better choice. The lesson is simple: compare the complete offers, not just the headline rate.
Who Should Choose a Credit Union or Bank Loan?
The right lender depends on your financial situation, the loan you need, and the specific offer available to you. A credit union may suit one borrower while a bank may suit another. The goal is to match the lender with your borrowing needs rather than choosing based only on the institution’s name.
A Credit Union May Fit If You:
- Meet the credit union’s membership requirements.
- Receive a loan offer with competitive overall terms.
- Prefer a relationship-focused lending experience.
- Value local or cooperative financial services.
A Bank May Fit If You:
- Value convenient branch, ATM, or digital access.
- Prefer to manage several financial products through one institution.
- Want access to the digital tools and services offered by your bank.
- Receive a loan offer with suitable rates, fees, and repayment terms.
Best approach: If both options are available, compare the actual offers side by side. Consider your credit profile, loan purpose, repayment ability, total borrowing cost, and preferred level of access before making the final decision.
Frequently Asked Questions About Credit Union Loans vs Bank Loans
1. Are credit union loans cheaper than bank loans?
Not necessarily. Credit unions may offer competitive rates or fees, but pricing varies by lender, loan type, and borrower. Compare the APR, fees, repayment term, and total repayment amount for the specific offers you receive.
2. Is it easier to get a loan from a credit union?
There is no universal answer. Each lender sets its own underwriting standards. Your credit history, income, existing debt, loan amount, and other factors can affect approval and the terms offered.
3. Do I need to be a credit union member to get a loan?
Generally, yes. You normally need to meet the credit union’s membership eligibility requirements before accessing its member products, including loans.
4. Do banks offer better loan options than credit unions?
Not automatically. Banks may offer broad product selections and convenient digital or branch access, while credit unions may appeal to borrowers who value cooperative, relationship-focused service. The actual loan offer matters most.
5. Which is better for a personal loan, a credit union or bank?
Either can be a good choice. Compare APR, origination fees if applicable, repayment term, monthly payment, total repayment, funding time, and other loan conditions before choosing.
6. Can a credit union help borrowers with less-than-perfect credit?
Some credit unions may consider a broader range of borrower circumstances, but approval is never guaranteed. Ask about the lender’s credit criteria and compare the terms you actually qualify for.
7. Are credit union loans insured like bank loans?
Federal credit union share accounts can be insured by the National Credit Union Administration, while deposits at FDIC-insured banks can be insured by the Federal Deposit Insurance Corporation, subject to applicable limits and rules. This insurance protects qualifying deposits or shares, not the outstanding balance of a loan you owe.
8. What should I compare before choosing a lender?
Compare the APR, interest rate, fees, repayment term, monthly payment, total repayment amount, collateral requirements, prepayment terms, and lender service. Choose the offer that fits both your borrowing needs and your repayment budget.
Final Verdict: Credit Union Loans vs Bank Loans
There is no universal winner in the Credit Union Loans vs Bank Loans comparison. A credit union may fit you if you meet its membership requirements, prefer a relationship-focused experience, and receive a strong loan offer. A bank may be a better fit if convenient access, digital services, or a broader financial product lineup matters more to you.
The most reliable way to choose is to compare the actual offers available to you. Review the APR, fees, repayment term, monthly payment, total repayment amount, collateral requirements, and other loan conditions. A lower advertised rate or smaller monthly payment does not necessarily mean a lower overall cost.
Our takeaway: Choose the lender whose loan fits your borrowing needs, repayment budget, and preferred level of service while offering terms you understand and can comfortably manage. If practical, compare both credit unions and banks before making your final decision.
Related Resources for Smarter Borrowing
Want to dig deeper before choosing a lender? These FinanceInvestment guides cover the credit union topics that matter when comparing borrowing options, from membership and fees to insurance and the broader credit union-versus-bank relationship.
- Credit Unions Explained — Learn how credit unions work and how their member-owned structure differs from banks.
- Credit Union Membership Requirements — Check the eligibility concept before applying for membership or a loan.
- Credit Union Fees Explained — Understand fees that may affect the overall cost of using a credit union.
- NCUA vs FDIC Insurance — Compare the federal insurance systems that protect qualifying deposits and credit union shares.
- Credit Union vs Bank — Explore the broader differences between the two financial institution types.
Trusted Sources
For authoritative consumer-finance and credit-union information, visit the Consumer Financial Protection Bureau (CFPB) and the National Credit Union Administration (NCUA).