Treasury Bills for Emergency Funds
Treasury Bills for Emergency Funds: A Practical Starting Point
 Treasury Bills for Emergency Funds can be worth considering if you want part of your short-term reserves invested in U.S. government securities. But an emergency fund has a different priority from a regular investment account: you need to be able to reach the money when an unexpected bill arrives.
That is why liquidity matters before yield. A T-bill has a stated maturity date, while cash in a checking or savings account can generally be accessed without waiting for a security to mature. Some people may therefore keep their most immediate emergency cash in an accessible account and use shorter-term T-bills for money they may not need right away.
If Treasury bills are new to you, our Treasury Bills Explained guide is a useful starting point. It covers what T-bills are and how they work before you decide whether they fit your emergency-fund plan.
What You’ll Learn
- Where T-bills can fit within an emergency-fund strategy.
- Why immediate access can matter more than yield for emergency cash.
- How T-bill maturities affect when invested money becomes available.
- The potential benefits and drawbacks of using T-bills.
- How T-bills compare with savings and money market accounts.
- What to consider before using T-bills for unexpected expenses.
The central question is not simply whether T-bills are safe or offer a competitive return. It is whether the maturity, access, and structure of the investment match the kind of emergency you are preparing for.
Quick Answer: Can Treasury Bills Be Used for Emergency Funds?
Yes, Treasury bills can be part of an emergency-fund strategy, but they may not be suitable for every portion of your reserve. Emergency money needs dependable access. Because a T-bill has a maturity date, it can require more planning than cash held in an accessible bank account. Keeping some emergency savings readily available can reduce the chance of needing to sell a T-bill at an inconvenient time.
Key Takeaways
- Liquidity matters: The money you may need immediately should be easy to access without relying on a security sale.
- Maturity dates matter: A T-bill follows a defined maturity schedule, so the timing should fit your expected cash needs.
- Shorter maturities offer more frequent planning points: They can give you more opportunities to reassess the money as bills mature.
- You can split your emergency reserves: Some money can remain in an accessible account while another portion is allocated to short-term T-bills.
- Early sales carry market-price risk: If you sell a marketable T-bill before maturity, the amount you receive may be different from your purchase price.
- Future yields can change: Reinvesting after maturity does not guarantee the same yield as the original T-bill.
- Tax treatment is different from bank interest: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
BOTTOM LINE: T-bills can be one component of an emergency-fund plan. The key is to match the amount and maturity of the T-bills with how quickly you may need the money, while keeping sufficient cash accessible for immediate surprises.
Table of Contents
Treasury Bills for Emergency Funds at a Glance
Treasury bills can be useful for part of an emergency-fund plan, but they should be viewed differently from cash in a checking or savings account. The main issue is timing: a T-bill has a defined maturity, while an unexpected expense may arrive at any time.
| Feature | What It Means for an Emergency Fund |
|---|---|
| Maturity | T-bills have short-term maturities, so the maturity date should fit when you expect the money could be needed. |
| Access | Access is different from withdrawing cash from an ordinary bank account, particularly if the T-bill has not yet matured. |
| FDIC insurance | T-bills are not FDIC-insured deposits. They are marketable securities issued by the U.S. Department of the Treasury. |
| Before maturity | A marketable T-bill can generally be sold before maturity through a broker, but its market price can change. |
| Tax treatment | T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. |
| Potential role | T-bills may fit a portion of emergency reserves that does not need to remain immediately accessible. |
QUICK TAKE: An emergency fund is about more than earning a return. If you use T-bills, match their maturity and access requirements with your expected cash needs. Money needed for an immediate emergency can remain in an easily accessible account, while a separate portion may be considered for short-term T-bills.
Complete Beginner Guide to Using Treasury Bills for an Emergency Fund
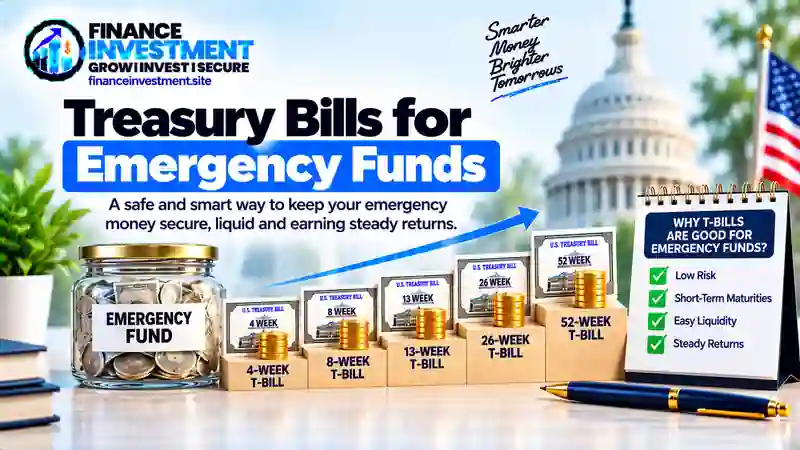 A simple way to think about Treasury Bills for Emergency Funds is to divide your reserves according to when you might need the money. Cash needed for an expense tomorrow should be handled differently from money that may remain untouched for several months.
1. Build an Accessible Cash Reserve First
Start with money that can be accessed easily through a checking or savings account. This portion can help cover an urgent car repair, insurance deductible, unexpected household expense, or temporary gap in income without requiring you to sell an investment.
2. Identify Money You May Not Need Immediately
After setting aside readily accessible cash, look at the remaining emergency reserve. If some of that money is unlikely to be needed immediately, short-term Treasury bills may be one option to consider. The important point is to avoid treating the entire reserve as though it has the same access requirements.
3. Choose a Maturity That Fits Your Timeline
Each T-bill has a stated maturity. Before buying one, consider when the money may be needed and whether you are comfortable waiting until maturity. A shorter maturity can bring the maturity date closer, while a longer one may require a longer planning horizon.
4. Decide What Happens When the Bill Matures
At maturity, you can reassess the money based on your current circumstances. You might keep it available as cash, use it for an upcoming need, or consider another short-term investment. This review point can help keep your emergency reserves aligned with your changing financial situation.
BEGINNER TIP: Build the emergency-fund structure around access rather than chasing the highest available yield. The right setup is one where you know which money is immediately available and which portion follows a T-bill maturity schedule.
How Treasury Bills Work for Emergency Funds
Using Treasury bills for an emergency fund involves more than buying a government security. You need to plan around the purchase amount, maturity date, account you use, and what you would do if an unexpected expense occurs before the bill matures.
1. Decide How Much to Put Into T-Bills
First, identify the portion of your emergency reserve that can follow a maturity schedule. Money needed for an immediate expense may be better kept in an easily accessible account. The T-bill portion should be money you are comfortable keeping invested for its selected term.
2. Select the Maturity
Treasury bills are short-term Treasury securities with maturities of one year or less. Different bill terms are offered through Treasury auctions. When choosing a term, consider how long you can leave that portion of your emergency reserve invested without needing it.
3. Choose Where to Buy
Individuals can buy Treasury bills through TreasuryDirect or through a brokerage that offers Treasury securities. The two routes differ in how securities are purchased, held, transferred, and sold, so the account you choose matters when planning for emergency access.
For the purchase process, see our How to Buy Treasury Bills guide. You can also compare the two account options in TreasuryDirect vs. Brokerage T-Bills.
4. Hold Until Maturity or Plan for an Early Sale
Holding the T-bill until maturity follows the scheduled maturity process. If you need the money earlier, a marketable T-bill may be sold before maturity, but the process depends on where the security is held. With TreasuryDirect, a marketable security generally needs to be transferred to the commercial book-entry system for sale, and the amount received can be affected by market conditions.
5. Review the Money at Maturity
When the T-bill matures, reassess your emergency-fund needs. You may keep the proceeds accessible, use them for an upcoming expense, or consider another short-term investment. If you choose to reinvest, remember that the yield available on a new T-bill may be different from the original one.
PRACTICAL POINT: For emergency savings, the purchase decision and the access plan should be considered together. A T-bill can provide a scheduled source of funds, but it should not be treated as identical to cash that is immediately available in a bank account.
Benefits and Drawbacks of Using Treasury Bills for Emergency Funds
Treasury bills can serve a purpose within a broader emergency-fund plan, particularly for reserves that do not need to remain immediately accessible. However, their advantages come with trade-offs that are important to understand before using them for unexpected expenses.
Potential Benefits
- U.S. government obligation: T-bills are securities issued by the U.S. Treasury and backed by the federal government’s obligation to pay according to their terms.
- Short-term maturities: Their relatively short terms can suit money that has a defined short-term purpose.
- State and local tax treatment: Interest from Treasury securities is generally exempt from state and local income taxes.
- Known maturity date: The maturity date is established when the bill is issued, which can make future cash planning easier.
Potential Drawbacks
- Not immediate cash: A T-bill follows a security and maturity process rather than functioning like a bank-account balance.
- Early-sale risk: If you sell before maturity, the market price may be different from the price you paid.
- Changing future yields: If you reinvest after maturity, the new T-bill may have a different yield.
- More administration: You need to keep track of maturities, account access, and how the proceeds will be handled.
KEY POINT: T-bills can add a short-term government-security layer to an emergency-fund plan, but they do not eliminate the need for accessible cash. The important question is whether the maturity and access arrangements fit the type of emergency you are preparing for.
Treasury Bills vs. Other Emergency-Fund Options
Different emergency-fund options solve different cash-management needs. The key differences are how quickly you can access the money, whether there is a maturity date, whether the product is a bank deposit, and what happens if you need the funds earlier than planned.
| Option | Access | Maturity / Withdrawal | FDIC Insurance | Potential Role |
|---|---|---|---|---|
| Treasury Bills | Depends on maturity or an early-sale process | Fixed maturity; marketable bills may generally be sold before maturity | No | A portion of reserves that can follow a Treasury maturity schedule |
| High-Yield Savings Account | Generally convenient access | No fixed maturity | Generally yes, if it is a deposit at an FDIC-insured bank and within applicable limits | Readily accessible emergency cash |
| Money Market Deposit Account | Generally convenient access | No fixed maturity | Generally yes, if it is an FDIC-insured bank deposit and within applicable limits | Accessible cash with bank-account features |
| Certificate of Deposit (CD) | Usually less flexible before maturity | Fixed term; early withdrawal may involve a penalty | Generally yes, if it is an FDIC-insured bank CD and within applicable limits | Money that can remain committed for a defined period |
QUICK COMPARISON: Bank savings and money market deposit accounts generally provide simpler access to emergency cash. T-bills and CDs add a defined investment term, so they require more planning when the money may be needed unexpectedly. FDIC insurance applies to eligible bank deposits, not Treasury bills.
Costs, Risks and Expert Tips for Using T-Bills in an Emergency Fund
Treasury bills generally have a straightforward cost structure when purchased directly through TreasuryDirect. The bigger issue for an emergency fund is often the trade-off between earning a return and keeping money readily available. Your purchase method and the timing of a potential withdrawal both matter.
Potential Costs and Trade-Offs
- TreasuryDirect purchase cost: The U.S. Treasury states that it does not charge a purchase fee or commission when you buy Treasury securities through TreasuryDirect.
- Brokerage pricing: If you use a brokerage, review that firm’s current pricing and trading terms because costs and transaction policies can vary.
- Liquidity trade-off: Money invested in a T-bill follows a maturity schedule, so it may not be as convenient for an emergency as cash held in an accessible bank account.
Key Risks
- Timing risk: An emergency may occur before your T-bill reaches maturity.
- Market-price risk: If you sell a marketable T-bill before maturity, the price you receive can differ from the amount you originally paid.
- Reinvestment risk: When a T-bill matures, a new bill may have a different yield.
- Access considerations: The steps for accessing funds before maturity depend partly on where the T-bill is held and how it is sold or transferred.
EXPERT TIP: For emergency savings, think about liquidity before yield. Keep an accessible cash layer for expenses that cannot wait, and consider T-bills only for the portion of your reserve that fits comfortably within a maturity schedule.
Common Mistakes and an Illustrative Real-Life Example
Treasury bills can be useful for part of an emergency-fund plan, but mistakes often happen when investors focus on the investment itself and overlook how quickly the money may be needed.
Common Mistakes to Avoid
- Putting the entire emergency fund into T-bills: This can create an access problem if an urgent expense occurs before a bill matures.
- Choosing a maturity without considering cash needs: The maturity date should fit how long you can reasonably leave that portion of your reserve invested.
- Assuming early access works like a bank withdrawal: Selling or transferring a marketable T-bill before maturity involves a different process.
- Assuming future yields will remain unchanged: A new T-bill may have a different yield when the original bill matures.
- Overlooking tax treatment: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
- Never reviewing the emergency-fund structure: Changes in income, expenses, family circumstances, or other liquid assets can affect how much accessible cash you need.
Illustrative Example: A $24,000 Emergency Reserve
Consider a hypothetical household with a $24,000 emergency reserve. The household decides to keep $8,000 in an accessible savings account and considers using the remaining $16,000 for short-term Treasury bills. The purpose is to separate money needed for immediate expenses from money that can follow a maturity schedule.
Suppose an unexpected $3,000 expense occurs. The household could use part of its accessible cash instead of immediately trying to sell a T-bill. Later, when a T-bill matures, the household can reassess its cash needs and decide whether to keep the proceeds available or consider another short-term option.
IMPORTANT: The $8,000 and $16,000 amounts are only illustrative. They are not a recommended emergency-fund allocation. The appropriate structure depends on factors such as monthly expenses, income stability, household obligations, other liquid assets, and how quickly the money may be needed.
Who Should Consider Using Treasury Bills for an Emergency Fund?
Treasury bills may be considered by people who want to keep part of their short-term reserves in U.S. government securities while maintaining separate funds that are readily accessible. Whether this approach fits depends on how quickly the money may be needed and how comfortable you are with a security that has a defined maturity.
This Approach May Fit People Who:
- Already keep some emergency money in an easily accessible account.
- Can identify a portion of their reserves that is unlikely to be needed immediately.
- Are comfortable tracking T-bill maturity dates and managing Treasury securities.
- Understand that selling a marketable T-bill before maturity can involve changes in its market price.
- Want to consider Treasury interest and its federal, state, and local tax treatment when comparing short-term options.
It May Be Less Suitable When:
You have very little readily accessible cash, expect frequent or unpredictable withdrawals, or do not want to manage maturity dates and potential early-sale considerations. In those circumstances, an emergency-fund structure with greater immediate access may better match your cash-flow needs.
KEY QUESTION: Before using a T-bill for emergency savings, ask: “If I needed this money unexpectedly, would the maturity timing and access process work for me?”
Frequently Asked Questions About Treasury Bills for Emergency Funds
1. Can Treasury bills be used for an emergency fund?
Yes. Treasury bills can be used for a portion of an emergency fund, particularly money that does not need to remain immediately accessible. Keeping some cash readily available can help cover expenses that cannot wait for a T-bill to mature.
2. Are T-bills good for emergency savings?
They can be useful for part of an emergency reserve, but they are not the same as immediately accessible cash. The appropriate choice depends on when you may need the money and whether the T-bill’s maturity and access arrangements fit your circumstances.
3. How much of an emergency fund should be in T-bills?
There is no universal percentage. The amount depends on your expenses, income, other liquid assets, and how quickly you might need the money. A useful framework is to separate immediately accessible cash from reserves that can follow a T-bill maturity schedule.
4. Can you access T-bill money before maturity?
Marketable T-bills can generally be sold before maturity, but the process depends on where the security is held. A TreasuryDirect-held marketable security may need to be transferred or sold through the applicable TreasuryDirect process, and an early sale can produce a price different from the amount originally paid.
5. Are Treasury bills FDIC insured?
No. Treasury bills are securities issued by the U.S. Treasury, not FDIC-insured bank deposits. FDIC insurance applies to eligible deposits held at FDIC-insured banks, subject to applicable coverage limits.
6. Do T-bills have state and local tax benefits?
Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.
7. What T-bill maturity is best for an emergency fund?
There is no single maturity that is best for everyone. The appropriate term depends on how long you can leave the money invested, how much accessible cash you already have, and how soon you may need the reserve.
8. Should you keep some emergency money in a savings account?
Keeping some emergency money in an accessible savings account can make sense when immediate access is important. The appropriate amount depends on your expected expenses, cash-flow needs, and overall financial situation.
FAQ NOTE: These answers explain the general framework. Your emergency-fund structure should reflect your own cash needs, access requirements, and financial circumstances.
Final Verdict: Where Treasury Bills Can Fit in an Emergency Fund
Treasury Bills for Emergency Funds can be considered for a portion of short-term reserves when that money does not need to remain immediately accessible. Their defined maturities can help with planned cash management, while their status as U.S. Treasury securities gives them a different role from ordinary bank deposits.
The main consideration is liquidity. An unexpected expense can arise before a T-bill reaches maturity. If you need to access the money earlier, the process depends on where the security is held, and selling before maturity can expose you to changes in market price. This is why emergency-fund planning should account for readily accessible cash as well as investments with defined terms.
THE BIG IDEA: Think of an emergency fund as a liquidity structure rather than a single investment. Accessible cash can cover immediate needs, while T-bills may be considered for reserves that can comfortably follow a maturity schedule.
There is no universal T-bill allocation or maturity for every household. The appropriate structure depends on expenses, income, other liquid assets, expected cash needs, and your comfort with managing Treasury securities.

 Building the right savings balance is simpler than many people think. Instead of choosing a random dollar amount, start by looking at your monthly essential expenses. These include housing, groceries, utilities, transportation, insurance, healthcare, and other bills you must pay even during a financial emergency.