Tag: Credit Union Guide

  • How Do Credit Unions Work? Complete Beginner Guide 2026

    How Do Credit Unions Work? Complete Beginner Guide 2026

    How Do Credit Unions Work? Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    How Do Credit Unions Work?

    How Do Credit Unions WorkIf you’ve ever wondered how do credit unions work, the simplest answer is this: members save, borrow and use financial services through a cooperative institution they collectively own. Credit unions can accept member savings, make loans and provide services much like banks, but their ownership structure is different. The NCUA describes credit unions as member-owned, member-controlled cooperatives.

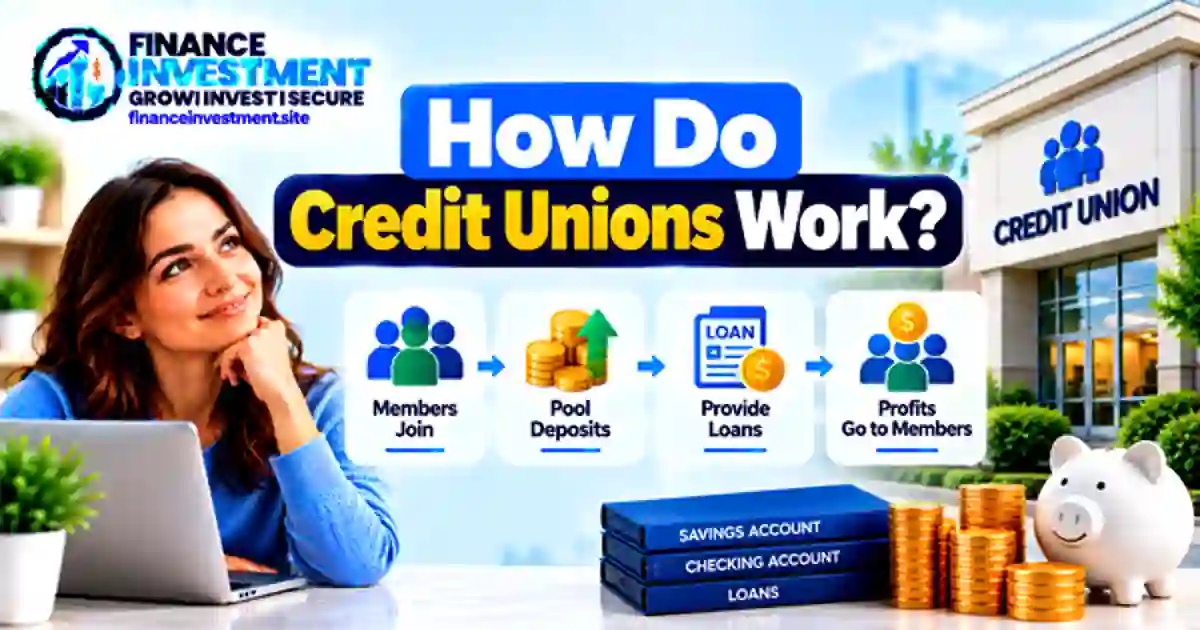
    The money flow is at the heart of the model. Members put money into savings and other share accounts. The credit union uses its available funds to support lending and day-to-day operations. When members borrow, their loan payments bring money back into the institution. Revenue from loans, fees and other activities helps cover operating costs and maintain the credit union’s financial strength.

    Membership is another important piece. A credit union usually has a defined field of membership, which can be based on factors such as employment, location, family or association membership. So before opening an account, you need to determine whether you qualify.

    THE SIMPLE IDEA

    A credit union creates a cooperative financial cycle: members save → the credit union lends → borrowers repay → the institution serves its members and covers its costs.

    For the bigger picture, see our complete Credit Unions Explained guide, which covers accounts, membership, fees, NCUA insurance and other important details.

    What You’ll Learn

    • How credit union membership and ownership work.
    • How member savings and loans connect inside the cooperative model.
    • How checking, savings and other share accounts fit into the system.
    • How revenue, fees and operating costs affect the credit union.
    • How credit unions differ from traditional banks.
    • What to consider before joining or opening an account.

    Quick Answer: How Do Credit Unions Work?

    How do credit unions work? They operate as member-owned financial cooperatives. People who qualify for membership can place money into share accounts, use checking and savings services, and apply for loans. The credit union earns revenue, pays its operating expenses, manages financial reserves and provides services for its members.

    The biggest difference from a traditional bank is the ownership structure. Eligible members become part of the cooperative and may have voting rights under the credit union’s rules. Credit unions also use different terminology: a savings account may be called a share account, while a checking account may be called a share draft account.

    KEY TAKEAWAYS

    • You generally need to meet the credit union’s membership eligibility rules.
    • Members can use share accounts, checking services, loans and other financial products.
    • Membership gives eligible individuals an ownership interest in the cooperative.
    • Credit unions generate revenue to cover expenses, maintain financial strength and serve members.
    • Accounts at federally insured credit unions can receive NCUA share insurance, subject to applicable coverage limits and rules.

    Credit Unions at a Glance

    FeatureWhat It Means
    OwnershipEligible members have an ownership interest in the cooperative.
    MembershipYou generally must qualify under the credit union’s field-of-membership rules.
    AccountsProducts may include share savings, share draft checking and share certificates.
    LoansCredit unions can provide financing for needs such as vehicles, personal expenses and homes.
    Share InsuranceAccounts at federally insured credit unions may receive NCUA share insurance, subject to coverage limits and applicable rules.

    QUICK TAKE

    A credit union brings membership, saving, borrowing and financial services together under a cooperative structure. The exact products, fees, eligibility rules and insurance arrangements vary, so compare the specific credit union before opening an account.

    How Credit Unions Work: Complete Beginner Guide
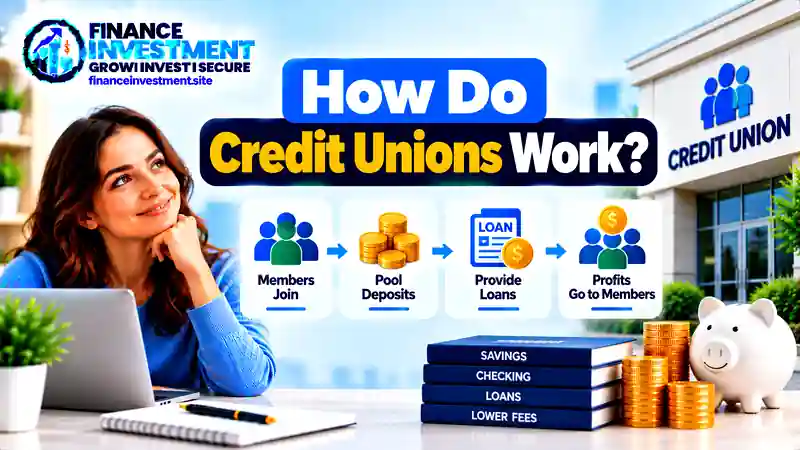
    How Do Credit Unions WorkTo understand how credit unions work, it helps to follow the process from eligibility to everyday financial services. The experience can look familiar if you’ve used a bank before: you may save money, make payments, use a debit card, manage your account online and apply for a loan. The main difference is the cooperative ownership structure.

    1. You Qualify for Membership

    A credit union generally serves a defined field of membership. Depending on its charter, eligibility may be connected to your community, employer, family relationship, association or another qualifying group. Once you qualify, the credit union explains the steps and minimum share requirements for becoming a member.

    2. You Open Accounts and Use Services

    Credit unions can offer many of the same everyday services available at banks. A share savings account can hold savings, while a share draft account can provide checking features. Depending on the institution, members may also have access to share certificates, debit cards, digital banking, credit cards and other products.

    3. The Credit Union Manages Its Resources

    The credit union manages member shares along with other funding sources, investments, liquidity and financial reserves. It can use available resources to make loans to qualified borrowers and provide other services. Interest from loans, fees and other revenue help the institution pay operating expenses and maintain financial strength.

    4. Members Have an Ownership Role

    The members are the owners of the cooperative. Eligible members generally have voting rights under the credit union’s governing rules and elect a board of directors to oversee the institution. This member-owner structure is one of the clearest differences between a credit union and an investor-owned bank.

    BEGINNER TIP

    Before joining, check the credit union’s eligibility rules, minimum share requirement, account fees, digital access, ATM options and applicable insurance coverage. If you’re comparing digital institutions with cooperative options, our guide to digital banks vs. credit unions can help you compare the basic models.

    How Credit Union Money Flow Works

    To understand how money moves through a credit union, think beyond a simple “savings account funds a loan” model. A credit union manages member shares together with its other funding sources, investments, liquidity and capital. Its goal is to provide financial services while meeting withdrawals, loan demand, operating expenses and other obligations.

    Step 1: Members Keep Money in Share Accounts

    Members may keep money in share savings, share draft and other eligible accounts. These balances become part of the credit union’s overall funding base. The institution manages that money rather than treating each member’s balance as a separate pool reserved for a particular purpose.

    Step 2: The Credit Union Provides Financing

    Credit unions evaluate loan applications and may provide financing to qualified borrowers. Depending on the institution, loans can include auto loans, personal loans, mortgages and credit cards. Borrowers then make principal and interest payments according to their agreements.

    Step 3: Revenue Covers Costs and Supports Financial Strength

    Interest from loans and revenue from other activities help the credit union pay employee, technology, facility, insurance and regulatory expenses. The institution also manages capital, liquidity and reserves to remain financially sound and ready to meet member needs.

    Step 4: The Cycle Continues

    Members continue saving, borrowing, making payments and using financial services. Because the institution is member-owned, its financial activities are organized around serving its membership rather than outside stockholders. The exact rates, fees and financial products vary by credit union.

    MONEY-FLOW SNAPSHOT

    Members provide funding → the credit union manages its resources → qualified borrowers receive financing → borrowers make payments → revenue supports operations, liquidity and financial strength. This is a simplified view of a much more detailed balance sheet.

    Credit Union Benefits & Drawbacks

    Credit unions can offer a different banking experience because members own the cooperative and eligible members can participate in its governance. At the same time, a credit union is not automatically the right fit for everyone. Products, rates, fees, technology and access can vary considerably between institutions.

    Potential Benefits

    • Eligible members have an ownership role in the cooperative.
    • Members can access checking, savings, loans and other financial services.
    • Some credit unions may offer competitive rates or fees on particular products.
    • Members may have voting rights under the credit union’s governing rules.

    Potential Drawbacks

    • Eligibility rules can limit who is able to join.
    • Branch and ATM access may vary by location and network.
    • Digital banking tools and product selection can differ between institutions.
    • Rates and fees are not automatically better than those offered by banks.

    WHAT TO CHECK

    Before joining, compare the specific credit union’s APYs, loan rates, account fees, minimum balances, ATM access, digital banking features, membership rules and applicable share insurance. The cooperative structure is only one part of the decision.

    Credit Union vs. Bank Comparison

    Credit unions and banks can both provide checking, savings, payment services and loans. The clearest structural difference is ownership: a credit union is a member-owned cooperative, while a bank may be shareholder-owned or privately owned. That distinction can affect governance and membership rules, but it does not by itself determine the rates, fees or services available to customers.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeMay be shareholder-owned or privately owned
    EligibilityGenerally requires meeting the credit union’s membership rulesMust meet the bank’s account-opening and customer requirements
    GovernanceEligible members may vote under applicable rulesGoverned according to the bank’s ownership and corporate structure
    Deposit/Share InsuranceFederally insured credit unions can have NCUA share insurance, subject to applicable limits and rulesFDIC-insured banks provide FDIC deposit insurance, subject to applicable limits and rules

    COMPARE THE ACTUAL ACCOUNT

    When comparing a credit union with a bank, look beyond the label. Check the APY, interest rate, fees, minimum balance, ATM access, digital tools, branch availability and applicable insurance coverage for the specific account.

    Credit Union Costs, Risks & Expert Tips

    A credit union can offer useful financial services, but joining does not automatically mean lower costs or better terms. Depending on the institution and account, you may encounter monthly maintenance fees, overdraft charges, ATM fees, minimum-balance requirements, loan interest and other service charges. Always review the specific account terms before joining.

    Risks and Limitations to Consider

    Access can vary significantly between credit unions. One institution may have convenient branches and shared-branch access, while another may rely more heavily on digital banking. Product selection, ATM availability and mobile features can also differ. You should also verify the institution’s share-insurance status and understand which accounts are covered and what limits apply.

    Expert Tips Before You Join

    • Read the account agreement and current fee schedule.
    • Check minimum opening deposits and balance requirements.
    • Compare loan APRs, fees and total borrowing costs.
    • Review branch, ATM, shared-branch and digital access.
    • Verify the credit union’s applicable share-insurance coverage before depositing significant funds.

    SMART CHECK

    Don’t judge an account by its headline rate alone. Compare the rate, fees, requirements, access and applicable insurance coverage together before making a decision.

    Common Credit Union Mistakes + Illustrative Example

    Knowing how credit unions work is useful, but the account details matter just as much. Many mistakes happen when people focus on the cooperative label and skip the practical terms that affect their everyday banking.

    Mistakes to Avoid

    • Not checking eligibility: Confirm that you qualify before spending time comparing accounts.
    • Ignoring account requirements: Review monthly fees, minimum balances, opening deposits and transaction rules.
    • Assuming all credit unions are alike: Products, rates, technology, branches and ATM access can differ.
    • Comparing only the advertised rate: Consider fees and other account conditions alongside the rate.

    A Simple Example

    Imagine Maria qualifies for a credit union and needs a checking account. She expects to use ATMs several times a month and deposits her paycheck electronically. Before opening the account, she compares the monthly fee, minimum balance, ATM access, mobile deposit features and overdraft terms with another financial institution. The credit union may meet her needs, but if ATM availability or another account feature is less convenient for her routine, she has a practical factor to weigh before joining.

    THE LESSON

    Don’t choose an account based only on the institution’s label. Compare the specific fees, requirements, access, services and applicable insurance coverage against how you actually plan to use the account.

    Who May Benefit From a Credit Union?

    A credit union may fit your needs when its membership rules, account terms, services and access align with how you manage money. The cooperative structure gives eligible members an ownership role, but that feature is only one part of the decision. Your everyday costs, account features and access should also match your priorities.

    A Credit Union May Fit If You:

    • Meet the institution’s membership eligibility requirements.
    • Want checking, savings, lending or other financial services from the same institution.
    • Value having an ownership and voting role under the cooperative’s governing rules.
    • Can conveniently use the credit union’s branches, ATMs, shared-branch network or digital services.
    • Find its fees, rates, minimum requirements and account features suitable for your needs.

    The same comparison process applies whether you’re managing everyday spending, saving for a goal or looking for borrowing options. If you’re comparing online banking with cooperative banking, see our guide to digital banks vs. credit unions.

    A PRACTICAL RULE

    Eligibility determines whether you can join. After that, compare the account terms, costs, access, services and applicable insurance coverage before opening an account.

    Frequently Asked Questions About How Credit Unions Work

    1. How do credit unions work?

    Credit unions operate as member-owned financial cooperatives. Eligible members can use savings, checking, lending and other financial services. The institution manages its resources, earns revenue and uses that revenue to cover operating expenses and maintain financial strength.

    2. Are credit unions banks?

    No. Credit unions and banks can offer many similar financial products, but their organizational structures differ. Credit unions are member-owned cooperatives, while banks may be shareholder-owned or privately owned.

    3. How does a credit union generate revenue?

    Credit unions can generate revenue from loan interest, fees and other financial activities. That revenue helps pay operating expenses, support financial operations and maintain the institution’s financial condition.

    4. Do credit unions have checking and savings accounts?

    Yes. Many credit unions offer both. They may use different terminology, such as share accounts for savings and share draft accounts for checking.

    5. Are credit union accounts insured?

    Accounts at federally insured credit unions may receive NCUA share insurance, subject to applicable coverage limits and rules. Check the institution’s insurance status and account coverage before depositing money.

    6. Can anyone join a credit union?

    Not necessarily. Credit unions generally have a defined field of membership. Eligibility can depend on factors such as location, employment, family relationships or membership in a qualifying organization.

    7. Can credit unions offer loans?

    Yes. Depending on the institution, credit unions may offer auto loans, personal loans, mortgages, credit cards and other financing. Approval, rates and terms depend on the specific product and borrower.

    8. What should I check before joining a credit union?

    Check eligibility, fees, minimum balances, APYs, loan rates, ATM and branch access, digital banking features, account terms and applicable share insurance. Compare those details with your actual banking needs.


    Final Verdict: How Do Credit Unions Work?

    So, how do credit unions work? The model is built around eligible members who use and collectively own a cooperative financial institution. The credit union manages member shares and other resources, provides financial services, makes loans to qualified borrowers and uses revenue to cover operating expenses and maintain financial strength.

    For someone considering membership, the ownership structure is only the starting point. The practical details can differ by institution, including membership eligibility, account fees, rates, minimum balances, ATM access, digital banking features, loan terms and applicable share insurance.

    BOTTOM LINE

    A credit union combines cooperative ownership with everyday financial services. Before joining, review the specific institution’s terms and compare them with the way you actually plan to save, spend or borrow.

    Related Resources & Authority Sources

    If you want to continue researching credit unions, start with our complete Credit Unions Explained guide. You can also compare different banking models with our guide to digital banks vs. credit unions.

    Official Authority Sources

    RESEARCH TIP

    Before opening an account, use the institution’s current disclosures and official regulator information to verify membership eligibility, fees, rates, account terms and applicable insurance coverage.

    Have a Money Question? Keep Exploring.

    Credit unions are just one part of the banking landscape. As you compare your options, keep looking at the details that affect your everyday money decisions, including fees, account features, access, rates and applicable protections.

    📩 Get in Touch With FinanceInvestment

    Have a personal-finance question or a topic you’d like FinanceInvestment to explain?
    Email FinanceInvestment

  • What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    What Is a Credit Union?

    What Is a Credit UnionIf you’ve ever wondered what is a credit union and how it differs from a bank, the basic idea is straightforward. A credit union is a member-owned, not-for-profit financial cooperative that provides services such as savings, checking, certificates and loans to people who qualify for membership. NCUA explains the credit union structure here.

    The difference becomes clearer when you look beyond the account itself. When you join a credit union, you become a member of the cooperative. That relationship can give you access to everyday banking, savings products and borrowing options offered by the institution.

    There is one important checkpoint before choosing an account: eligibility. Credit unions generally operate within a defined field of membership. Depending on the institution, qualification may be connected to your employer, association, geographic community or another permitted relationship. NCUA’s field-of-membership guide explains how these eligibility rules work.

    THE BIG IDEA

    A credit union can look much like a bank when you use it day to day. The meaningful differences are usually found in ownership, membership, account terms, fees, access and insurance. Understanding those details makes the comparison much easier.

    If you want the wider picture after this beginner guide, continue to our complete Credit Unions Explained guide, which brings together accounts, fees, NCUA insurance, membership and other important questions.

    What You’ll Learn

    • What a credit union is and what makes its ownership structure different.
    • Why membership eligibility matters before you open an account.
    • How common credit union accounts work.
    • How credit unions compare with banks.
    • What to check when reviewing fees, access and insurance.
    • The potential benefits and drawbacks of joining a credit union.

    Quick Answer: What Is a Credit Union?

    THE SHORT ANSWER

    A credit union is a member-owned, not-for-profit financial cooperative. People who meet its membership requirements can join and use services such as checking, savings, certificates and loans. The cooperative structure is one of the main differences between a credit union and a traditional bank.

    Key Takeaways

    • Eligibility matters: You need to qualify under the credit union’s membership rules.
    • Members own the cooperative: The institution is organized around its members rather than outside stockholders.
    • Everyday services are available: Many credit unions offer checking, savings, certificates and loans.
    • Account terms vary: Fees, rates, minimum balances and access can differ from one credit union to another.
    • Federal insurance may apply: Qualifying shares at federally insured credit unions can receive NCUSIF coverage, subject to applicable limits and ownership rules.
    • The institution still matters: Compare the actual account and services instead of relying only on the credit union label.

    BOTTOM LINE

    Think of a credit union as a financial cooperative with membership rules. Before joining, compare eligibility, costs, account features, access and applicable insurance.

    Credit Union at a Glance

    Before we get into the details, here is the quick picture. A credit union can provide many familiar financial services, but membership rules, account terms and insurance status are worth checking before you open an account.

    Quick Facts

    FactorWhat to Know
    OwnershipA credit union is a member-owned cooperative.
    MembershipYou generally need to meet the institution’s eligibility requirements.
    Common ServicesChecking, savings, certificates, payment services and loans may be available.
    AccessBranches, ATMs, shared branching and digital banking depend on the institution.
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable rules.

    Key Numbers

    For federally insured credit unions, the standard maximum share-insurance amount is generally $250,000 per share owner, per federally insured credit union, for each ownership category. The actual coverage calculation can depend on ownership structure and other applicable rules.

    There is no single nationwide fee, minimum balance or savings rate for all credit unions. Those figures belong to individual institutions and accounts, so current terms should always be checked before opening an account.

    Who May Find a Credit Union Relevant?

    Credit unions can be relevant to people who qualify for membership and want access to everyday banking, savings or borrowing through a cooperative institution. Families, retirees, students and other consumers may all encounter credit unions, but the useful comparison depends on the products and services they actually need.

    QUICK TAKE

    The first checkpoint is eligibility. Once you qualify, compare the actual account’s fees, rates, minimum balance, access, services and applicable insurance rather than judging the institution by its name alone.

    What Is a Credit Union? A Beginner Guide

    What Is a Credit UnionA credit union is a member-owned, not-for-profit financial cooperative that provides financial services to people who qualify for membership. Like a bank, it may offer checking, savings, certificates, loans and other financial products. The important difference is the ownership structure behind those services. Members join the cooperative and have a membership relationship with the institution. NCUA explains the credit union structure and how it differs from other financial institutions.

    What Does “Member-Owned” Mean?

    When you qualify and join a credit union, you become a member of the cooperative. That is different from simply being a customer of a financial institution. In a federal credit union, members generally have voting rights in the governance of the cooperative, including the ability to participate in the election of the board of directors, subject to the credit union’s governing rules.

    The phrase not-for-profit can also be misunderstood. It does not mean a credit union operates without revenue or earnings. It still has employees, technology, branches, compliance costs and other expenses. Revenue helps cover those costs and supports the institution’s financial strength. NCUA’s guidance on credit-union earnings explains why earnings remain important to a cooperative financial institution.

    Why Do Credit Unions Have Membership Rules?

    A credit union generally serves a defined field of membership. In simple terms, that means there are rules describing who is eligible to join. Depending on the institution, eligibility may be connected to an employer, association, geographic community, family relationship or another qualifying connection. NCUA’s field-of-membership information provides more detail.

    This is why membership should be checked before comparing an account’s rate or fee. If you qualify, the same membership may give you access to several products offered by that credit union.

    Credit Union Terms You May See

    Credit Union TermOften Compared WithTypical Purpose
    Share AccountSavings accountHolding savings and, depending on the credit union, establishing the membership relationship.
    Share Draft AccountChecking accountEveryday spending, payments and other transactions.
    Share CertificateCertificate of deposit (CD)Holding money for a stated term under the certificate’s conditions.

    BEGINNER TIP

    The word “share” can make credit union accounts sound unfamiliar. In practice, many of these products serve purposes similar to accounts you may already know. Focus on the account’s actual fees, rates, access rules and other terms before opening it.

    How Do Credit Unions Work?

    A simple way to understand a credit union is to look at how members save, borrow and use financial services. Members place money into share accounts and other available products. The credit union manages those funds and other resources while making loans to eligible members and providing additional services. Interest from loans and other revenue help pay operating costs and support the institution’s financial strength.

    This creates a cooperative financial cycle. Member savings can help provide part of the funding used for lending, although individual deposits are not directly matched to individual loans. The credit union manages the overall pool of funds, assets and liabilities. NCUA’s explanation of credit union operations describes how federally chartered credit unions allow members to save, borrow and participate in the cooperative.

    Who Runs a Credit Union?

    For a federal credit union, members elect a board of directors from the membership. The board oversees the institution, while management and employees handle day-to-day operations. This gives members a formal role in the governance of the cooperative. NCUA’s operations guidance explains the role of the elected board and member ownership.

    What Happens to Credit Union Earnings?

    Not-for-profit does not mean a credit union can operate without earnings. NCUA explains that credit unions need revenue to cover the cost of serving members and maintain an appropriate level of net worth. Depending on the institution’s financial position, earnings may be retained to strengthen the credit union or may support member value through products, rates, fees or dividends. NCUA’s earnings guidance explains this balance.

    StepWhat Happens
    1. JoinAn eligible person becomes a member under the credit union’s membership rules.
    2. SaveMembers can place funds into available share accounts and other products.
    3. BorrowEligible members can apply for loans under the credit union’s lending requirements.
    4. ManageThe institution manages its funds, expenses, risks, capital and member services.

    HOW IT CONNECTS

    The cooperative model connects membership, saving, lending and shared financial services. The exact rates, fees, products and member benefits depend on the individual credit union and its financial condition.

    Credit Union Benefits & Drawbacks

    A credit union can fit well into one person’s banking setup and be less convenient for another. The important part is to compare the specific institution, because account features, fees, rates and access can vary.

    Potential Benefits

    • Member ownership: Joining creates an ownership relationship within the cooperative.
    • Several banking services: Many credit unions offer checking, savings, certificates and loans through the same membership.
    • Competitive terms may be available: Some institutions offer attractive rates or fees on particular products, although there is no guarantee across all credit unions.
    • Multiple access options: Depending on the institution, members may have access to branches, shared branches, ATMs and digital banking.
    • Federal share insurance: Qualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable limits and ownership rules.

    Potential Drawbacks

    • Membership eligibility: You generally need to meet the credit union’s field-of-membership requirements.
    • Branch availability can vary: Some credit unions have fewer physical locations than larger banking networks.
    • Digital features differ: Mobile apps, online banking tools and remote services are not identical across institutions.
    • Product selection varies: A particular credit union may not offer every financial service you want.
    • Rates and fees are not automatically better: The credit-union structure alone does not guarantee a lower fee or higher savings rate.

    EXPERT TIP

    Don’t compare a credit union with a bank using the name alone. Put the actual accounts side by side and check eligibility, APY or dividend terms, fees, minimum balances, ATM access, digital features and applicable insurance.

    Credit Union vs. Bank: What’s the Difference?

    Credit unions and banks can both provide checking, savings, payment services and loans. The differences become clearer when you look at how each institution is organized, who can use it and which insurance system applies to eligible accounts.

    FactorCredit UnionBank
    OwnershipMember-owned cooperativeBanks have their own ownership and corporate structures.
    EligibilityYou generally need to meet membership requirements.Banks generally do not use a credit-union field-of-membership system.
    InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage.Qualifying deposits at FDIC-insured banks may receive FDIC coverage.
    Accounts & ServicesProducts and features vary by credit union.Products and features vary by bank.
    AccessBranches, ATMs, shared networks and digital tools depend on the institution.Branch, ATM and digital access also depend on the institution.

    What Should You Compare?

    For everyday banking, compare the actual account rather than the institution label. Look at monthly fees, minimum balances, savings APY, checking features, ATM access, branch locations and digital banking. If borrowing is important, compare loan APRs, fees, repayment periods and total costs using similar loan amounts and terms.

    Insurance is another important checkpoint. NCUA explains federal share insurance for qualifying shares at federally insured credit unions, while the FDIC explains deposit insurance for qualifying deposits at insured banks.

    COMPARISON TIP

    A useful comparison starts with your actual needs. Put the specific credit union account and bank account side by side and compare their current terms, access and applicable insurance.

    Credit Union Costs, Risks & Expert Tips

    A credit union is not automatically fee-free. Costs depend on the specific account, services you use and the institution’s current terms. Before joining, review the fee schedule and account disclosures instead of focusing only on the advertised rate.

    Costs Worth Checking

    CostWhat to Check
    Monthly FeeWhether a recurring fee applies and whether the credit union offers a waiver.
    Minimum BalanceAny required opening or ongoing balance and the consequences of falling below it.
    ATM ChargesWhich ATMs are available and whether out-of-network fees may apply.
    Other Service FeesReview overdraft, insufficient-funds, wire, transfer and other applicable charges.

    Risks and Important Checks

    The main risk is assuming that all credit unions offer the same rates, fees, technology or access. They do not. A credit union with attractive savings terms may have different ATM coverage or digital features, while another may offer a broader service network. Compare the details that matter to you.

    You should also confirm the institution’s insurance status. At a federally insured credit union, qualifying shares are generally insured through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. Do not treat every financial product offered by a credit union as an insured share account.

    IMPORTANT CHECK

    Federal share insurance generally applies to qualifying share accounts, not investments such as stocks, bonds or mutual funds. Always confirm what you are purchasing and what protection applies before moving money.

    EXPERT TIP

    Before opening an account, save the fee schedule, rate information, account disclosures and insurance details. These documents give you a clear reference point when reviewing the account later.

    Common Credit Union Mistakes to Avoid

    Opening an account without checking the details can lead to avoidable fees or access problems. A few simple checks can make the process easier and help you understand what you are actually getting.

    Mistakes Beginners Often Make

    1. Skipping the eligibility check: Confirm that you qualify for membership and understand any required opening deposit or membership conditions.
    2. Ignoring the fee schedule: Review monthly, ATM, overdraft, transfer and other applicable service fees.
    3. Assuming every credit union works the same way: Branch locations, ATM access, digital tools and account features can vary significantly.
    4. Focusing only on the advertised rate: Check the APY or dividend rate along with minimum balances, fees and other account conditions.
    5. Overlooking insurance status: Confirm whether the institution is federally insured and understand which qualifying shares may receive NCUSIF coverage.

    Illustrative Example: Comparing a Credit Union Account

    Suppose Sarah is looking for a new checking account. She finds a credit union with a low monthly fee and is interested in joining. Instead of opening the account immediately, she first confirms that she qualifies for membership, checks the minimum balance requirement and reviews the fee schedule.

    Next, Sarah checks the credit union’s ATM network and digital banking features. She also verifies its federal insurance status and compares the account with a bank checking account that she could use instead. The comparison shows her the practical differences in fees, access and features.

    This example shows why the account details matter more than the label. A credit union may fit her needs, but she can make that decision only after reviewing the actual terms.

    LESSON FROM THE EXAMPLE

    Before moving your money, check eligibility, fees, rates, access, account conditions and applicable insurance. A few minutes of comparison can reveal details that an advertised offer may not show.

    Who Should Choose a Credit Union?

    A credit union may be worth considering if you qualify for membership and its accounts, services and costs match the way you manage your money. The right fit depends on your individual needs, so compare the actual terms rather than choosing based only on the institution’s name.

    A Credit Union May Fit If You:

    • Qualify for membership: You meet the credit union’s eligibility requirements.
    • Want several services: You can access the checking, savings, borrowing or other products you need through the institution.
    • Value cooperative membership: You prefer an institution organized around a member-owned structure.
    • Find suitable account terms: The fees, rates, minimum balances and features fit your financial needs.
    • Have convenient access: The available branches, ATMs, shared networks and digital tools work for your routine.

    When Should You Compare Other Options?

    Another financial institution may be worth comparing if you cannot qualify for membership or if the credit union’s fees, account features, ATM access, digital tools or product selection do not meet your needs. Comparing similar accounts can help you see the practical differences before opening an account.

    QUICK CHECK

    Before joining, ask three questions: Can I qualify? Does the account meet my needs? Do the costs, access and protections make sense for me?

    Frequently Asked Questions About Credit Unions

    Here are answers to common beginner questions about credit unions, membership, accounts, fees and federal share insurance.

    1. What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative. Eligible members can use services such as checking, savings, certificates and loans. The specific products and terms depend on the institution.

    2. Are Credit Unions Banks?

    No. Credit unions and banks are different types of financial institutions, although they can offer many similar financial products. Credit unions are member-owned cooperatives and generally have membership eligibility requirements.

    3. Can Anyone Join a Credit Union?

    Not necessarily. You generally need to meet the credit union’s field-of-membership requirements. Eligibility can depend on factors such as where you live, where you work, an association or another qualifying relationship.

    4. Are Credit Unions Safe?

    Federally insured credit unions provide federal share insurance for qualifying shares through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. You should verify the credit union’s insurance status before depositing money.

    5. What Accounts Do Credit Unions Offer?

    Many credit unions offer share savings accounts, share draft accounts that work much like checking accounts, share certificates, money market products and loans. The exact product lineup varies by institution.

    6. Do Credit Unions Have Lower Fees Than Banks?

    Not necessarily. Fees vary by institution and account. Compare monthly maintenance fees, minimum balance requirements, ATM charges, overdraft policies and other service costs before opening an account.

    7. What Is NCUSIF Insurance?

    NCUSIF stands for the National Credit Union Share Insurance Fund. It provides federal share insurance for qualifying shares at federally insured credit unions, subject to applicable coverage limits and ownership categories. It does not insure investments such as stocks, bonds or mutual funds.

    8. How Should I Choose Between a Credit Union and a Bank?

    Start with your actual needs. Compare membership eligibility, account fees, rates, minimum balances, ATM and branch access, digital banking, product selection and applicable insurance. Looking at specific accounts side by side can give you a clearer picture than relying on the institution type alone.

    FAQ TAKEAWAY

    The key is to understand membership, account terms, fees, access and applicable insurance before opening a credit union account.


    Final Verdict: What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative that can offer checking, savings, certificates, loans and other financial services. Its membership structure and eligibility rules are what set it apart from a typical bank.

    If you are considering one, start with the basics: Can you qualify, and does the account fit your needs? Then review the actual fees, rates, minimum balances, ATM access, digital tools and available services. These details can vary significantly from one institution to another.

    For federally insured credit unions, also verify the applicable NCUSIF coverage for qualifying shares and understand the relevant ownership limits. This gives you a clearer picture of both the account and the protection attached to it.

    THE BOTTOM LINE

    A credit union is one financial option among several. The useful comparison comes down to eligibility, account terms, costs, access, services and applicable insurance.

    Related Resources & Authority Sources

    If you want to continue learning, our complete Credit Unions Explained guide covers accounts, membership, fees and NCUA insurance in greater detail. You can also explore digital banks vs. credit unions to understand how digital banking models compare with credit-union services.

    Trusted Authority Sources

    • NCUA Share Insurance Coverage — explains federal share insurance, coverage limits, ownership categories and products that are not covered.
    • NCUA Field of Membership — provides information about credit union membership eligibility and field-of-membership rules.
    • FDIC Deposit Insurance — provides information about federal deposit insurance for qualifying deposits at FDIC-insured banks.

    RESEARCH TIP

    Use regulator information to understand insurance and membership rules, then review the credit union’s current account disclosures for its specific rates, fees, minimums and conditions.

    Have a Money Question? Keep Exploring.

    Your banking needs can change over time. Keep learning about accounts, fees, insurance and other money topics so you can evaluate your options with greater confidence.

    📩 Get in Touch With FinanceInvestment

    Have a finance question, topic suggestion or feedback? Send us a message.

    Email FinanceInvestment

    Continue Your Research