Treasury Bills vs CDs: Tax Differences
Treasury Bills vs CDs: Tax Differences
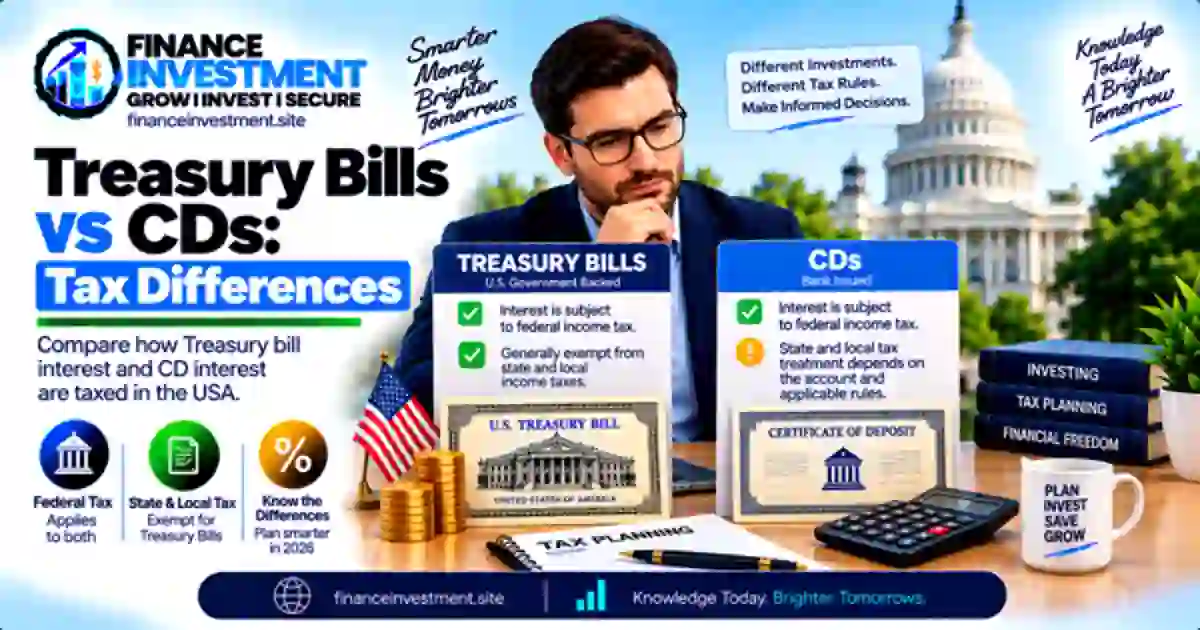 At first glance, Treasury bills and certificates of deposit can seem similar. Both can hold your money for a defined period and generate income. But Treasury Bills vs CDs: Tax Differences can change the amount you keep after taxes. A rate that looks attractive before taxes may not produce the same after-tax result.
Treasury bill interest is generally subject to federal income tax, but interest from U.S. Treasury obligations is generally exempt from state and local income taxes. CD interest is generally taxable as interest income, while state and local taxes may also apply depending on where you live and the applicable rules.
This guide explains the difference in plain English. You’ll see how each investment creates taxable income, how that income is generally reported, and why your location can matter when comparing the two. For a broader introduction to Treasury bills, see our complete Treasury Bills guide.
What You’ll Learn
- How Treasury bill interest is generally taxed federally.
- How CD interest is generally treated for federal tax purposes.
- Why state and local taxes can create a difference between the two.
- How T-bill and CD interest is generally reported.
- Why after-tax income can be more useful than comparing stated yields alone.
- Common tax-reporting mistakes to watch for.
Quick Answer: How Do Treasury Bills and CDs Differ on Taxes?
The short answer: Both Treasury bill interest and CD interest are generally subject to federal income tax. The major difference is that interest from U.S. Treasury obligations is generally exempt from state and local income taxes, while CD interest may also be subject to applicable state and local income taxes.
Key Takeaways
- T-bills: Interest is generally subject to federal income tax.
- CDs: Interest is generally taxable for federal income tax purposes.
- State and local taxes: Interest from U.S. Treasury obligations is generally exempt from these taxes.
- CD taxation: State and local treatment depends on the applicable rules where you live.
- T-bill reporting: Treasury interest is generally reported on Form 1099-INT, with Treasury obligations generally shown in Box 3.
- CD reporting: Banks generally report taxable CD interest on Form 1099-INT when the applicable reporting requirements are met.
- After-tax income: The amount you keep can differ even when two investments have similar pre-tax yields.
BOTTOM LINE: Treasury bills are generally not free from federal income tax. Their main tax distinction is the general exemption of Treasury interest from state and local income taxes.
Table of Contents
Treasury Bills vs CDs: At a Glance
The main tax difference becomes easier to see when federal, state, and local taxes are separated. Both Treasury bills and CDs generally create income that is taxable at the federal level. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes, while CD interest may be subject to those taxes under applicable rules.
Quick Facts
| Tax Detail | Treasury Bills | CDs |
|---|---|---|
| Federal income tax | Generally applies | Generally applies |
| State & local income tax | Generally exempt | May apply under applicable rules |
| Federal tax reporting | Generally Form 1099-INT, Box 3 | Generally Form 1099-INT when reportable |
| Income structure | Usually issued at a discount and paid at face value at maturity | Usually earns stated interest according to the CD terms |
Best For Comparing
The tax comparison is especially useful when you are deciding between similar pre-tax yields. Your state and local tax situation can affect the amount of income you keep from a CD, while Treasury interest generally receives the state and local exemption.
QUICK TAKE: The key numbers are not just the quoted yields. Look at the federal tax treatment, your applicable state and local taxes, and the resulting after-tax income.
Complete Beginner Guide to Treasury Bills vs CDs Tax Differences
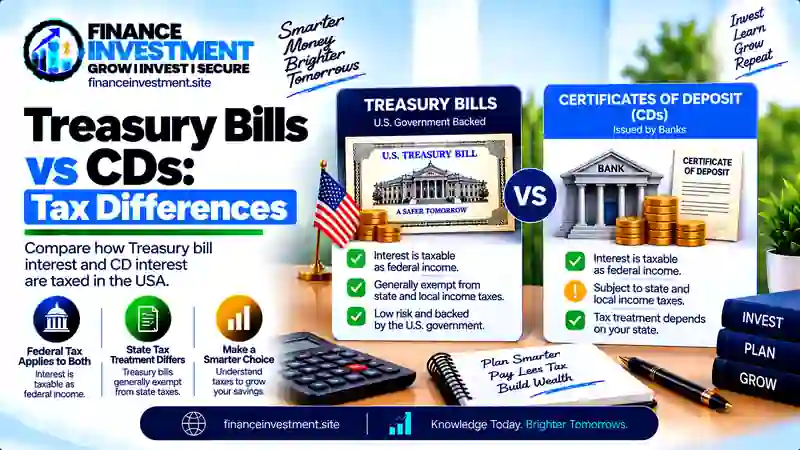 When comparing Treasury bills and CDs, the advertised yield is only part of the picture. Both can generate taxable income, but the tax treatment is not identical. The biggest difference is what happens at the state and local level.
1. How Are Treasury Bills Taxed?
Treasury bills are generally issued at a discount and mature at face value. For example, you might pay $9,800 for a $10,000 T-bill. If you hold it to maturity, the $200 difference is generally treated as interest income for federal tax purposes. Treasury bill interest is generally exempt from state and local income taxes. The IRS says Treasury interest is generally reported on Form 1099-INT, Box 3.
2. How Are CDs Taxed?
Interest from a certificate of deposit is generally taxable income for federal purposes. For many CDs, you include interest when you receive it or when it becomes available to you without a substantial penalty. Some deferred-interest CDs can follow different timing rules. CD interest also does not receive the federal exemption from state and local income taxes that applies to Treasury obligations.
3. Why Can Your State Matter?
Imagine a T-bill and a CD producing similar pre-tax income. If you live in a state or locality that taxes income, the CD may create an additional state or local tax cost, while qualifying Treasury interest generally remains exempt from those taxes. That can change the after-tax comparison.
4. How Is the Income Reported?
Treasury interest is generally shown on Form 1099-INT, Box 3. CD interest is generally reported by the financial institution on Form 1099-INT when the applicable reporting requirements are met. Keep your forms and purchase records, and remember that taxable interest generally must be reported even if a Form 1099-INT is not received.
EASY WAY TO REMEMBER: Both investments can create federal taxable income. The major tax advantage of Treasury bills is that interest from U.S. Treasury obligations is generally exempt from state and local income taxes.
How the Tax Treatment Works
A simple way to compare Treasury bills and CDs is to follow four questions: how the income is generated, when it is generally taxable, which taxes can apply, and how the income is reported. The products work differently, but these steps make the tax comparison easier to follow.
Step 1: Understand How the Income Is Created
A Treasury bill is generally issued at a discount and pays its face value at maturity. For a standard T-bill held to maturity, the difference between the purchase price and the amount received is generally treated as interest income. A CD normally earns interest according to the terms set by the financial institution.
Step 2: Consider Federal Income Tax
Interest from both investments is generally subject to federal income tax. The amount of federal tax you ultimately owe depends on your individual tax circumstances, so two investors receiving the same amount of interest may have different after-tax results.
Step 3: Check State and Local Taxes
This is the key distinction. Interest from U.S. Treasury obligations is generally exempt from state and local income taxes. CD interest does not receive that Treasury-specific exemption, so applicable state or local income taxes may affect the amount you keep.
Step 4: Compare After-Tax Income
Once you know the pre-tax income and the taxes that may apply, you can make a more meaningful comparison. A slightly different advertised yield can produce a different after-tax result once federal and applicable state or local taxes are considered.
THE SIMPLE VERSION: Both T-bills and CDs are generally subject to federal income tax. The major difference is that Treasury interest is generally exempt from state and local income taxes.
Benefits & Drawbacks of the Tax Differences
The tax gap between Treasury bills and CDs may look small on paper, but it can affect your actual income when state or local income taxes apply. The impact depends on your location, tax situation, and the return offered by each investment.
Benefits to Consider
- State and local tax exemption: Interest from U.S. Treasury obligations is generally exempt from state and local income taxes.
- Useful after-tax comparison: The exemption can make Treasury bills more tax-efficient than an otherwise similar taxable investment for some taxpayers.
- Clear tax classification: Treasury interest is generally reported separately from other interest on Form 1099-INT, with Treasury obligations generally shown in Box 3.
Drawbacks to Consider
- Federal tax still applies: Treasury bills generally do not avoid federal income tax.
- CDs may have different tax and account terms: Interest timing, early-withdrawal penalties, and account terms can affect the comparison.
- Tax is not the whole picture: Yield, maturity, liquidity, transaction costs, FDIC insurance for eligible CDs, and the nature of the underlying investment also deserve attention.
QUICK TAKE: Treasury bills generally have a state and local income-tax advantage, but that does not automatically make them the better choice. Compare the applicable taxes, return, terms, and access to your money together.
Treasury Bills vs CDs: Detailed Tax Comparison
Treasury bills and CDs can both produce taxable income, but their tax treatment is not identical. The biggest difference is the treatment of Treasury interest at the state and local level.
| Tax Factor | Treasury Bills | CDs |
|---|---|---|
| Federal income tax | Generally applies | Generally applies |
| State income tax | Generally exempt | May apply under applicable state rules |
| Local income tax | Generally exempt | May apply under applicable local rules |
| How income is generally created | Usually through the discount between purchase price and maturity value | Interest under the CD’s terms |
| Common federal reporting | Form 1099-INT, generally Box 3 | Form 1099-INT when reportable |
Why the Tax Difference Matters
Suppose a Treasury bill and a CD generate the same amount of pre-tax income. For a taxpayer who owes state or local income tax, the CD may produce a different after-tax result because qualifying Treasury interest is generally exempt from those taxes. The actual difference depends on the investor’s tax situation and the applicable rules.
COMPARE THE AFTER-TAX RESULT: A higher stated yield does not necessarily produce more income after taxes. Look at the applicable federal, state, and local tax treatment when comparing a T-bill with a CD.
Costs, Risks & Expert Tips
The tax difference is important, but it should not be viewed by itself. The purchase price, investment terms, access to your money, and other costs can all affect the return you ultimately keep.
Costs to Check
- T-bills: Check brokerage fees, bid-ask spreads, and any other transaction costs that may apply.
- CDs: Review early-withdrawal penalties, minimum requirements, and the CD’s account terms before investing.
- Taxes: Compare potential income after applicable federal, state, and local taxes rather than looking only at the stated yield.
Risks and Tax Details to Watch
Treasury interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally federally taxable and may also be subject to applicable state and local taxes. Selling a T-bill before maturity or using a nonstandard CD structure can require additional tax or reporting considerations.
EXPERT TIP: Keep purchase confirmations, maturity details, account statements, and tax forms together. When comparing a T-bill with a CD, consider the applicable tax rules and the investment terms before focusing on the headline yield.
Common Mistakes & Real-Life Example
Tax differences can be easy to overlook when two investments appear to offer similar returns. A few common mistakes can lead to an incomplete comparison between Treasury bills and CDs.
Common Tax Mistakes to Avoid
- Assuming T-bills are tax-free: Treasury bill interest is generally subject to federal income tax.
- Comparing only the advertised yield: The amount you keep after applicable taxes may be different from the headline return.
- Ignoring state or local taxes on CDs: CD interest does not receive the general state and local income-tax exemption that applies to qualifying U.S. Treasury interest.
- Forgetting tax records: Keep applicable Form 1099-INT forms and investment records so you can report taxable income accurately.
A Simple $10,000 Example
Imagine an investor puts $10,000 into a Treasury bill and another $10,000 into a CD. For illustration only, assume each investment produces $400 of taxable income before taxes. Both amounts are generally subject to federal income tax. If the investor’s state or local rules impose income tax on CD interest, the CD could create an additional state or local tax liability, while qualifying Treasury interest is generally exempt from those taxes.
This example does not determine the investor’s actual tax bill. Federal tax depends on the investor’s circumstances, and state and local treatment can vary. The key lesson is to compare the after-tax result rather than relying only on the advertised rate.
QUICK CHECK: Compare the same investment amount, similar time period, expected income, applicable taxes, and any account or transaction costs before deciding how the two options fit your situation.
Who Should Consider Treasury Bills or CDs?
The appropriate option depends on your goals, tax situation, time horizon, and how you want to access your money. Tax treatment is an important consideration, but it is only one part of the comparison.
Treasury Bills May Be Relevant If…
- You want short-term U.S. Treasury securities with defined maturities.
- State or local income-tax treatment is important when comparing after-tax income.
- You want to include Treasury securities as part of a broader fixed-income strategy.
CDs May Be Relevant If…
- You prefer a bank or credit-union deposit product with a stated term and interest rate.
- You are comfortable with the CD’s maturity period and understand its early-withdrawal terms.
- Eligible FDIC or NCUA insurance coverage is an important part of your deposit strategy, depending on where the CD is held.
REMEMBER: Compare tax treatment, maturity, liquidity, yield, applicable insurance coverage, and account terms together rather than focusing on one feature alone.
Frequently Asked Questions
Here are common questions about Treasury bills vs CDs tax differences, including federal taxation, state and local taxes, reporting, and tax timing.
1. Are Treasury bills or CDs taxed less?
Both are generally subject to federal income tax. Interest from U.S. Treasury obligations is generally exempt from state and local income taxes, while CD interest may be subject to applicable state and local taxes.
2. Are T-bills tax-free?
No. Treasury bill interest is generally subject to federal income tax. The key tax benefit is the general exemption from state and local income taxes.
3. Are CD earnings taxable?
Yes. CD interest is generally taxable for federal income tax purposes. State and local taxation depends on the applicable rules and the investor’s jurisdiction.
4. Do T-bills avoid state income tax?
Generally, yes. Interest from U.S. Treasury bills, notes, and bonds is generally exempt from state and local income taxes.
5. Do CDs pay state income tax?
CD interest may be subject to state or local income taxes. The exact treatment depends on the applicable jurisdiction and tax rules.
6. How is T-bill interest reported?
Treasury bill interest is generally reported on Form 1099-INT, with Treasury interest shown in Box 3. Taxpayers generally must report taxable interest even if they do not receive a Form 1099-INT.
7. When is CD interest taxed?
For many CDs, interest is generally included in income when received or when you are entitled to receive it without paying a substantial penalty. Certain CDs with deferred interest or longer terms can have different OID reporting rules.
8. Should I compare T-bills and CDs by after-tax yield?
Comparing potential after-tax income can give you a clearer picture than comparing stated yields alone, especially when state or local taxes may apply to CD interest.
IMPORTANT: Tax rules can vary based on the investment structure and your individual circumstances. Use current IRS guidance and your tax professional when a specific tax situation requires personalized advice.
Final Verdict: Treasury Bills vs CDs: Tax Differences
The main tax difference between Treasury bills and CDs is straightforward: both are generally subject to federal income tax, but interest from U.S. Treasury obligations is generally exempt from state and local income taxes. CD interest may also be subject to applicable state and local taxes.
That difference can affect the amount you keep after taxes, particularly when state or local income taxes apply. However, taxes are only one part of the comparison. Maturity, liquidity, yield, early-withdrawal terms, and the applicable protections for the investment should also be reviewed.
For a broader introduction to Treasury securities, see our Treasury Bills Explained guide before comparing specific investments.
KEY POINT: Compare Treasury bills and CDs using potential after-tax income along with maturity, liquidity, yield, and investment terms rather than relying on the advertised rate alone.