Tag: CD Strategies

  • Callable CDs Explained: How They Work, Risks & Rates in 2026

    Callable CDs Explained: How They Work, Risks & Rates in 2026


    Callable CDs Explained: How They Work in 2026

    FINANCEINVESTMENT
    Callable CDs, Explained Clearly

    Written by Subhash Rukade

    Updated August 29, 2026

    A practical guide to understanding callable CDs, including
    call dates, interest rates, access, risks and the details
    worth checking before opening one.

    Callable CDs: A Higher Rate With an Important Catch
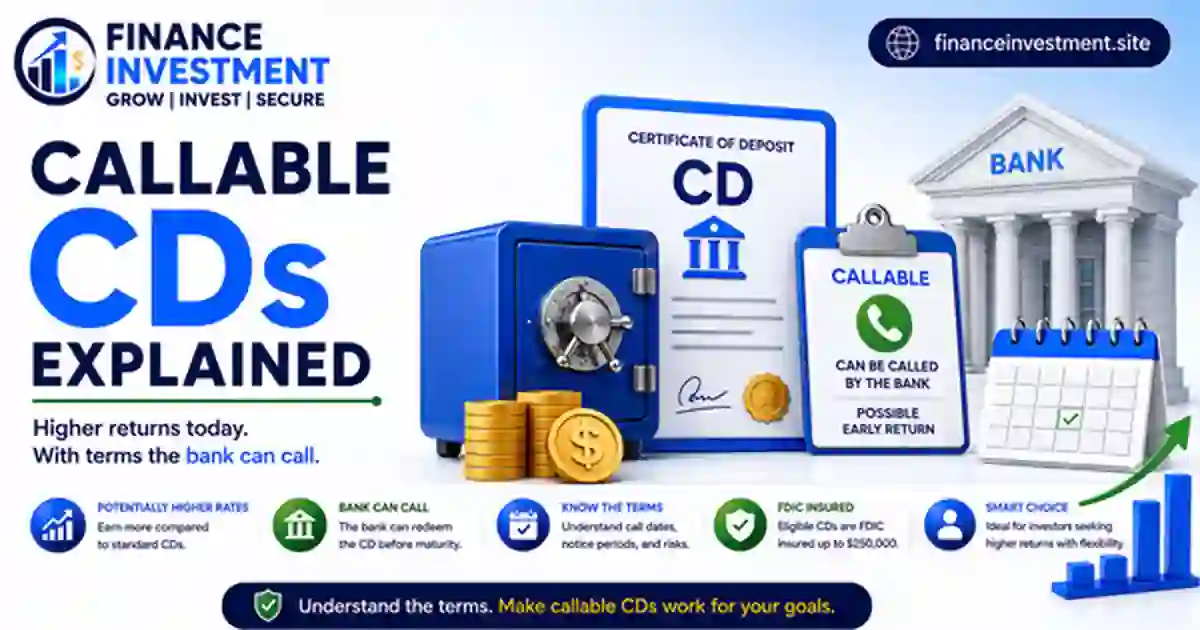
    Callable CDs Explained: callable certificate of deposit rates, call dates and risksA callable CD can look appealing when its advertised rate is higher than
    what you see on a comparable traditional CD. But there is a detail that
    deserves attention: the bank or credit union may have the right to end
    the CD before its stated maturity date. That feature can change how you
    think about the return you are actually getting.

    For example, imagine locking in a strong rate for several years. If market
    rates later fall, the issuer may decide to call the CD according to the
    terms of the account. You receive the amount specified under the contract,
    but you may then have to reinvest that money at lower rates. The attractive
    rate you saw at the beginning, therefore, is not always the same as the
    rate you can count on for the entire advertised term.

    If you are new to CDs, start with the broader

    CD Guide 2026

    before comparing more specialized CD types.

    What You’ll Learn

    This guide will show you how callable CDs work, what a call date means,
    why issuers may exercise the call option, and how callable CDs differ
    from standard CDs. You will also see the trade-offs involving rates,
    liquidity, taxes, insurance, reinvestment and maturity—so you can judge
    an offer by its full terms rather than its headline APY alone.

    Quick Answer: What Is a Callable CD?

    A callable CD is a certificate of deposit that can be
    ended early by the issuing bank or credit union under specific terms.
    In exchange for giving the issuer this flexibility, a callable CD may
    offer a more attractive rate than some comparable CDs. The important
    catch is that you cannot assume the advertised rate will remain in place
    for the entire stated term if the CD is called.

    Key Takeaways

    • Issuer controls the call: The bank decides whether to exercise its call option.
    • Rates are typically fixed: The stated rate generally stays fixed while the CD remains outstanding.
    • Call risk matters: A called CD can leave you looking for a new place to invest your money.
    • Protection may apply: Eligible deposits at an FDIC-insured bank or federally insured credit union can receive applicable deposit insurance.
    • Taxes still matter: CD interest is generally taxable income when required under federal tax rules.
    • Read the call terms: Check the call date, notice provisions, term and what happens if the issuer calls the CD.
    Bottom Line:
    A callable CD can offer a compelling rate, but the extra yield comes with
    issuer call risk. Look beyond APY and make sure the call provisions fit
    your time horizon and need for predictable income.

    Callable CDs at a Glance

    A callable CD combines a fixed deposit rate with an issuer’s right to
    redeem the CD before its stated maturity. That extra feature makes the
    call terms just as important as the advertised APY.

    Key FactWhat to Know
    RateUsually fixed while the CD remains outstanding.
    Call periodThe issuer can call the CD only according to its stated terms.
    MaturityThe original term may be longer than the period the CD actually stays open.
    AccessEarly access is governed by the contract; a callable CD is not the same as a no-penalty CD.
    ProtectionEligible deposits may receive FDIC or NCUA insurance within applicable limits.
    MinimumDeposit requirements vary by institution and product.
    TaxesInterest is generally taxable income for federal tax purposes.

    Best use: Callable CDs may suit savers who value a potentially
    higher fixed rate and can accept the possibility of having their money
    returned earlier than expected.

    Complete Beginner Guide to Callable CDs
    Callable CDsA callable CD is a type of certificate of deposit with one important
    difference from a basic CD: the financial institution may have the right
    to end the CD before its scheduled maturity date. The account still works
    around a deposit, an interest rate and a defined term, but the issuer gets
    an additional option that can affect how long your money stays invested.

    How the Basic Structure Works

    You start by depositing a specific amount, known as the principal.
    The bank then pays interest according to the rate and terms disclosed when
    you open the account. The APY shows the annualized return while
    accounting for the effect of compounding, making it more useful for comparing
    CD offers than a simple interest rate alone.

    The term tells you the scheduled length of the CD, such as
    one year, three years or five years. At maturity, the CD reaches
    the end of that scheduled term. With a callable CD, however, the issuer may
    be able to redeem it earlier if the contract allows a call during the
    specified call period.

    Callable CD vs. Standard CD

    A standard CD generally keeps your money invested until its stated maturity,
    unless you withdraw early under the account’s withdrawal rules. A callable
    CD adds issuer call risk: the institution can potentially return your
    principal and applicable interest before the original maturity date.
    That is why a higher advertised rate should be considered alongside the
    call schedule and other contract details.

    Where Ownership Fits In

    CDs can be held individually or jointly, depending on the institution and
    account structure. Eligible deposits at an FDIC-insured bank or federally
    insured credit union may receive applicable deposit insurance within legal
    limits. Callable CDs therefore sit closer to the cash-saving side of a
    portfolio than to higher-volatility investments, although the call feature
    creates a reinvestment consideration that ordinary savings accounts may not.

    For a broader foundation, see our

    guide to standard CDs

    How Callable CDs Work

    A callable CD follows a fairly simple path, but one extra feature can
    change the outcome: the issuing bank or credit union may have the right
    to redeem the CD before its scheduled maturity. Here is how the process
    typically unfolds.

    1. Choose the CD and Review the Call Terms

    Before opening the account, check the APY, deposit requirement, scheduled
    term and, most importantly, the call provisions. Look for the first
    possible call date, how often the issuer can call the CD and what you
    receive if the CD is redeemed.

    2. Fund the Account

    You deposit the required principal according to the institution’s rules.
    Once the CD is opened, the disclosed rate generally applies while the
    account remains outstanding under its terms.

    3. Interest Accrues

    The CD earns interest according to its stated rate and compounding
    schedule. Your actual earnings can depend on when interest is credited,
    whether it is paid out or added to the balance, and the product’s
    specific terms.

    4. The Issuer Reaches the Call Date

    Once the CD becomes callable, the issuer can exercise its call option
    if the contract permits it. This is controlled by the institution—not
    by the depositor. If the issuer does not call the CD, it can continue
    toward its original maturity.

    5. Called CD vs. CD That Reaches Maturity

    If the CD is called, the institution returns the amount specified under
    the contract, ending the deposit earlier than originally expected. You
    then have to decide where that money goes next. If the CD reaches
    maturity instead, you can follow the maturity instructions, such as
    withdrawing the funds, transferring them or allowing an eligible renewal.

    Practical point:
    A callable CD does not give you control over the timing of the exit.
    The call schedule tells you when the issuer gets that option, so keep
    your own cash needs separate from money committed to the CD.

    Benefits & Drawbacks of Callable CDs

    Callable CDs can be attractive when the rate is competitive, but the
    higher potential return comes with a trade-off. The key question is
    whether the added rate is worth giving the issuer more control over
    when the CD ends.

    ✓ Benefits

    • Potentially attractive rates: Some callable CDs may
      offer a higher rate to compensate savers for accepting the call feature.
    • Rate stability: While the CD remains outstanding,
      its stated rate generally does not fluctuate with daily market rates.
    • Deposit protection: Eligible deposits at an
      FDIC-insured bank or federally insured credit union may receive
      applicable insurance within coverage limits.
    • Defined structure: The CD provides a stated term,
      rate and contractual call provisions rather than leaving every detail
      open-ended.

    ⚠ Drawbacks

    • Call risk: The issuer may redeem the CD before its
      scheduled maturity when the contract allows it.
    • Reinvestment risk: If the CD is called after rates
      fall, comparable new deposits may offer less attractive returns.
    • Inflation risk: A fixed rate may lose purchasing power
      if inflation remains higher than the return.
    • Less certainty about timing: You may receive your
      money earlier than planned, which can disrupt a specific savings goal.

    Benefits & Drawbacks of Callable CDs

    A callable CD can be appealing when you want a fixed return and the
    offered rate is competitive. The trade-off is that the bank gets an
    option that a standard CD usually does not: it may be able to redeem
    the CD before the scheduled maturity date.

    Benefits of Callable CDs

    • Potentially higher rates:
      Some callable CDs offer a stronger APY than comparable products to
      compensate for the issuer’s call option.
    • Fixed-rate structure:
      The stated rate generally remains fixed while the CD stays outstanding
      under its terms.
    • Deposit protection:
      Eligible deposits may receive FDIC or NCUA insurance within applicable
      coverage limits.
    • Defined terms:
      The contract spells out the rate, scheduled maturity and circumstances
      under which the issuer can call the CD.

    Drawbacks to Consider

    • Call risk:
      The issuer may end the CD early when the contract permits it.
    • Reinvestment risk:
      If rates have fallen when your CD is called, a new CD may offer a
      lower return.
    • Inflation risk:
      A fixed return may not keep pace with rising prices.
    • Less control over timing:
      The money could come back before your original savings plan reaches
      its intended date.
    Key point:
    A higher APY can be useful, but it should be weighed against the possibility
    that the issuer ends the CD when market conditions make that attractive
    for the institution.

    Callable CDs Compared With Other Savings Options

    A callable CD is not automatically better than a regular CD or a savings
    account. Each option gives you a different mix of return, access and
    predictability. The biggest distinction is who controls the timing: with
    a callable CD, the issuer may have the right to end the deposit early.

    OptionRateAccessBest Use
    Callable CDUsually fixedContract-based; issuer may call earlySavers seeking a fixed return who accept call risk
    Standard CDUsually fixedLimited before maturityMoney with a defined time horizon
    High-Yield SavingsVariableGenerally easyEmergency funds and flexible savings
    Money Market AccountUsually variableMore flexible than a CDCash reserves needing convenient access

    Minimum deposits and fees vary by institution, so the advertised APY is
    only one part of the decision. Eligible deposits at an FDIC-insured bank
    or federally insured credit union can receive applicable deposit insurance
    within coverage limits. Interest earned from these deposit products is
    generally taxable income, although the exact tax treatment depends on the
    account and your circumstances.

    If you are deciding between a callable product and a conventional deposit,
    our

    Standard CDs Explained

    guide provides a useful starting point. For a more flexible comparison,
    see our guide to

    CDs vs. high-yield savings accounts
    .

    Quick takeaway:
    A callable CD can make sense for a rate-focused saver who accepts issuer
    call risk. A high-yield savings account or money market account may be
    more suitable when keeping funds readily accessible matters more.

    Costs, Risks & Expert Tips for Callable CDs

    The most important cost of a callable CD is not always a visible fee.
    The bigger concern can be what happens when the issuer exercises its
    call option. A good offer should be judged by its full terms, not just
    the headline APY.

    Costs and Risks to Check

    .  Call Risk-   bank’s decision to call a CD is not the same as a customer’s early
    withdrawal. When the issuer exercises its call right, the redemption
    follows the terms stated in the CD agreement. Your own withdrawal rights
    are a separate matter.

    • Reinvestment risk: If market rates have fallen when
      the CD is called, replacing it could mean accepting a lower yield.
    • Early-withdrawal rules: Do not assume that a callable
      CD gives you penalty-free access. Your own withdrawal rights are
      determined by the account agreement.
    • Inflation: A fixed return can lose purchasing power
      when inflation runs above the CD’s effective return.
    • Taxes: Interest from taxable CDs is generally subject
      to federal income tax, even when the money remains in the account.
    • Fees and minimums: Check the institution’s disclosure
      for account fees, minimum opening deposits and any conditions attached
      to the advertised rate.

    Practical Checks Before Opening One

    1. Find the exact first call date and full call schedule.
    2. Confirm what you receive if the issuer calls the CD.
    3. Verify that the institution is FDIC-insured or federally insured by NCUA, as applicable.
    4. Check your total deposits against applicable insurance limits.
    5. Keep money needed for near-term bills outside the CD.
    6. Decide in advance where the funds could go if the CD is called.

    Expert Tip

    Treat the call date as a planning date, not a guaranteed maturity date.
    If the money has a specific future job, keep enough flexibility elsewhere
    so an unexpected early redemption does not force a rushed reinvestment decision.

    Common Callable CD Mistakes and an Illustrative Example

    Illustrative Example — Not a Real Customer CaseSuppose a saver places $10,000 into a callable CD with a fixed rate.
    The issuer later calls the CD before its scheduled maturity. The saver
    receives the applicable principal and interest, but now has to decide
    where to place the money. If comparable CD rates have fallen, the next
    available rate may be lower.


    Common Mistakes to Avoid

    • Choosing by APY alone: A higher rate does not tell you
      when the issuer can call the CD or how long you may actually keep that rate.
    • Skipping the call schedule: The first callable date,
      notice provisions and redemption terms deserve a careful look.
    • Assuming every callable CD works the same way:
      Call periods, terms and redemption conditions can differ between products.
    • Overlooking insurance: Verify the institution and keep
      your deposits within applicable FDIC or NCUA coverage limits.
    • Forgetting taxes: Interest from a taxable CD can create
      income-tax consequences even if you leave the earnings in the account.
    • Ignoring liquidity: Money needed for an upcoming expense
      should not depend on whether a callable CD remains open.
    • Having no reinvestment plan: If the CD is called, rates
      available at that time may be lower than the rate you originally locked in.

    Who Should Consider a Callable CD?

    Callable CDs can make sense for savers who are comfortable trading some
    control over timing for a potentially attractive fixed rate. They may be
    worth considering when the money is not needed for everyday expenses and
    the account’s call terms are easy to understand.

    Who May Find Them Useful?

    • Beginners: Those learning about fixed-rate deposits and
      willing to read the contract carefully.
    • Families: Savers setting aside money for a known future
      goal who can handle an earlier return of funds.
    • Retirees: Investors seeking predictable interest from
      eligible deposit products, provided the call risk fits their income plan.
    • Larger-balance savers: People who can manage deposit
      insurance limits across institutions when necessary.
    • Conservative investors: Those who prioritize principal
      stability over market-based growth.

    When Another Option May Fit Better

    If you need frequent access to the money, a

    high-yield savings account

    may offer greater flexibility. A standard CD can be easier to plan around
    when you want a defined maturity without an issuer call feature. For a
    very short-term goal, keeping the money readily available may matter more
    than locking in a potentially higher rate.

    Frequently Asked Questions About Callable CDs

    What is a callable CD?

    A callable CD is a certificate of deposit that gives the issuing
    institution the right to redeem the CD before its scheduled maturity,
    subject to the contract’s call terms.

    Are callable CDs safe?

    They can provide principal stability when offered by an eligible
    insured institution, but the call feature creates reinvestment risk.
    They are not the same as investments whose market value fluctuates.

    Are callable CDs FDIC insured?

    An eligible callable CD issued by an FDIC-insured bank may be covered by
    FDIC deposit insurance within applicable limits.

    How does the call date work?

    The call date is the earliest date on which the issuer may exercise its
    redemption right if the contract permits it. It does not mean the CD
    will definitely be called.

    Is the rate on a callable CD fixed?

    Callable CDs commonly have a fixed stated rate while the CD remains
    outstanding, but the issuer’s call option can shorten the period during
    which you receive that rate.

    What happens if a callable CD is called early?

    The institution redeems the CD according to the contract, returning the
    applicable principal and interest. You then decide how to use or
    reinvest the funds.

    Do callable CDs have minimum deposits?

    Minimum opening deposits vary by bank, credit union and product. Always
    check the specific account disclosure rather than assuming every callable
    CD has the same requirement.

    Are callable CD earnings taxable?

    Interest from a taxable CD is generally included in income for federal
    tax purposes. Your actual tax treatment can depend on the account and
    your individual circumstances.

    Can I withdraw from a callable CD whenever I want?

    No. A callable CD’s issuer call feature is different from your own
    withdrawal rights. Any early withdrawal by you is governed by the
    account agreement and may involve a penalty.

    Are callable CDs good for short-term savings?

    They may not be ideal when you need dependable access to the money on a
    specific date. A flexible savings option can be easier to manage for
    short-term needs.

    Final Verdict: Are Callable CDs Worth Considering?

    Callable CDs can be a useful choice for savers who want a fixed rate and
    are comfortable with the possibility that the issuer may end the CD before
    its scheduled maturity. They can work particularly well when you have a
    defined savings goal but do not need to control the exact date your money
    comes back.

    Still, the highest APY should not automatically win. The first call date,
    call schedule and redemption terms can matter just as much as the quoted
    rate. If the CD is called after market rates have fallen, finding a
    comparable replacement may be difficult.

    Liquidity also deserves attention. Keep money needed for emergencies or
    near-term expenses somewhere easier to access. And remember that interest
    from taxable CDs can affect your federal tax bill, reducing your
    after-tax return.


    Bottom Line

    A callable CD is best viewed as a trade-off: potentially attractive fixed
    earnings in exchange for issuer call risk. For a broader look at CD types,
    strategies and choosing a product, explore our

    CD Guide 2026
    .

    Related Resources

    Want to go deeper before choosing a CD? These guides cover the practical
    questions that usually come next:

    For authoritative information, review

    FDIC deposit insurance
    ,

    Treasury.gov

    and the

    IRS

    for current federal guidance.

    FINANCEINVESTMENT

    Make Your Next CD Decision With Confidence

    Want more practical guidance on CDs, rates and savings strategies?
    Explore our

    CD Guide 2026

    and keep learning before you lock in your next deposit.
    You can also reach us at

    subhashr325@gmail.com
    .
  • CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    FINANCEINVESTMENT • CD STRATEGIES 2026

    CD Ladder vs CD Barbell Strategy: Which One Fits Your Goals?

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    Compare two practical ways to spread CD maturities, balance liquidity, and manage rate risk without making your cash strategy unnecessarily complicated.

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?
    CD Ladder vs CD Barbell Strategy explained for 2026. Compare maturity schedules, liquidity, rate risk, flexibility, and which strategy may fit your goals.
    cd-ladder-vs-cd-barbell-strategy
    CD Ladder vs CD Barbell Strategy
    CD ladder strategy,
    CD barbell strategy,
    CD ladder vs barbell,
    ladder vs barbell CDs,
    CD laddering,
    barbell CD strategy,
    CD investment strategy,
    CD maturity strategy,
    CD liquidity strategy,
    CD rate risk
    https://financeinvestment.site/cd-ladder-vs-cd-barbell-strategy/
    Subhash Rukade
    August 24, 2026
    About 10–12 minutes

    CD Ladder vs CD Barbell Strategy: Start With Your Cash Timeline

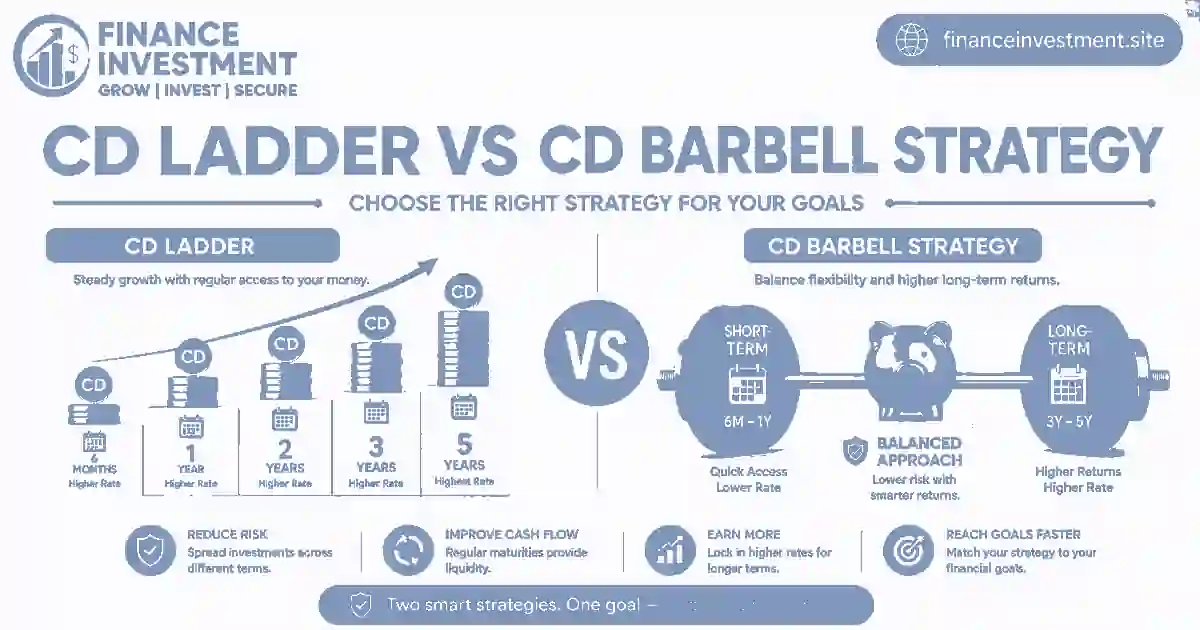
    CD Ladder vs CD Barbell StrategyWhen people compare a CD Ladder vs CD Barbell Strategy, they often start by asking which one earns more. That can miss the bigger issue. The more useful question is when you expect to need the money again. A strategy that works beautifully for someone with several upcoming expenses may feel restrictive to someone who mainly wants access to cash at the short and long ends of the timeline.

    A CD ladder spreads money across several maturity dates. That creates a steady stream of opportunities to reassess or use funds. A barbell takes a different route. It typically places money toward shorter and longer maturities while leaving less in the middle.

    Neither structure automatically wins. Your expected cash needs, comfort with locking money away, views on future rates, and desire for regular access can point you toward one design over the other. The goal is to build a schedule that makes sense for your money instead of forcing your money into a preset formula.

    If you want to refresh the basics before comparing these strategies, our

    CD Guide 2026

    explains CD basics, terms, rates, and the details worth checking before you choose an account.

    What You’ll Learn

    • How CD ladders and barbells are structured
    • Where each strategy can fit different cash needs
    • How maturity timing affects liquidity
    • The trade-offs involving rates and reinvestment
    • How to choose a structure without overcomplicating your savings plan

    Quick Answer: CD Ladder or CD Barbell?

    A CD ladder generally spreads money across multiple maturity dates, while a CD barbell concentrates more of the money in shorter and longer terms, with less in the middle. A ladder can offer more regular access points; a barbell can keep some cash relatively near-term while committing another portion for longer.

    6 Key Takeaways

    1. Ladder: Several CDs mature at different points.
    2. Barbell: Money is concentrated toward short and long maturities.
    3. Liquidity: A ladder can create more frequent maturity dates.
    4. Rate exposure: A barbell can give you both shorter-term flexibility and longer-term rate certainty.
    5. Cash needs matter: Upcoming expenses can influence which structure makes more sense.
    6. There is no universal winner: The better setup is the one that matches your timeline and comfort with locked-up money.

    Bottom line: A ladder is useful when you want several planned maturity dates. A barbell may fit better when you want a short-term pool alongside a longer commitment.

    CD Ladder vs CD Barbell: At a Glance

    The two structures differ mainly in where your maturity dates sit. A ladder usually creates a sequence of scheduled maturities, while a barbell places more weight at the short and long ends. That difference can affect how often you can access cash and how much of the portfolio is committed for longer periods.

    FeatureCD LadderCD Barbell
    Typical structureSeveral staggered maturitiesShort and long maturities
    Liquidity patternMore frequent maturity pointsMore concentrated access
    Rate exposureSpread across maturitiesShort and long rate exposure
    May suitSavers wanting scheduled access pointsSavers comfortable pairing near-term access with longer commitments

    Quick read: A ladder emphasizes a sequence of maturity dates. A barbell emphasizes separation between the short and long ends. The real difference is how each structure distributes your maturity dates and future decisions.

    How to Build a CD Ladder or Barbell From Scratch

    Building either strategy starts with the same basic question: how much money can you commit without needing it unexpectedly? Once that amount is clear, the structure becomes easier to design. Keep your emergency reserve and near-term spending money outside the CDs first. The remaining cash can then be divided according to your timeline.

    Building a CD Ladder

    A simple ladder divides your deposit among certificates with different maturity dates. For example, someone with $20,000 might place $5,000 into four CDs with staggered terms. As each certificate matures, the owner can use the money or reinvest it into a new longer-term CD.

    The exact terms do not have to follow one fixed formula. You might use six-month, one-year, 18-month, and two-year certificates, depending on available rates and when you expect to need the cash. Pick maturity dates that match real expenses or review points instead of filling every available term.

    Building a CD Barbell

    A barbell uses two ends of the maturity spectrum. One portion can sit in shorter CDs for relatively earlier access, while another portion can use longer certificates for a longer rate commitment. There is no universal percentage split. Your spending needs and tolerance for locking money away should guide the allocation.

    Plan the Reinvestment Before Maturity

    Decide in advance what you might do when a certificate matures. If you need the cash, move it to the account where you will spend it. If you still have a long-term need, consider reinvesting after checking current rates. Avoid automatic renewal simply because it is convenient.

    Practical Tip

    Keep a simple maturity calendar. Knowing which CD matures next can be more useful than trying to remember every account detail.

    How a CD Ladder and Barbell Work Over Time

    CD Ladder vs CD Barbell StrategyThe main difference becomes clearer once the certificates are actually in place. You are not simply choosing several CDs; you are creating a schedule for when portions of your money become available and when you will decide what to do next.

    How a CD Ladder Moves

    Imagine you divide $24,000 into four $6,000 CDs. You could choose terms that mature at different points, such as six months, one year, 18 months, and two years. When the first CD matures, you can take the money for a planned expense or reinvest it into a new certificate. The other CDs continue following their original schedules.

    You can compare the current CD market, check whether your original goal has changed, and decide whether that slice of money still belongs in another CD. That gives the strategy a built-in review point instead of requiring you to commit the entire balance at one time.

    How a CD Barbell Moves

    Now consider a $24,000 barbell. You might place $8,000 in shorter-term CDs and $16,000 in a longer-term certificate. The short side can provide an earlier opportunity to access or reposition part of the money, while the longer side remains committed for a longer period.

    The two sides do not have to be equal. A saver expecting a major expense soon might give more weight to the short end. Someone comfortable leaving most of the money untouched could place more toward the longer end.

    Illustrative example: Mark expects to need some cash within a year but wants another portion working for several years. A barbell may give him two distinct time horizons, while a ladder would spread those maturities more evenly.

    In both structures, the important work happens when a CD matures. That is when you reassess the rate, timing, and purpose of that portion of the money rather than automatically repeating the old decision.

    Benefits and Drawbacks of CD Ladders and Barbells

    The appeal of these strategies comes from giving each portion of your cash a different place on the calendar. That can make a large balance easier to organize, but the structure also creates trade-offs you should understand before committing the money.

    ✓ Pros

    • Planned access: A ladder can create regular maturity dates, giving you more opportunities to use or reposition cash.
    • Rate diversification: Different maturity dates can reduce the need to commit the entire balance at one rate.
    • Reinvestment choices: Each maturity gives you a chance to compare current rates before putting the money back to work.
    • Flexible structure: A barbell can pair shorter commitments with longer ones instead of spreading money evenly.

    ⚠ Cons

    • Timing risk: A maturity date may not arrive when you actually need the money.
    • Concentration: A barbell can leave a larger share committed at one end of the maturity range.
    • Inflation risk: Fixed CD returns may lose purchasing power when prices rise faster than the account’s return.
    • Reinvestment risk: A maturing CD may need to be renewed when available rates are lower.

    That timing control is useful only if your cash outside the CDs is large enough to handle unexpected expenses.

    CD Ladder vs CD Barbell: Side-by-Side Comparison

    Once you move beyond the basic definitions, the choice comes down to how much control you want over maturity dates and where you want your rate exposure. A ladder spreads decisions across time, while a barbell creates a sharper split between shorter and longer commitments.

    FactorCD LadderCD Barbell
    StructureMoney is divided across several maturity dates.Money is concentrated around shorter and longer terms.
    LiquidityCan create more frequent maturityAccess is generally concentrated in the shorter-term portion.
    Maturity spreadBroad and staggered.Focused at two ends.
    ReinvestmentDecisions occur more regularly.Fewer, more concentrated decisions.
    ComplexityCan require tracking several CDs.Can be simpler to maintain.
    May suitSavers who value recurring maturity dates.Savers who want a short-term pool alongside longer commitments.

    The strategy can also be adjusted around the available products. For example, you could review
    6-month CD rates
    for the shorter side and compare them with
    5-year CD rates
    for a longer commitment. If you are unsure which term fits your cash needs, our guide on
    choosing the right CD
    can help frame the decision.

    Neither structure guarantees a better return. The useful comparison is how well each one fits your expected cash flow, tolerance for locked-up funds, and willingness to revisit rates over time.

    Costs, Risks and Expert Tips for CD Ladders and Barbells

    A well-planned CD structure can make your cash easier to manage, but it cannot remove the normal risks of certificates. The biggest issues usually appear when your circumstances change, rates move, or a maturity date arrives at an inconvenient time.

    Risks to Check Before Funding

    Early withdrawal penalties can reduce your interest if you need money before a CD matures. That matters in both strategies, especially if the amount at a particular maturity is smaller than the expense you eventually face.

    Opportunity cost matters when rates change. A long-term CD can keep earning its agreed rate while newer certificates become more attractive. On the other hand, short-term CDs may mature when available rates are lower. Inflation can also reduce the purchasing power of a fixed return.

    Insurance and taxes deserve a separate check. Check that eligible deposits are within applicable FDIC or NCUA coverage limits, including the relevant ownership category and institution. particularly when several CDs are held at the same institution. Interest from taxable CDs can also affect your tax bill and after-tax return.

    Expert Checks Before You Build or Renew

    Premium Expert Tip

    Write down every CD’s balance, APY, maturity date, penalty, ownership category, and renewal instructions. Then review the schedule as a whole. Several CDs can end up maturing close together, while a barbell can leave a large share of the balance tied to the long end.

    Before renewing, compare the new rate with current offers and ask whether the original cash plan still applies. Also check whether you still need the same balance at each maturity. A strategy should be adjusted when your financial timeline changes.

    Finally, keep emergency cash outside the certificates. A ladder or barbell works best when you are not forced to break a CD simply because an unexpected bill arrives.

    Common CD Ladder and Barbell Mistakes

    The trouble usually starts with the details: too many CDs, poorly spaced maturities, or money that should never have been locked up. The most common errors are usually not about picking a particular bank. They come from building a schedule that does not match the way the money will actually be used.

    Mistakes to Watch For

    • Making the structure too complicated: A ladder with too many small certificates can become difficult to track. If the added complexity does not create useful maturity dates, simplify it.
    • Clustering maturities: Several CDs that mature within the same narrow period may leave you with less flexibility than expected.
    • Using emergency cash: Money that may be needed immediately should not depend on a CD reaching maturity.
    • Ignoring renewal dates: A certificate can automatically renew according to its terms if you do not act during the applicable window.
    • Chasing rates: Moving money repeatedly for a slightly higher APY can add unnecessary work and may leave the maturity schedule disconnected from your goals.

    Illustrative Example: David Simplifies His Ladder

    David initially creates six small CDs because he wants frequent maturity dates. After reviewing the accounts, he realizes two mature within the same month and several balances are too small to make the extra tracking worthwhile. He consolidates his plan around fewer, more useful maturity points while keeping his emergency savings separate.

    Illustrative lesson: A useful CD strategy does not need to be complicated. The schedule should make your cash easier to manage, not create another chore.

    Before adding another certificate, look at the entire schedule rather than evaluating the new CD by itself. That simple habit can reveal gaps, clusters, and unnecessary commitments.

    Who Should Choose a CD Ladder or Barbell?

    A CD ladder may appeal to savers who want several planned points when money becomes available. It can work well for families with expenses spread across the year, retirees who want periodic access to part of their cash, or investors who prefer making smaller reinvestment decisions over time.

    A ladder tends to make sense for savers who want several planned maturity dates. keeping part of the money relatively accessible while committing another portion for a longer period. It can be useful when near-term liquidity and longer-term rate certainty both matter.

    Neither structure is necessary for every saver. If the balance is modest or the goal has one clear date, a single CD may be easier to manage. And if you may need the money without warning, a flexible savings account can be a better home for that cash.

    Quick Decision Guide

    • Want recurring maturity dates? Consider a ladder.
    • Need short and long commitments? Consider a barbell.
    • Have one clear cash date? A single CD may be enough.
    • Need immediate access? Keep the money flexible.

    Frequently Asked Questions About CD Ladders and Barbells

    What is the main difference between a CD ladder and a CD barbell?

    A ladder distributes money across a series of maturity dates, while a barbell puts greater weight on shorter and longer terms. The choice mainly changes how your cash becomes available over time.

    How many CDs do I need to build a CD ladder?

    There is no fixed number. A few certificates can create useful maturity dates, while a larger balance may support more steps. Keep the structure simple enough to track.

    Does a CD ladder provide more liquidity than a barbell?

    A ladder can create more maturity points, but that does not mean the money is available on demand. A CD generally remains subject to its terms until maturity.

    Which strategy has more rate risk?

    Both have rate exposure in different ways. A ladder spreads renewal decisions across time, while a barbell can leave more money committed at the long end.

    What happens when a CD in a ladder matures?

    You can generally use the money, move it elsewhere, or reinvest it after reviewing current rates and your financial needs.

    Can I change a CD ladder after I build it?

    Yes. As certificates mature, you can change the next term or amount rather than rebuilding the entire structure from scratch.

    Do CD ladders and barbells require a minimum deposit?

    Each bank or credit union sets its own CD minimums. Building a strategy with several certificates may require enough money to meet those minimums comfortably.

    Are CDs in a ladder or barbell federally insured?

    Eligible bank CDs may receive FDIC insurance, while qualifying credit-union share certificates may receive NCUA federal share insurance. Coverage limits and ownership categories apply.

    Are CD ladder and barbell earnings taxable?

    Interest from CDs held in a regular taxable account is generally taxable interest income. Your actual tax treatment depends on your circumstances and account type.

    Illustrative: Which strategy could fit a $30,000 balance?

    Illustrative comparison only: A saver could divide $30,000 among several maturity dates for a ladder or place more toward short and long terms for a barbell. The better structure depends on when the saver expects to need the money, not simply the balance size.

    Final Verdict: Which CD Strategy Makes More Sense?

    Choose a ladder if your main priority is having several planned maturity dates. Choose a barbell if your money has two different time horizons and you want a shorter-term portion alongside longer-term CDs. A ladder makes more sense when you want several maturity dates and prefer to spread your cash decisions across time. A barbell can be useful when you have two clear priorities: keeping one portion relatively near-term while giving another portion a longer runway.

    The key is to build around your expected cash needs rather than choosing a structure simply because it looks attractive on a rate table. A higher APY can lose its appeal if the money becomes unavailable when you need it, or if a maturity schedule creates more management work than you want.

    If you want to review CD basics, terms, safety considerations, and rate factors before choosing a structure, see our

    CD Guide 2026
    .

    Practical takeaway: Map out when you may need the money first. Then choose the CD structure that gives those dollars the right maturity dates.

    Build a CD Strategy That Fits Your Timeline

    A useful CD strategy starts with your cash needs, not with a complicated formula. Start with when you may need the money, then choose a structure that makes those dates easier to manage. For practical finance guides and new money insights, join our newsletter.

    📧 subhashr325@gmail.com