Tag: Banking Tips

  • How to Transfer Money From One Bank to Another (2026)

    How to Transfer Money From One Bank to Another (2026)

    BANKING & MONEY TRANSFERS

    How to Transfer Money From One Bank to Another
    Written by Subhash Rukade
    Founder, FinanceInvestment
    Publish date: October,  25, – 10.


    how to transfer money from one bank to another

    Knowing how to transfer money from one bank to another can make it easier to manage savings, pay bills, move money between your own accounts, or send funds to someone else. In the United States, the right method depends on how quickly the money needs to arrive, the amount you’re sending, and the fees or transfer limits that apply.

    Most people can start a transfer through their bank’s website or mobile app. Depending on the banks and services involved, options may include an external bank transfer using ACH, a domestic wire transfer, or a supported person-to-person payment service. Processing times, costs, and protections vary, so the fastest option isn’t always the most practical one.

    This guide walks you through the process, explains the differences between common transfer methods, and shows you how to reduce avoidable mistakes. For more background, visit our guide to bank transfers and payment methods.

    What You’ll Learn

    • How to initiate a transfer between two different banks.
    • When to use ACH transfers, wire transfers, or payment apps.
    • How transfer fees, limits, and delivery times can differ.
    • Which account details you may need before getting started.
    • How to avoid common errors and reduce transfer-related risks.

    Quick Answer

    What Is the Best Way to Transfer Money Between Banks?

    For routine transfers between your own U.S. bank accounts, an external bank transfer using ACH is often a cost-effective choice, and many banks offer it without a fee. Transfers commonly take one to three business days, but timing varies. A domestic wire transfer may suit urgent or large payments when the receiving bank can process it promptly and the fees are acceptable. For sending money to another person, an eligible payment app may be convenient. Before choosing, compare fees, transfer limits, delivery estimates, and available protections.

    Key Takeaways

    • Compare fees: Check whether the sending or receiving bank charges for the transfer.
    • Plan around timing: Weekends, holidays, bank cutoff times, and verification checks can delay delivery.
    • Verify account details: Double-check the recipient’s routing number and account number before submitting the transfer.
    • Check limits: Confirm your bank’s daily or per-transfer limits, especially for large amounts.
    • Stay alert: Use official banking channels and independently verify unexpected requests to send money.

    Table of Contents

    Use the links below to explore bank transfer methods, compare costs and timing, and learn how to move money between accounts safely.

    1. Article Title and Author
    2. Introduction: How to Transfer Money From One Bank to Another
    3. Quick Answer
    4. Table of Contents
    5. Bank Transfer Methods at a Glance
    6. A Beginner’s Guide to Bank Transfers
    7. How to Transfer Money Step by Step
    8. Benefits and Drawbacks
    9. ACH vs. Wire Transfers vs. Payment Apps
    10. Transfer Fees, Risks, and Expert Tips
    11. Common Mistakes and How to Avoid Them
    12. Who Should Choose Each Transfer Method?
    13. Frequently Asked Questions
    14. Final Verdict
    15. Related Resources and Further Reading
    16. Contact FinanceInvestment

    Bank Transfer Methods at a Glance

    If you’re deciding how to transfer money from one bank to another, compare the available methods before you send it. The right choice depends on how quickly the money must arrive, the amount you’re transferring, and the fees and limits set by your bank or payment service.

    Transfer MethodTypical TimingTypical CostBest Use
    External bank transfer (usually ACH)Often 1–3 business days; bank policies varyOften free, but check both banks’ termsMoving money between your own accounts
    Domestic wire transferMay arrive the same business day if submitted before the cutoff and processed in timeSending or receiving fees may applyUrgent payments or transactions requiring a wire
    Real-time bank paymentCan be completed within seconds when both banks and accounts are eligibleDepends on the payment network and bankEligible payments where speed is important
    Person-to-person payment appMay be quick within the service; moving funds to a bank can take longerVaries by app, payment source, and withdrawal speedSending money to another person through a supported service

    Important: Timing and fees are general estimates, not guarantees. Weekends, federal holidays, bank cutoff times, transfer limits, account verification, and fraud checks can affect processing. Real-time payment availability depends on the specific network and participating institutions.

    Quick Take

    For routine transfers between your own accounts, check whether an ACH transfer is available and free. If you need the money to arrive sooner, ask your bank about wire or real-time payment options, confirm eligibility and limits, and compare the total cost before proceeding.

    A Beginner’s Guide to Bank Transfershow to transfer money from one bank to another

    An external bank transfer moves money between accounts held at different financial institutions. In the United States, many banks process these transfers through the Automated Clearing House (ACH) network. To get started, sign in to your bank’s official website or mobile app, choose the external transfer option, and follow the instructions to link the receiving account. Available options and processing times vary by bank.

    Understanding Routing and Account Numbers

    A routing number identifies a financial institution for a particular transaction type, while an account number identifies the specific bank account. You may need both to set up a transfer. Do not assume the routing number printed on a check is suitable for every transaction; confirm the correct details with your bank. Read our guide on how to find your checking account routing number.

    Verifying the External Bank Account

    Before allowing transfers, your bank may require you to verify ownership of the external account. Depending on the institution, verification may use a secure connection, login-based verification, small test deposits called micro-deposits, or another approved process. Complete the steps through your bank’s official channel and allow extra time if verification is required.

    Beginner tip: Before confirming a transfer, check the receiving account details, amount, fees, and estimated delivery date. Never share your banking password or one-time verification code with someone who contacts you unexpectedly. If anything looks unfamiliar, contact your bank using its verified phone number or official app.

    How to Transfer Money From One Bank to Another: Step by Step

    Most transfers between U.S. bank accounts can be started online or through a mobile banking app. The exact process depends on your bank and the transfer method, but these steps can help you prepare and avoid common errors.

    1. Sign in to your bank.
      Use the bank’s official website or mobile app and look for “Transfers,” “External Transfers,” or a similar option.
    2. Add the receiving account.
      Enter the requested details, which may include the bank routing number and account number. Follow the bank’s instructions to verify account ownership, if required.
    3. Choose the accounts and amount.
      Select the sending and receiving accounts, enter the amount, and choose a transfer date or frequency if scheduling is available.
    4. Review the transfer carefully.
      Confirm the account details, amount, fees, transfer limits, and estimated delivery date. Correct any errors before authorizing the transaction.
    5. Authorize and save confirmation.
      Complete any required security checks and submit the transfer. Save the confirmation number or receipt for future reference.
    6. Track the status and verify delivery.
      Check your bank’s transfer history for updates. Once the transfer is expected to arrive, confirm that the receiving account shows the funds. If the transfer is delayed or the status is unclear, contact your bank through an official channel.

    Important: A confirmation screen only shows that the request was submitted or accepted for processing; it does not always mean the money has arrived. Keep your receipt until the transfer is complete, and never share your banking password or one-time security code with someone who contacts you unexpectedly.

    Benefits and Drawbacks of Bank Transfers

    Bank transfers can make everyday money management easier, especially when you need to move funds between accounts at different banks. However, costs, delivery times, and payment protections vary depending on the method and the institutions involved.

    Benefits

    • Transfer money online without visiting a bank branch.
    • Use ACH transfers that may be free or inexpensive, depending on your bank.
    • Move funds between personal accounts and manage bills or savings more conveniently.
    • Review transaction records to help track deposits and payments.

    Drawbacks

    • Standard transfers may take several business days.
    • Wire transfers and expedited services may carry fees.
    • Banks can impose transfer limits, verification steps, or processing holds.
    • Incorrect account details and fraudulent payment requests can lead to financial loss.

    How to Choose the Right Method

    For routine transfers between your own accounts, compare ACH options and their fees. If the payment is urgent, ask your bank about wire transfers or eligible real-time payment services. Check the delivery estimate, transfer limits, and total cost before sending money, and verify the receiving account details carefully.

    ACH vs. Wire Transfers vs. Payment Apps

    In the United States, ACH transfers, wire transfers, and payment apps serve different needs. ACH is commonly used for routine bank payments, wires can suit urgent or high-value transactions, and payment apps are often convenient for eligible person-to-person payments. Compare their typical timing, costs, and requirements before deciding.

    FeatureACH TransferWire TransferPayment Apps
    Typical speedOften 1–3 business days; timing variesMay arrive the same business day if processed before the cutoffMay be quick within the service; bank withdrawals can take longer
    Typical costOften free, but fees may applySending or receiving fees may applyDepends on the app, payment source, and withdrawal speed
    Best useRoutine transfers and eligible bill paymentsUrgent or wire-required paymentsEligible payments between individuals
    Before sendingCheck transfer limits, processing time, and account detailsConfirm recipient details, cutoff time, and total feesVerify the recipient, payment limits, and withdrawal terms

    These are general estimates, not guarantees. Actual delivery times and fees depend on your bank, payment service, transaction details, processing schedule, and any required verification.

    Which Option Should You Choose?

    For routine transfers between your own bank accounts, compare the bank’s ACH options first. If timing is critical, ask about wire transfers or eligible real-time bank payments. Use a payment app when it suits the recipient and payment type. Before confirming any transaction, check the total cost, delivery estimate, limits, and recipient details.

    Transfer Fees, Risks, and Expert Tips

    Before moving money between banks, check more than the advertised transfer fee. Processing delays, account restrictions, and incorrect payment details can cause complications or unexpected costs. Reviewing the terms and recipient information before authorizing a transfer can help you avoid preventable problems.

    Fees and Costs to Check

    • Wire transfer fees: The sending bank may charge a fee, and the receiving bank may charge one too.
    • Faster delivery: Expedited services may cost more than standard transfers.
    • Returned payments or overdrafts: A rejected transaction or insufficient balance may lead to additional charges, depending on your account terms.
    • Payment app fees: Fees may apply based on the funding source, payment type, or withdrawal speed.

    How to Reduce Transfer Risks

    • Verify account details: Confirm the recipient’s name and the correct routing and account numbers before sending.
    • Watch for payment scams: Independently confirm unexpected requests to change bank details or send money, especially requests that create urgency.
    • Secure your account: Use your bank’s official website or app. Never share your password or one-time security code with someone who contacts you unexpectedly.
    • Keep transaction records: Save the confirmation number and monitor the transfer until its status is clear.

    Expert Tip: Act Quickly if Something Goes Wrong

    If you notice an unfamiliar transaction, enter incorrect transfer details, or suspect a scam, contact your bank or payment provider immediately through an official channel. Ask whether the payment can be stopped, recalled, or investigated. Recovery is not guaranteed, particularly after certain payments have been completed, so do not delay reporting the problem.

    Common Mistakes and How to Avoid Them

    A small mistake can delay a bank transfer or create extra work. Before sending money, check these common problems and how to prevent them.

    1. Entering Incorrect Account Details

    An incorrect routing or account number may cause a transfer to be rejected, delayed, or sent to an unintended account. Verify the details with the receiving bank or account holder before authorizing the payment.

    2. Underestimating Transfer Time

    An ACH transfer started on Friday may not arrive immediately. Weekends, federal holidays, cutoff times, and bank processing schedules can affect delivery. Check the estimated arrival date and allow extra time for bills or other deadlines.

    3. Submitting a Duplicate Transfer

    If a payment remains pending, sending it again could result in two transfers. Check your transaction history and confirmation number first. If the status is unclear, contact your bank before retrying.

    4. Trusting Unexpected Payment Instructions

    A scammer may impersonate a vendor, family member, or bank employee and request an urgent payment or new account details. Independently verify the request using a trusted phone number or previously confirmed contact method.

    If something goes wrong: Contact your bank or payment provider promptly if you notice an incorrect transfer, duplicate payment, or suspected scam. Ask whether the transaction can be stopped, recalled, or investigated. Recovery is not guaranteed, so report the problem as soon as possible.

    Who Should Choose Each Transfer Method?

    Choose your transfer method based on the recipient, urgency, cost, and your bank’s requirements.

    Routine Transfers Between Your Own Accounts

    Consider ACH: Often a practical, low-cost option when you can wait for processing. Check fees, limits, and the estimated arrival date.

    Urgent or Wire-Required Payments

    Consider a wire: It may suit time-sensitive transactions, but confirm the recipient’s requirements, cutoff time, fees, and expected delivery before sending.

    Payments to Friends or Family

    Consider a supported payment app: It can be convenient for eligible person-to-person payments. Verify the recipient and review the app’s limits, fees, and protections.

    Practical rule: Compare total cost, delivery time, eligibility, and available protections. Never choose a method based on speed alone.

    Frequently Asked Questions

    1. How long does it take to transfer money between banks?

    Many ACH transfers take one to three business days, although timing varies by bank. Domestic wires may arrive the same business day if processed before the cutoff. Verification, weekends, and holidays can affect delivery.

    2. Is transferring money between banks free?

    Some banks offer standard ACH transfers at no charge. Wire transfers and expedited services may cost extra. Check the fees charged by both banks and any applicable service before confirming.

    3. What information do I need for a bank transfer?

    Depending on the method, you may need the recipient’s name, routing number, account number, and transfer amount. Follow your bank’s instructions and confirm the details before authorizing the payment.

    4. Can I transfer money between banks online?

    Yes. Many U.S. banks support transfers through online banking or mobile apps. You may need to add the receiving account and complete verification before sending money.

    5. Are there limits on bank transfers?

    Yes, banks may set per-transfer, daily, or other limits. The amount you can send depends on your account, transfer method, and bank policies. Ask your bank about limits before making a large payment.

    6. Why is my bank transfer delayed?

    Common reasons include weekends, holidays, cutoff times, account verification, security reviews, or incorrect details. Check the transaction status and contact your bank if the delay exceeds its estimate.

    7. Can I cancel a bank transfer after submitting it?

    Sometimes. A scheduled transfer may be cancellable before processing, but a transfer already sent may be difficult or impossible to reverse. Contact your bank immediately to ask about available options.

    8. How can I transfer money safely?

    Use your bank’s official website or app, verify recipient details, and review fees before sending. Independently confirm unexpected payment requests, never share security codes, and report suspected fraud to your bank promptly.

    Final Verdict: Choose the Right Way to Transfer Money

    For routine transfers between your own U.S. bank accounts, an ACH transfer is often a practical, low-cost starting point. If a payment is urgent or the recipient requires a wire, compare the available options, fees, cutoff times, and delivery estimates before sending. Payment apps can be convenient for eligible transfers to friends and family, but check their limits and protections.

    Before confirming any transfer, verify the recipient’s details and use your bank’s official website or app. Keep the confirmation and check that the money arrives. The best method is the one that fits your timing, budget, and security needs.

    Need more guidance? Read our
    complete guide to bank transfers and payment methods
    to explore your options.

    Have Questions About Bank Transfers?

    Have feedback or a suggestion for this guide? Email FinanceInvestment at

    For pending, delayed, or incorrect transfers, contact your bank directly.

    Explore More Banking Guides

    Learn more in our guide to
    bank transfers and payment methods
    or review our
    bank account security checklist
    for practical account-protection tips.
  • Who Should Join a Credit Union? Eligibility Guide (2026)

    Who Should Join a Credit Union? Eligibility Guide (2026)

    Who Should Join a Credit Union? Find Out If Membership Is Right for You

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Updated: October 11, 2026
    Reading time: 11–12 minutes
    MEMBER GUIDE

    who should join a credit unionWho should join a credit union? It may be a good choice if you qualify for membership and want to compare savings options, everyday banking services, or loan terms with those offered by other financial institutions. The right fit depends on your needs, not just the institution’s name.

    Credit unions are member-owned financial cooperatives. Many offer checking accounts, savings accounts, certificates, and loans. Some provide competitive rates or lower fees, but these benefits vary by institution. You must also meet the credit union’s membership eligibility rules before opening an account.

    Depending on the credit union, you may qualify through your location, employer, an eligible organization, or a family connection. Before joining, compare account fees, ATM and branch access, mobile banking, loan terms, and applicable federal share insurance coverage.

    Not sure how credit unions work? Start with our complete guide to credit unions. Then use this article to see whether membership makes sense for your circumstances.

    What You’ll Learn

    • Who may qualify for credit union membership.
    • Which people and households may benefit most.
    • How credit unions compare with banks.
    • What to review before opening an account.
    • When a bank or another financial institution may suit you better.

    Quick Answer: Who Should Join a Credit Union?

    A credit union may be worth considering if you qualify for membership and want to compare checking accounts, savings options, or loans with those offered by banks. It may appeal to people who value member-focused service or convenient local banking. However, benefits, rates, fees, and access vary by institution.

    Key Takeaways

    • Check eligibility first. Each credit union has its own membership requirements.
    • Compare account terms. Review fees, interest rates, loan costs, and features.
    • Consider everyday access. Check ATM networks, branch locations, and mobile banking tools.
    • Verify federal share insurance. Confirm whether the credit union is federally insured and review the applicable coverage limits.
    • Compare alternatives. A bank may be a better fit if it offers the services and convenience you need.

    Bottom line: Choose a credit union after checking eligibility, costs, convenience, and applicable account protections—not simply because it advertises lower fees.

    Table of Contents

    Jump to the section you need to understand credit union eligibility, compare your options, and decide whether membership fits your financial needs.

    Credit Unions at a Glance

    A credit union may be a good fit if its membership rules, account features, and service options match your needs. Use this quick comparison to identify what deserves a closer look before you apply.

    FactorWhat to Know
    Membership eligibilityYou must meet the institution’s membership requirements.
    Rates and feesCompare savings yields, account charges, and loan terms.
    Everyday accessReview ATM networks, branch locations, mobile banking, and support hours.
    Share insuranceVerify federal insurance status and applicable coverage limits.
    OwnershipCredit unions are member-owned financial cooperatives.

    QUICK TAKE

    Consider joining when you qualify and the credit union offers the right mix of cost, convenience, and services. Compare actual account terms before deciding because membership does not guarantee lower fees, better rates, or easier access.

    Credit Union Membership: A Beginner’s Guidewho should join a credit union

    Before choosing a credit union, understand how membership works. Unlike many banks, credit unions generally serve people who meet specific eligibility requirements. These rules are often called the credit union’s field of membership.

    Common Ways to Qualify

    • Location: You live, work, worship, or attend school in an eligible area, where permitted by the credit union’s rules.
    • Employment or organization: Your employer, profession, or an eligible association connects you to the institution.
    • Family connection: A qualifying relative is already a member, if the credit union allows family-based eligibility.

    What Happens When You Apply?

    Start by checking the credit union’s eligibility page. If you qualify, review its account fees, minimum opening deposit, identification requirements, and any membership share or savings-account rules. These details vary by institution.

    Remember, qualifying for membership does not guarantee approval for every loan or financial product. If you need help comparing options, read our complete credit union guide before making your decision.

    Beginner tip: Confirm eligibility directly with the credit union before submitting an application or paying any membership-related deposit.

    How Credit Union Membership Works

    Joining a credit union generally starts with checking whether you qualify. If you meet its membership rules, you can review the available accounts, understand the costs, and apply. The exact process depends on the institution.

    Four Steps to Become a Member

    1. Confirm eligibility. Check the credit union’s field of membership and make sure your location, employment, family connection, or another qualifying factor meets its rules.
    2. Gather required information. Depending on the application, you may need identification, personal details, and documents confirming eligibility.
    3. Apply and meet opening requirements. Some credit unions require an opening deposit or a small share deposit to establish membership.
    4. Set up your account. Review fees and account terms, activate digital banking if available, and learn how to access your money.

    What Does Member-Owned Mean?

    Credit unions are member-owned financial cooperatives. Members generally have voting rights under the institution’s governing rules, including a role in electing the board of directors. However, voting procedures and participation can vary, and membership does not guarantee better rates or service.

    Remember: Membership eligibility is separate from approval for a loan or credit card. Lenders still evaluate applications under their own requirements.

    Benefits and Potential Drawbacks of Joining a Credit Union

    A credit union may be a practical alternative to a bank, but the experience depends on the institution and the products you use. Consider both the potential benefits and the limitations before deciding whether membership suits you.

    Potential Benefits

    • Competitive account terms: Some credit unions offer attractive savings rates, loan rates, or lower fees.
    • Personal service: Some emphasize local relationships and direct member support.
    • Member ownership: Eligible members generally have voting rights under the credit union’s governing rules.
    • Everyday banking: Many provide checking, savings, certificates, and lending products.

    Potential Drawbacks

    • Membership restrictions: You must meet the institution’s eligibility requirements.
    • Limited branch access: Some have fewer branches or locations than large banks.
    • Different digital features: Apps, online services, and support hours vary.
    • Account conditions: Fees, minimum balances, and transaction rules may still apply.

    A smaller branch network does not always mean limited access. Some credit unions participate in shared branching or ATM networks, but participation, fees, and available services vary. Confirm the details before relying on these options.

    Check account protection, too. Eligible deposits at federally insured credit unions are generally insured by the NCUA up to applicable limits and subject to its rules. Verify the institution’s insurance status and understand which accounts and balances qualify.

    Practical takeaway: Compare a specific credit union with a bank using similar account types, balances, fees, access needs, and applicable insurance protections. Choose the option that fits your financial routine—not a general claim about either institution.

    Credit Union vs. Bank: Which Is Better for You?

    Credit unions and banks both provide checking accounts, savings products, and loans. Their ownership structures differ, but your day-to-day experience depends on the institution you choose. Compare the actual account terms and services instead of assuming one option is always better.

    FactorCredit UnionBank
    OwnershipMember-owned financial cooperativeMay be shareholder-owned or privately owned
    EligibilityMembership eligibility rules generally applyApplicants must meet the bank’s account-opening requirements
    Rates and feesDepend on the institution, account, and applicable conditionsDepend on the institution, account, and applicable conditions
    Branch and ATM accessMay include local branches, shared branching, or participating ATM networksMay include extensive branch and ATM networks, depending on the bank
    Federal deposit protectionNCUA share insurance at federally insured credit unions, subject to coverage rules and limitsFDIC deposit insurance at insured banks, subject to coverage rules and limits

    Want a deeper comparison? Read our guide to credit unions vs. banks before deciding where to open an account.

    How to decide: Compare similar accounts by fees, interest rates, minimum balance rules, digital banking, customer support, and access to cash. Also verify the institution’s insurance status. Choose the option that best supports your financial routine.

    Costs, Risks, and Practical Tips Before Joining

    A credit union can be a useful banking option, but membership does not guarantee free accounts, convenient access, or better rates. Review the terms of the specific institution before opening an account.

    Costs and Details to Check

    • Account fees: Check monthly maintenance charges, overdraft fees, and out-of-network ATM fees.
    • Opening requirements: Confirm the minimum opening deposit, any required share deposit, and ongoing balance rules.
    • Access and transfers: Review branch availability, ATM networks, transfer limits, and mobile banking features.
    • Share insurance: Verify federal insurance status and applicable NCUA coverage rules and limits.

    How to Make an Informed Choice

    Read the account agreement and current fee schedule before applying. If you plan to borrow, compare the annual percentage rate (APR), repayment period, fees, and total borrowing cost. A lower advertised monthly payment does not necessarily mean a loan costs less overall.

    Also consider how you normally manage money. A credit union with attractive account terms may still be inconvenient if its ATM network, digital tools, or support hours do not meet your needs.

    Practical tip: Review our guide to how to avoid credit union fees, then confirm the current terms directly with the institution.

    Common Mistakes to Avoid Before Joining a Credit Union

    • Assuming you qualify: Check the credit union’s membership requirements before applying.
    • Chasing one attractive rate: Compare fees, minimum balance rules, and the account’s full terms.
    • Overlooking convenience: Check ATM access, branch availability, digital banking, and support hours.
    • Skipping insurance verification: Confirm federal share insurance status and understand the applicable coverage limits.

    A Practical Example

    Imagine Alex finds a credit union advertising a competitive savings rate. Before opening an account, Alex confirms eligibility, checks the minimum balance and fees, reviews ATM access, and verifies federal share insurance. Alex then compares the offer with a bank account, paying attention to the rate, account conditions, and convenience.

    The credit union may still be the better choice, but Alex now has enough information to compare the options fairly. If the account requires a balance Alex cannot maintain or makes everyday access difficult, another institution may be more suitable.

    Key lesson: Choose based on eligibility, total costs, account protection, and convenience—not just an advertised rate.

    Who Should Choose a Credit Union?

    A credit union may be a good fit if you meet its membership requirements and its accounts, costs, and services match your needs. Instead of choosing based on reputation alone, consider how you save, spend, borrow, and access your money.

    A Credit Union May Suit You If You:

    • Meet its eligibility rules through an approved location, employer, family connection, or another qualifying route.
    • Find account fees, savings rates, or loan terms that compare favorably with alternatives.
    • Value the service offered by that particular institution.
    • Can conveniently use its branches, ATM network, and digital banking services.

    When a Bank May Be a Better Fit

    A bank may suit you better if its branch network, account features, digital tools, or financial products better match your routine. A credit union may also be less practical if you do not qualify or its fees and access arrangements do not meet your needs.

    Decision rule: Choose the specific institution that offers the best overall fit for your eligibility, costs, account protection, and everyday access—not simply the one with the most appealing label.

    Frequently Asked Questions

    1. Who should join a credit union?

    People who qualify for membership and find suitable account terms, services, and access may benefit. Compare the specific credit union with other financial institutions before deciding.

    2. Can anyone join a credit union?

    Not always. Credit unions generally have membership eligibility rules based on factors such as location, employment, family connections, or qualifying organizations.

    3. Are credit unions better than banks?

    Neither is automatically better. Compare fees, interest rates, loan terms, digital features, branch access, and customer service to find the better fit for your needs.

    4. Do credit unions charge membership fees?

    Requirements vary. Some credit unions require a small share deposit or opening deposit. Account maintenance and other service fees depend on the institution and account terms.

    5. Are credit union deposits federally insured?

    Eligible share deposits at federally insured credit unions are generally protected by NCUA insurance, subject to ownership rules and coverage limits. Confirm the institution’s insurance status before depositing money.

    6. Does credit union membership guarantee loan approval?

    No. Membership may let you apply, but approval depends on the lender’s criteria, credit history, income, and other relevant factors.

    7. Can I keep my bank account and join a credit union?

    Yes. You can generally hold accounts at both institutions if you meet their requirements. Compare account terms and fees before moving money or closing an existing account.

    8. What should I check before joining a credit union?

    Confirm membership eligibility, account fees, minimum balance rules, ATM access, digital banking features, and federal share insurance status before applying.

    Final Verdict: Should You Join a Credit Union?

    A credit union is worth considering when you qualify for membership and its accounts, costs, and services fit the way you manage money. Member ownership and personal service may appeal to you, but neither guarantees lower fees, better rates, or a better banking experience.

    Before deciding, compare account terms, minimum balance requirements, ATM access, digital banking, and applicable federal share insurance. A bank may be the better fit if it offers more convenient access or features you use regularly. You can also keep accounts at both types of institutions if that suits your needs.

    Want to explore the basics before making a decision? Read our complete guide to credit unions for more information about how they work, the accounts they offer, and what to consider before joining.

    Have a Money Question? Keep Exploring.

    Choosing where to bank starts with knowing your options. Compare membership eligibility, account costs, insurance protection, and everyday convenience before deciding which institution fits your needs.

    Contact FinanceInvestment

    Have a question or suggestion for a future personal finance guide? Get in touch by email.

    Email FinanceInvestment

    Continue Your Research

  • Credit Union Pros and Cons: Benefits and Drawbacks (2026)

    Credit Union Pros and Cons: Benefits and Drawbacks (2026)

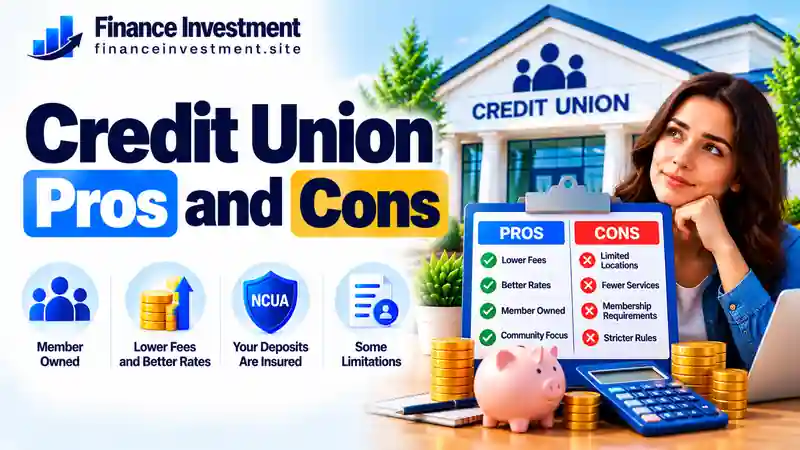
    Credit Union Pros and Cons: What to Know Before Joining

    Subhash Rukade
    Founder, FinanceInvestment
    Consumer Banking · Credit Union Guides
    LAST UPDATED
    October 11, 2026
    READING TIME
    About 10 minutes

    Credit Union Pros and Cons: Is Joining Worth It?credit union pros and cons

    Choosing where to keep your money is a personal decision. Understanding the credit union pros and cons can help you decide whether one is a better fit for your savings, everyday banking, or borrowing needs.

    Credit unions are member-owned financial institutions. Depending on the institution, members may find competitive savings rates, lower fees, or more personal service. There can be trade-offs, too. Membership rules, branch locations, ATM access, digital tools, and available financial products vary from one credit union to another.

    Before joining, compare the details that affect your daily finances: account fees, minimum balance requirements, savings yields, loan terms, customer support, and mobile banking features. Also verify whether the credit union is federally insured by the National Credit Union Administration (NCUA). Federal share insurance protects eligible deposits if an insured institution fails, subject to coverage rules and limits; it does not cover every possible financial loss.

    New to credit unions? Read our complete guide to credit unions to understand membership, accounts, and how these institutions operate.

    What You’ll Learn

    • The main advantages and disadvantages of joining a credit union.
    • How savings rates, loan terms, and account fees can differ.
    • What to compare when choosing between a credit union and a bank.
    • How membership eligibility, ATM access, branches, and mobile banking affect convenience.
    • How to verify federal share insurance and decide whether a credit union fits your needs.

    Credit Union Pros and Cons: The Quick Answer

    Quick answer: A credit union may suit you if you want competitive savings rates, reasonable fees, and member-focused service. Possible drawbacks include membership requirements, fewer nearby branches, limited product choices, or less convenient ATM access. The actual benefits depend on the institution and your banking habits.

    Key Takeaways

    • Competitive rates may be available: Compare current savings yields and loan APRs rather than assuming every credit union offers the best deal.
    • Fees depend on the account: Review monthly charges, minimum balance rules, overdraft policies, and ATM fees.
    • Eligibility can matter: Some credit unions restrict membership based on location, employment, family relationships, or other criteria.
    • Access varies: Check branch locations, ATM networks, shared branching, and mobile banking features.
    • Services differ: A smaller institution may not offer every product or digital feature you want.
    • Verify deposit insurance: Confirm whether the credit union is federally insured by the NCUA and understand applicable coverage limits.

    Bottom line: Compare the actual costs, rates, account features, convenience, and deposit protection before joining. A credit union is worth considering when its services fit your needs better than the alternatives.

    Table of Contents

    Credit Union Pros and Cons at a Glance

    Credit unions can be a good fit for some households, but the benefits depend on the institution and the account. This overview highlights the main points to compare before you join.

    POTENTIAL ADVANTAGE

    Some institutions offer competitive savings yields, loan terms, or account fees.

    POSSIBLE TRADE-OFF

    Membership eligibility, fewer nearby branches, or a narrower product selection may be drawbacks.

    BEST FIRST STEP

    Compare fees, rates, ATM access, digital features, and deposit insurance.

    Credit Union Quick Comparison

    FeaturePotential benefitWhat to check
    Savings and loansCompetitive rates may be availableCurrent APY, loan APR, and terms
    FeesSome accounts may have lower costsMonthly, overdraft, and ATM charges
    AccessLocal service or shared branching may helpBranches, ATM network, and app features
    MembershipMember ownership and participationEligibility rules and any membership requirements
    Deposit protectionFederal share insurance at eligible institutionsInsurance status, ownership category, and coverage limits

    QUICK TAKE: Compare the actual account terms rather than assuming every credit union offers lower fees or better rates. The best choice is the one that fits your financial needs and everyday banking habits.

    A Beginner’s Guide to Credit Unionscredit union pros and cons

    A credit union is a member-owned financial institution. Like a bank, it may offer checking and savings accounts, debit cards, and loans. Its ownership model and membership rules are different, while the exact products and services depend on the institution.

    How Does Credit Union Membership Work?

    Eligibility may be based on where you live, where you work, an organization you belong to, or a family connection. Some credit unions ask new members to open a share savings account with a small deposit. Requirements and minimum amounts vary, so check the membership rules before applying.

    That deposit may represent your ownership share in the credit union. It is not necessarily a separate membership fee, and withdrawal rules may apply while you remain a member. Review the account terms to understand what you must keep in the account.

    Where Do the Pros and Cons Show Up?

    Depending on the institution, members may find competitive savings yields, appealing loan terms, lower fees, or personal service. Possible disadvantages include fewer branches, limited product options, or digital tools that do not suit your needs. A bank with a broad national network may be more convenient if you travel frequently.

    A Simple Example

    Suppose you need both a savings account and a car loan. Credit Union A offers a competitive savings APY and a suitable loan rate, but its branches are far away. Credit Union B has convenient digital services and a nearby branch, but charges a monthly account fee. Compare the total cost, access, and loan terms instead of choosing based on one feature alone.

    Beginner tip: Check membership eligibility, read the account disclosures and fee schedule, and verify the institution’s federal insurance status. The official MyCreditUnion.gov website offers consumer information about credit unions and share insurance.

    How Do Credit Unions Work?

    Credit unions are financial cooperatives owned by their members. After meeting the eligibility requirements and joining, you can use the accounts and services available at that institution. Members generally have voting rights under the credit union’s rules, which may include voting for board representatives. This gives eligible members a voice in how the cooperative is governed.

    How Do Deposits and Loans Work?

    Members may deposit money into checking, savings, and other eligible accounts. The credit union manages these funds alongside its other resources to support lending and daily operations. When members borrow money, they repay the loan with interest under the agreed terms. Eligible deposit accounts may earn interest or dividends, depending on the account and institution. Neither higher returns nor lower loan rates are guaranteed.

    How Can Members Access Their Money?

    Available options may include branches, ATMs, online banking, mobile apps, and shared branching. Access differs by credit union, and some networks may charge fees or have usage restrictions. Before joining, check whether the institution offers the locations, digital tools, and account services you need. You can also explore our guide to how credit union mobile banking works to understand the digital side of membership.

    What this means for you: Member ownership can offer a say in governance, but it does not automatically mean lower fees, higher savings returns, or loan approval. Compare account disclosures, rates, fees, and access before choosing a credit union.

    Credit Union Benefits and Drawbacks

    Credit unions can work well for everyday banking, savings, and borrowing, but the experience depends on the institution. The right choice comes down to the rates, fees, services, and access you actually need.

    Potential Benefits of Credit Unions

    • Competitive rates: Some credit unions offer attractive savings yields or loan rates. Compare current offers because rates vary.
    • Potentially lower fees: Some accounts have modest maintenance fees or no monthly fee, but minimum-balance and transaction rules still matter.
    • Personal service: A local credit union may offer helpful in-person support and a community-focused approach.
    • Member participation: Eligible members generally have voting rights under the institution’s rules.

    Possible Drawbacks of Credit Unions

    • Membership restrictions: You may need to meet community, employment, family, or organizational eligibility rules.
    • Branch and ATM access: Nearby locations may be limited, and out-of-network ATM use may involve fees.
    • Fewer product options: Some credit unions offer fewer specialized accounts or financial services than larger banks.
    • Different digital features: App functionality, payment tools, support hours, and online services vary.

    Consider a borrower who finds a suitable auto loan at one credit union but would need to travel far to visit a branch. Another institution might offer convenient mobile banking but charge a fee for a service the borrower uses regularly. Reviewing the credit union fee structure can help reveal costs that are easy to overlook.

    The practical takeaway: Judge a credit union by its actual account terms, loan offers, service quality, and convenience—not by its name or ownership model alone.

    Credit Union vs. Bank: What Is the Difference?

    Credit unions and banks both offer financial services such as checking, savings, and loans. The main difference is ownership: credit unions are member-owned cooperatives, while banks may be privately owned or owned by shareholders. Their account terms, technology, and customer service can vary widely.

    Credit Union vs. Bank Comparison Table

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeMay be privately owned or shareholder-owned
    EligibilityMembership eligibility rules may applyApplicants must meet account-opening requirements
    Rates and feesMay offer competitive rates or lower feesRates and fees vary by institution and account
    Branches and technologyAccess depends on branches, networks, and digital toolsSome banks provide broad branch networks and extensive digital services
    Deposit protectionNCUA share insurance at federally insured credit unionsFDIC deposit insurance at FDIC-insured banks

    Which One Should You Choose?

    A credit union may suit you if its membership rules, rates, fees, and services match your needs. A bank may be more convenient if you need a broad branch network or particular financial products. Compare actual account terms instead of assuming one type of institution always offers a better deal.

    For more details, read our guide to credit unions vs. banks.

    Comparison tip: At federally insured institutions, standard NCUA share insurance and FDIC deposit insurance generally cover up to $250,000 per depositor or member, per insured institution, per ownership category. Coverage depends on account ownership and applicable rules, so verify your situation with the relevant insurer.

    Credit Union Costs, Risks, and Expert Tips

    A credit union may offer good value, but advertised rates alone do not show the full cost of an account. Review the fee schedule, withdrawal rules, and available services before deciding where to keep your money.

    Costs and Risks to Check

    • Account fees: Check monthly maintenance charges, minimum-balance requirements, overdraft fees, and wire-transfer costs.
    • ATM charges: Out-of-network withdrawals may involve fees from the credit union, the ATM operator, or both.
    • Early withdrawal penalties: Share certificates and other term deposits may charge a penalty if you withdraw funds before maturity.
    • Access limitations: Limited branches, restricted support hours, or missing digital features may make routine banking less convenient.

    Expert Tips Before You Join

    1. Read the account disclosures and fee schedule, including minimum-balance and withdrawal rules.
    2. Compare savings APYs and loan APRs with offers from other financial institutions.
    3. Check ATM access, shared branching, mobile banking, and customer support hours.
    4. Confirm that the credit union is federally insured and review the applicable NCUA share-insurance limits and ownership rules.

    Before opening an account, review our guides to credit union fees and how to avoid unnecessary fees to identify charges that could affect your balance.

    Practical rule: Compare the total cost, convenience, and account terms—not just the advertised interest rate. A higher APY may not be the better deal if fees or access limitations outweigh the benefit.

    Common Credit Union Mistakes to Avoid

    A credit union may look appealing at first, but overlooking account conditions can lead to unexpected costs or inconvenient banking. Check these details before becoming a member.

    Five Mistakes Worth Avoiding

    1. Comparing APY alone: Check fees, minimum-balance requirements, eligibility conditions, and withdrawal restrictions alongside the advertised rate.
    2. Skipping the eligibility check: Confirm that you qualify for membership before starting an application.
    3. Forgetting ATM access: Review nearby ATM options, shared-branching availability, and possible out-of-network charges.
    4. Assuming every account is insured: Verify that the institution is federally insured and understand how NCUA share-insurance limits and ownership categories apply to your accounts.
    5. Ignoring everyday convenience: Check mobile banking, transfers, bill payments, customer support, and branch access before committing.

    A Practical Example

    Imagine a family chooses a savings account because its advertised APY looks attractive. After applying, they discover that the rate requires a balance they cannot comfortably maintain. Reviewing the account disclosures and fee schedule beforehand could have helped them compare alternatives more accurately.

    Before you apply: Confirm membership eligibility, compare account terms, review fees, test the available digital features, and verify federal insurance status. These checks can help you avoid an account that does not fit your needs.

    Who Should Join a Credit Union?

    A credit union may be a good fit if you qualify for membership and its accounts, rates, and services meet your needs. The best choice depends on how you bank, borrow, save, and access your money.

    Who May Benefit from Joining?

    • Fee-conscious savers: People comparing savings yields, maintenance fees, and minimum-balance requirements.
    • Local households: Families who value convenient nearby branches and in-person support.
    • Loan shoppers: Borrowers comparing auto loans, personal loans, or mortgages across multiple lenders.
    • Community-minded members: People who value participating in a member-owned financial cooperative.

    Who Might Prefer a Bank?

    A bank may be more convenient for people who need a broad branch network, particular business services, or specialized international banking features. However, some credit unions offer extensive digital services and a range of financial products, so compare individual institutions rather than relying on general assumptions.

    Decision tip: Confirm membership eligibility, compare rates and fees, and check branch, ATM, and digital access. Our guide to who can join a credit union explains common membership requirements.

    Frequently Asked Questions About Credit Union Pros and Cons

    These answers cover the most common questions about credit union membership, costs, safety, and everyday banking.

    1. What are the main pros and cons of credit unions?

    Potential benefits include competitive rates, reasonable fees, and member-focused service. Possible drawbacks include membership restrictions, fewer branches, or limited product and technology options. The actual experience depends on the credit union.

    2. Are credit unions safer than banks?

    Neither is automatically safer. Verify the institution’s insurance status and review its financial products carefully. NCUA share insurance protects eligible deposits at federally insured credit unions, while FDIC insurance protects eligible deposits at FDIC-insured banks, subject to applicable limits and rules.

    3. Do credit unions offer better interest rates?

    Some credit unions offer competitive savings APYs or loan APRs, but better rates are not guaranteed. Compare current rates, fees, eligibility conditions, and account requirements before choosing.

    4. Are credit union accounts insured by the NCUA?

    Eligible share accounts at federally insured credit unions are generally protected by NCUA share insurance. The standard limit is generally $250,000 per member, per federally insured credit union, per ownership category. Coverage depends on account ownership and applicable rules, so verify your situation before depositing money.

    5. What are the disadvantages of joining a credit union?

    Possible disadvantages include membership requirements, fewer convenient branches, limited specialized products, or digital services that may not meet your needs. Some accounts also have monthly fees, minimum-balance rules, or transaction charges.

    6. Can anyone join a credit union?

    Not always. Eligibility may depend on where you live, your employer, an organization you belong to, or another membership rule. Check the credit union’s requirements before applying.

    7. Are credit unions better for loans?

    A credit union may offer a competitive loan, but the best option depends on the APR, fees, repayment term, eligibility, and total borrowing cost. Compare written offers from multiple lenders before deciding.

    8. Can I use other ATMs or credit union branches?

    Possibly. Access depends on the credit union’s ATM network, shared-branching participation, and account rules. Check participating locations, transaction limits, and possible fees before relying on another institution’s ATM or branch.

    Final Verdict: Are Credit Unions Worth It?

    Credit unions are worth considering if their rates, fees, services, and membership requirements fit your financial needs. Member-focused service and competitive account terms can be attractive, but neither is guaranteed. Limited branch access or missing digital features may also make a particular institution less convenient.

    Before joining, compare savings APYs, loan APRs, minimum-balance requirements, and the total fees you could pay. Check how easily you can access your money, and verify the institution’s federal insurance status and applicable coverage rules. These details matter more than choosing a credit union simply because it is member-owned.

    Continue your research: Explore our complete credit unions explained guide to learn more about membership, account types, services, and what to check before opening an account.

    Have a Money Question? Keep Exploring.

    Choosing where to bank starts with understanding your options. Compare membership requirements, account fees, savings rates, and everyday access before deciding whether a credit union fits your needs.

    Contact FinanceInvestment

    Have a question or a suggestion for a future personal finance guide? Send us an email.

    Email FinanceInvestment

    Continue Your Research

  • How Credit Union Mobile Banking Works: 2026 Guide

    How Credit Union Mobile Banking Works: 2026 Guide

    How Credit Union Mobile Banking Works

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 7, 2026
    Updated: October 7, 2026
    Reading Time: 12–14 minutes

    How Credit Union Mobile Banking WorksFor many credit union members, banking no longer means waiting for a branch to open. How Credit Union Mobile Banking Works comes down to using a secure smartphone app to handle everyday account tasks when it is convenient for you. Depending on the credit union, you may be able to view balances, check recent activity, move money, pay bills, deposit checks, and receive account alerts without making a branch visit.

    The important part is knowing what your particular credit union actually offers. Mobile features can differ by institution, and some services may have transaction limits, eligibility rules, fees, or processing times. Your app also does not replace everything a credit union provides. Branches, ATMs, shared networks, and member support can still play an important role in how you manage your money. If you are new to the credit union model, our credit union guide explains the bigger picture.

    What You’ll Learn

    • How a credit union mobile app connects you with your accounts.
    • What you can typically do from a smartphone.
    • How mobile deposits, transfers, payments, and alerts fit into everyday banking.
    • What fees, limits, and processing delays you should watch for.
    • How mobile access works alongside ATMs, branches, and other services.
    • Which security habits can help protect your account.

    Quick Answer: How Does Credit Union Mobile Banking Work?

    Credit union mobile banking connects your eligible credit union accounts to a smartphone app. Once you sign in, the app can give you access to everyday banking tasks such as checking account activity, moving money, paying bills, depositing eligible checks, and managing certain card settings. The exact tools, limits, and fees depend on the credit union.

    6 Key Takeaways

    1. It extends branch access: Many routine banking tasks can be completed from your phone instead of requiring a branch visit.
    2. The app connects to your existing accounts: Mobile banking normally works as a digital access point for eligible checking, savings, and other accounts.
    3. Not every feature is universal: Two credit unions can offer noticeably different apps, services, limits, and payment options.
    4. Some transactions take time: Transfers, deposits, and bill payments may have processing windows or cutoff times.
    5. Security remains your responsibility: Account credentials, device settings, authentication methods, and scam awareness all matter.
    6. The app should be judged with the whole account: Fees, ATM access, deposit options, customer support, and account terms can matter just as much as app quality.

    Bottom line: A credit union mobile app can make everyday banking considerably more convenient, but a polished app does not automatically make an account a good fit. Look at the complete banking experience—including access, costs, transaction rules, security, and support—before choosing a credit union.

    Table of Contents

    At a Glance: Credit Union Mobile Banking

    FactorQuick Summary
    What it isA smartphone-based way to access eligible credit union accounts and services.
    Typical accessA credit union mobile app, usually protected by account credentials and additional security controls.
    Best forMembers who prefer handling routine banking tasks from a smartphone.
    Key considerationCompare the app’s features with account fees, limits, deposit options, ATM access, and support.

    QUICK TAKE: Mobile banking is the digital access layer of your credit union account. It can make everyday banking more convenient, but the app should not be judged by features alone. A good fit also depends on how easily you can access cash, make deposits, get help, and manage the account within its rules and costs.

    Credit Union Mobile Banking: A Beginner GuideHow Credit Union Mobile Banking Works

    If you are new to credit union mobile banking, the easiest way to think about it is as a digital way to reach the accounts you already have. You typically do not create a separate account just for the app. Instead, your credit union connects eligible checking, savings, or other accounts to its mobile banking service.

    Getting Started

    1. Join the credit union and open an eligible account. Membership requirements vary between credit unions.
    2. Download the official app. Use the mobile application recommended by your credit union rather than an unfamiliar third-party app.
    3. Register or sign in. The setup may require your existing online-banking information and identity verification.
    4. Connect your preferred device settings. Depending on the service, you may be able to use biometric login, alerts, or other account-access options.
    5. Explore the app first. Locate your balances, transaction history, payments, transfers, deposits, statements, and help options before you need them.

    Beginner tip: Do not assume every credit union app works the same way. Before using a new feature, check the instructions, eligibility requirements, limits, and processing details shown by your credit union.

    How Credit Union Mobile Banking Works

    A credit union mobile app works as a digital connection to your eligible accounts. After you sign in, the app securely displays information provided by the credit union and lets you submit certain banking requests. The credit union’s systems then process those requests based on the account rules, transaction limits, and service schedules that apply to you.

    The Basic Mobile Banking Flow

    1. Sign in: You authenticate your identity through the credit union’s approved mobile service.
    2. Choose a service: You select an available function, such as viewing an account, transferring money, paying a bill, or depositing an eligible check.
    3. Review the request: The app may show the amount, destination, date, or other details before you submit it.
    4. Submit: The request is sent through the credit union’s digital banking system for processing.
    5. Check the status: The transaction may appear as completed, pending, or otherwise subject to processing before it is fully available.
    Common TaskTypical Mobile Action
    Account reviewCheck eligible balances, transactions, and account details.
    Money transferEnter the permitted accounts or destination and submit the transfer.
    Mobile depositFollow the app’s instructions to submit an eligible check deposit.
    Bill paymentSet up or schedule an eligible payment through the available bill-pay service.

    Key point: Mobile banking gives you a convenient way to send instructions to your credit union, but it does not guarantee that every transaction settles immediately. Cutoff times, account eligibility, transaction limits, verification, and funds-availability rules can affect the final result.

    Benefits & Drawbacks of Credit Union Mobile Banking

    A well-designed credit union app can remove friction from everyday banking. You can handle many routine tasks from wherever you are, which is especially useful when a branch is not nearby. However, mobile access has limits. The quality of the experience depends on the credit union’s app, account rules, service availability, and the other ways you can access your money.

    Benefits

    • Convenient access: Complete many routine banking tasks without traveling to a branch.
    • Quick account visibility: Review balances, transactions, and available alerts from your phone.
    • Remote check deposits: Eligible members may be able to submit checks without visiting a branch.
    • Digital self-service: Payments, transfers, statements, and other available tools can reduce routine calls or visits.

    Drawbacks

    • Different app experiences: Features and usability can vary significantly between credit unions.
    • Internet dependence: A poor connection, outage, or app problem can temporarily limit access.
    • Service restrictions: Certain transactions may have eligibility requirements, limits, cutoff times, or delays.
    • Not every problem is digital: Account disputes, complex requests, or some service needs may still require human assistance.

    Best perspective: Do not judge a credit union only by its mobile app. Consider how the digital service works alongside ATM access, branches, deposits, customer support, account rules, and the features you actually use. The strongest choice is the one that remains convenient when the app cannot handle what you need.

    Credit Union Mobile Banking Comparison

    Mobile banking is convenient, but it is not the only way to access a credit union account. Each channel has a different job. Comparing them helps you decide where a particular banking task makes the most sense.

    Access MethodBest ForMain AdvantageMain Limitation
    Mobile appRoutine banking on a smartphoneConvenient access while away from a branchFeatures depend on the credit union and app
    Online bankingAccount management from a computerLarger screen for detailed account tasksLess convenient when you are away from a computer
    ATMCash withdrawals and selected self-service tasksPhysical cash accessLimited compared with full digital banking
    BranchComplex needs and personal assistanceDirect help from credit union staffLocation and operating hours can limit access

    QUICK COMPARISON: For everyday tasks, the mobile app is often the most convenient option. However, ATM access remains useful for cash, online banking can be easier for detailed work, and branches matter when a request needs personal assistance. A strong credit union experience gives you more than one practical way to access your money.

    Costs, Risks & Expert Tips

    A credit union may provide its mobile app at no separate monthly cost, but other banking charges can still apply. Depending on the account and service, costs may involve certain transfers, ATM use, overdrafts, expedited services, or other transactions. The safest approach is to check the credit union’s current fee schedule and account disclosures before using a service.

    Mobile Banking Risks

    • Impersonation scams: Fake messages, websites, or apps can be designed to capture banking credentials.
    • Device exposure: A lost, stolen, or poorly protected phone can create additional account-security concerns.
    • Unsafe connections: Public or untrusted networks can create privacy and security risks.
    • Service interruptions: An outage, maintenance period, or technical problem can temporarily prevent digital access.

    Expert Tips for Safer Mobile Banking

    • Download the app through the official channel recommended by your credit union.
    • Use a strong, unique password and enable available multifactor authentication.
    • Keep your phone’s operating system and banking app updated.
    • Turn on useful transaction and account alerts so unusual activity is easier to spot.
    • Contact the credit union through a trusted phone number or website if something looks suspicious.

    If you want to understand the broader charges that may affect your account, see our guide to credit union fees.

    Common Credit Union Mobile Banking Mistakes

    Mobile banking is simple once you get familiar with it, but small oversights can cause unnecessary problems. The most common mistakes involve assuming every credit union app works the same way, overlooking account rules, or treating a digital confirmation as proof that everything is finished.

    Mistakes to Avoid

    • Assuming features are universal: Check whether your credit union actually supports the service you want to use.
    • Skipping the details: Review amounts, recipients, dates, and available instructions before confirming an important request.
    • Ignoring account rules: Check applicable limits, eligibility requirements, and processing information.
    • Relying only on the app: Know how to contact your credit union if a digital request needs additional help.

    Real-Life Example

    Imagine Maria opens her credit union app to deposit a check. She assumes the money will be available immediately because the app accepts the deposit. Before spending the funds, she checks the credit union’s instructions and availability information. She learns that submitting the check and having the funds available are separate steps. That quick check helps her avoid planning a payment around money she cannot yet use.

    The lesson: Convenience is the biggest strength of mobile banking, but a few seconds of review can help prevent avoidable mistakes.

    Who Should Choose Credit Union Mobile Banking?

    Credit union mobile banking makes the most sense when your everyday banking needs are simple enough to handle digitally and you value access from your smartphone. It can be especially useful if you regularly check transactions, manage eligible transfers, make payments, or use other services available through your credit union’s app.

    A Good Fit If You:

    • Prefer banking from your phone: You are comfortable handling routine account tasks without visiting a branch.
    • Want flexible account access: You often need to review or manage your accounts when you are away from a branch.
    • Use routine digital services: Your banking needs include features supported by the credit union’s mobile app.
    • Want backup support: You are comfortable using the app for routine needs but can contact the credit union when a request requires additional assistance.

    When it may not be ideal: If you strongly prefer face-to-face service, rarely use a smartphone, or regularly need services unavailable through the app, a branch or another access method may suit you better. The goal is not to choose the most digital option—it is to choose the access method that fits your banking habits.

    Frequently Asked Questions About Credit Union Mobile Banking

    1. How do I start using credit union mobile banking?

    You generally need an eligible credit union account and access to the institution’s mobile banking service. Registration may require your existing online-banking details or identity verification.

    2. Do I need a separate account for mobile banking?

    No separate bank account is normally created just for the app. Mobile banking generally provides digital access to eligible accounts you already have with the credit union.

    3. Can I deposit a check through a credit union mobile app?

    Many credit unions offer mobile check deposit for eligible members. Availability, deposit limits, endorsement requirements, and funds-availability rules can vary.

    4. Can I transfer money using credit union mobile banking?

    Yes, when the credit union supports the type of transfer you need. Available destinations, limits, verification requirements, and processing times depend on the service.

    5. Does credit union mobile banking cost money?

    Some credit unions do not charge a separate fee for mobile banking, but account, transaction, ATM, or other service fees may still apply. Check the current fee schedule for your account.

    6. How can I make credit union mobile banking safer?

    Use the official credit union app, protect your login credentials, keep your device and app updated, and enable available authentication and account-alert features.

    7. Can I use mobile banking when I cannot visit a branch?

    Yes. Supported mobile features can let you handle routine banking without a branch visit. However, some services may still require staff assistance or another access method.

    8. What should I do if my credit union mobile app stops working?

    Check your internet connection, confirm that the app and device software are updated, and try again later if the service is temporarily unavailable. If the issue continues, contact the credit union through an official support channel.

    Quick answer: Credit union mobile banking can handle many routine tasks, but the exact features, limits, fees, and availability depend on the credit union and the account.

    Final Verdict: Is Credit Union Mobile Banking Worth It?

    Credit union mobile banking is worth considering if the app supports the tasks you regularly handle and you are comfortable managing routine banking from your phone. It can reduce the need for branch visits while giving you a convenient way to review and manage eligible accounts.

    Still, the app should be only one part of your decision. Before choosing or relying on a credit union, compare the features you actually need with its account fees, transaction limits, deposit rules, ATM and branch access, and customer support. Those details can matter more than how polished the app looks.

    Bottom line: The best credit union mobile banking setup is not the one with the most features. It is the one that makes your routine banking easier while giving you reliable alternatives when a task cannot be completed through the app.

    Have a Money Question? Keep Exploring.

    Credit union mobile banking can make routine tasks easier, but the right setup depends on the features, costs, access, and support that fit your needs. Keep comparing the details before making an important banking decision.

    Have a question? Contact FinanceInvestment

    Continue Your Research

    Credit Union Fees Explained ·
    Credit Union ATM Networks Explained

  • How to Avoid Credit Union Fees: 2026 Guide to Saving More

    How to Avoid Credit Union Fees: 2026 Guide to Saving More

    How to Avoid Credit Union Fees: 2026 Guide to Saving More

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 5, 2026
    Updated: October 5, 2026
    Reading Time: 10–12 min

    How to Avoid Credit Union Fees Without Sacrificing ConvenienceHow to Avoid Credit Union Fees

    Knowing how to avoid credit union fees can make a noticeable difference in your everyday finances. A credit union account may have low or no routine charges, but certain actions can still trigger costs. Using an out-of-network ATM, overdrawing your account, ordering paper statements, or missing an account requirement can turn a low-cost account into an expensive one.

    The key is knowing which charges you can prevent before they happen. Simple habits such as using your credit union’s ATM network, keeping a small account cushion, setting up direct deposit when it helps waive a fee, and checking account requirements regularly can reduce unnecessary costs.

    If you’re still learning how credit unions work, our complete guide to credit unions explains the basics. This guide takes the next step by showing you where fees commonly appear and what you can do to keep them under control.

    What You’ll Learn

    • The credit union fees that members are most likely to encounter.
    • Practical ways to avoid monthly, ATM, overdraft, and NSF charges.
    • How to compare account requirements and fee policies before choosing an account.
    • Simple money habits that can help beginners, families, investors, and retirees reduce unnecessary banking costs.

    Quick Answer: How to Avoid Credit Union Fees

    To avoid credit union fees, choose an account that matches how you actually bank, understand its requirements, and prevent the transactions that can trigger charges. Before opening an account, check monthly fees, minimum-balance rules, ATM costs, overdraft policies, and other common charges. Once the account is open, use fee-free options and keep enough money available for upcoming payments.

    6 Key Takeaways

    1. Choose the right account. A low-fee account is only useful if its balance, deposit, and transaction requirements fit your routine.
    2. Know how fees can be waived. Some accounts may remove certain charges when you meet specific conditions.
    3. Use fee-friendly ATM options. Your credit union’s network or available fee-reimbursement options may help reduce ATM costs.
    4. Keep overdrafts under control. Track your available funds and understand whether overdraft protection is enabled.
    5. Prevent returned payments. Keeping enough money available before checks and electronic payments can help avoid NSF-related charges.
    6. Check charges periodically. Reviewing recent transactions can help you spot an unexpected fee and address the cause quickly.

    Table of Contents

    At a Glance: Credit Union Fees in 2026

    Credit union fees are not identical across institutions. The charges you face depend on the account, services you use, and the rules attached to your membership. A smart starting point is to focus on the costs most likely to affect everyday checking and savings activity.

    4Common fee areas covered below
    ATMNetwork rules can affect costs
    2Key payment-balance risks: overdraft and NSF
    1Fee policy to review before opening
    Fee AreaPossible TriggerPractical Prevention
    Monthly maintenanceNot meeting account-specific requirementsChoose an account whose requirements fit your normal balance and activity
    ATM feesUsing an ATM outside an available networkUse participating ATMs or check whether reimbursement is available
    Overdraft feesA covered transaction is paid despite insufficient available fundsMonitor available funds and understand your overdraft options
    NSF feesA payment or transaction is returned because funds are insufficientKeep sufficient funds available before scheduled payments

    QUICK TAKE: The exact fees depend on the credit union and account. Before opening an account, review the current fee disclosures, balance requirements, ATM rules, and overdraft policies. The goal is not simply to find an account with the fewest fees—it is to choose one whose rules match the way you actually manage your money.

    Complete Beginner Guide: How to Avoid Credit Union FeesHow to Avoid Credit Union Fees

    For beginners, avoiding credit union fees starts with one simple idea: choose an account whose rules fit the way you already manage your money. You do not need to eliminate every possible charge. Instead, focus on the fees you are most likely to encounter and build a few habits around them.

    1. Compare the Account Requirements

    Before opening an account, check its monthly maintenance fee, minimum balance requirement, direct-deposit conditions, transaction rules, and other charges. If a fee can be waived, make sure the waiver requirement is realistic for you.

    2. Plan Your ATM Use

    Find out which ATMs you can use without a credit union fee and whether the institution participates in a broader ATM network. Some accounts may also reimburse qualifying out-of-network charges. Check the current account terms before relying on that benefit.

    3. Reduce Overdraft and NSF Risk

    Keep enough money available for upcoming bills, checks, and debit transactions. Review your overdraft settings and understand whether your credit union offers options such as a linked savings account or another form of overdraft protection.

    4. Read the Fee Disclosure Before You Need It

    Keep a copy of the current fee information for your account and review it when your banking needs change. If you see a charge you did not expect, ask the credit union what triggered it and whether another account option could reduce the cost.

    How Credit Union Fee Avoidance Works

    Credit union fee avoidance is not about trying to eliminate every possible charge. It is about understanding which account rules affect you and making small changes before those rules turn into unnecessary costs. The process becomes easier when you connect each fee to the action or account condition that caused it.

    Start With the Cause

    Look at the account terms and your recent transactions together. A monthly charge may be tied to a balance or activity requirement. An ATM charge may come from using an ATM outside the available network. An overdraft or NSF charge can be connected to insufficient funds and the way a payment or transaction is handled.

    Choose the Lowest-Cost Response

    Once you know why a fee occurred, look for the simplest solution. You might meet an account requirement, use an eligible ATM, change an overdraft setting, or keep more money available before scheduled payments. The right choice depends on your credit union’s current terms.

    Recheck When Your Banking Habits Change

    Fee avoidance is not a one-time task. A new job, different income pattern, lower account balance, or greater need for cash withdrawals can change whether your current account still fits. Recheck the terms when your financial routine changes.

    Bottom line: The smartest approach is to understand the rules first, identify the fees that could realistically affect you, and then choose habits or account features that reduce those costs.

    Benefits and Drawbacks of Avoiding Credit Union Fees

    Avoiding unnecessary credit union fees can help your money go further, but the cheapest option is not always the best option. A fee may sometimes pay for a service or convenience you genuinely use. The better goal is to eliminate avoidable costs while keeping the banking features that matter to you.

    Benefits

    • Lower everyday costs: Avoidable charges leave more money available for saving or spending.
    • Easier budgeting: Fewer unexpected fees can make monthly cash-flow planning more predictable.
    • Better account choices: Understanding fees helps you compare accounts based on how you actually bank.
    • Stronger money habits: Monitoring balances and account activity can reduce preventable mistakes.

    Drawbacks

    • Extra effort: Some fee waivers require you to monitor balances, deposits, or account activity.
    • Less convenience: Restricting ATM use may be inconvenient when you need cash away from your usual area.
    • Feature trade-offs: An account with fewer fees may not offer every service or benefit you want.
    • Switching costs: Changing accounts solely to avoid a minor fee may not justify the time and effort.

    Smart approach: Judge an account by its overall value, not by one fee alone. If avoiding a charge creates more inconvenience than the savings are worth, keeping the existing option may be the more sensible choice.

    Credit Union Fee Comparison Table

    Comparing credit union fees is easier when you look at the rules behind each charge, not just the advertised account name. One account may waive a fee under certain conditions, while another may avoid the charge without requiring a minimum balance. Use this table as a practical checklist, then verify the current terms before opening an account.

    Fee TypeWhat May VaryWhat to CheckWays to Reduce the Risk
    Monthly maintenanceFee amount and waiver conditionsBalance, direct deposit, or activity requirementsChoose requirements you can consistently meet
    ATMNetwork access, outside-ATM charges, and reimbursement rulesWhich ATMs are included and whether reimbursement has limitsUse participating ATMs when practical
    OverdraftAvailable coverage, fees, and account settingsWhich transactions are covered and what alternatives are offeredMonitor available funds and understand your settings
    NSFReturned-payment policy and applicable chargesWhat happens when available funds are insufficientKeep enough money available for scheduled payments
    Other servicesChecks, statements, transfers, and special servicesWhich services carry separate chargesUse included or lower-cost options when they meet your needs

    Comparison tip: Don’t choose an account simply because one fee is lower. Think about how often you use ATMs, whether you can meet balance requirements, how you handle recurring payments, and which services you actually use. A slightly different account structure may save more over time if it fits your routine better.

    Always check the credit union’s current disclosures before making a decision. Fees, waiver requirements, ATM arrangements, and available account features can change, so the terms that apply today matter more than an older comparison.

    Costs, Risks and Expert Tips for Avoiding Credit Union Fees

    Avoiding unnecessary fees can save money, but there is another cost to consider: your time, attention, and convenience. Switching accounts just to eliminate a small occasional charge may not be worthwhile. A better strategy is to focus first on fees that are recurring, preventable, or likely to affect your finances more often.

    Watch These Common Risks

    • Overdraft exposure: Understand how your credit union handles overdrafts and which services require your affirmative opt-in, particularly for ATM and one-time debit card transactions.
    • ATM costs: An out-of-network withdrawal may result in a fee from your credit union, the ATM operator, or both, depending on the applicable terms and disclosures.
    • Account requirements: A fee waiver may depend on a balance, deposit, or activity requirement that becomes harder to meet after your financial routine changes.
    • Outdated information: Fee schedules and account terms can change, so do not rely on information you reviewed years ago.

    Expert Tip: Prioritize the Fees You Can Control

    Start with the charges most closely connected to your normal banking habits. If you regularly withdraw cash, pay attention to ATM network access. If overdrafts are a concern, review the available settings and protection options. If you rarely use a particular service, check whether you can avoid paying for it.

    Practical rule: Before changing accounts, estimate how often a particular fee could affect you. Compare that potential cost with the time, effort, and loss of convenience involved in switching. This helps you focus on meaningful savings instead of chasing every small charge.

    Common Mistakes and Real-Life Examples

    Many avoidable credit union fees come from everyday oversights rather than major financial mistakes. A member may miss an account requirement, use an unfamiliar ATM, or forget about a payment that is scheduled to leave the account. These simple examples show why small checks can make a difference.

    Mistake 1: Assuming a Low-Fee Account Has No Conditions

    Example: Maria chooses a checking account because its monthly cost appears low. She later learns that the charge can be avoided only when certain account requirements are met. Reading the current fee schedule before opening the account could have helped her understand those conditions.

    Mistake 2: Using an Unfamiliar ATM Without Checking the Network

    Example: David needs cash while traveling and uses an ATM without checking whether it belongs to his credit union’s network. Depending on the applicable terms, the ATM operator and credit union may each impose a fee. Checking ATM access before withdrawing cash can reduce this risk.

    Mistake 3: Ignoring the Timing of Upcoming Transactions

    Example: James sees money in his account but forgets about a scheduled payment that is due soon. If available funds are not sufficient when the transaction is processed, the payment could lead to an overdraft or returned-payment situation, depending on the transaction and account terms.

    Lesson: Avoiding credit union fees often comes down to knowing your account rules and matching them with your daily habits. Check fee requirements, understand your ATM options, and review available funds before important transactions are processed.

    Who Should Focus on Avoiding Credit Union Fees?

    Almost any credit union member can benefit from avoiding unnecessary fees, but the impact can be greater for people who use their accounts frequently or have little room for unexpected expenses. The goal is not to eliminate every possible charge. It is to prevent costs that are avoidable and do not provide meaningful value.

    Beginners

    New members can benefit from learning account requirements, ATM rules, and common charges before they become a problem.

    Families

    Households with recurring bills and frequent transactions may have more opportunities to prevent avoidable account charges.

    Retirees

    Retirees who carefully manage regular account activity may value predictable banking costs and fewer unexpected charges.

    Frequent ATM Users

    Members who regularly withdraw cash should pay close attention to ATM networks, access rules, and reimbursement policies.

    Best approach: If your current account rarely generates fees and already fits your needs, you may not need to switch. Focus first on recurring or preventable costs, and compare alternatives only when the potential savings justify the effort.

    Frequently Asked Questions About Credit Union Fees

    1. How can I avoid credit union fees?

    You can avoid many credit union fees by choosing an account that fits your banking habits, meeting applicable waiver requirements, using participating ATMs, monitoring available funds, and reviewing the current fee schedule.

    2. Do credit unions charge monthly maintenance fees?

    Some credit union accounts may charge a monthly maintenance fee, while others may not. Some accounts may also waive a fee when specific balance, deposit, or activity requirements are met. Check the account’s current terms before opening it.

    3. How can I avoid credit union ATM fees?

    Use ATMs included in your credit union’s available network when practical. Also check whether your account offers ATM-fee reimbursement and whether any limits or conditions apply.

    4. How can I avoid credit union overdraft fees?

    Monitor your available balance, keep enough money available for upcoming transactions, and understand your credit union’s overdraft settings and available protection options. For covered ATM and one-time debit card overdraft services, understand whether you have affirmatively opted in.

    5. What is the difference between an overdraft fee and an NSF fee?

    An overdraft generally occurs when a credit union pays a transaction even though available funds are insufficient. An NSF situation generally involves a transaction being returned because available funds are insufficient. The exact fees, transaction treatment, and policies depend on the credit union and account.

    6. Can a credit union waive a fee?

    A credit union may waive or reverse a fee in some circumstances, but it is not guaranteed. If you see an unexpected charge, ask the credit union what caused it and whether a fee-waiver option is available.

    7. Should I switch credit unions to avoid fees?

    Not necessarily. If your current account works well and rarely charges you, switching may not be worthwhile. Compare the potential savings with the time, effort, and features you could give up by changing accounts.

    8. Where can I find my credit union’s fees?

    Start with the credit union’s current fee schedule, account disclosures, and applicable account agreement. You can also contact the credit union directly if a charge or requirement is unclear.

    FAQ takeaway: Credit union fees vary by institution and account. The safest approach is to review the current terms, understand the charges most relevant to your banking habits, and ask questions before a fee becomes a recurring expense.

    Final Verdict: How to Avoid Credit Union Fees

    The smartest way to avoid credit union fees is not simply to find an account with the fewest advertised charges. Choose an account whose requirements, access, and services fit the way you actually manage your money.

    Start by reviewing the current fee schedule and account disclosures. Pay close attention to monthly maintenance requirements, ATM access, overdraft policies, NSF charges, and services you use regularly. Then build simple habits around the costs you can control, such as checking available funds before important transactions and using eligible ATMs.

    For beginners, families, retirees, and frequent ATM users, understanding these rules can make banking costs easier to manage. But switching accounts is not automatically the answer. If your current credit union account already fits your needs and rarely creates avoidable charges, keeping it may be more practical.

    Bottom line: Understand the rules, prevent the charges you can control, and compare alternatives when the potential savings are meaningful. That is a practical way to reduce unnecessary credit union fees in 2026 without giving up useful banking features.

    Have a Money Question? Keep Exploring.

    The right account is one that fits your habits, keeps unnecessary costs under control, and gives you the services you actually need. Keep exploring FinanceInvestment for practical guides that can help you make more informed money decisions.

    Have a question about money? Email FinanceInvestment

    Continue Your Research