Documents Needed to Open a Money Market Account
What Documents Do You Need to Open a Money Market Account?
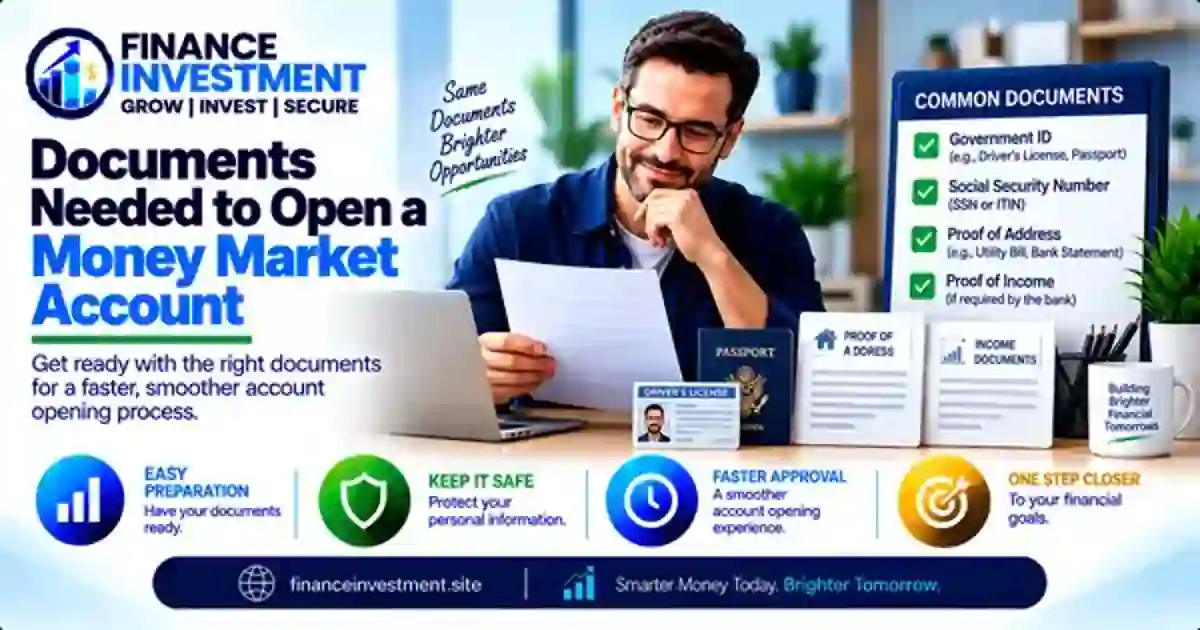 Opening a money market account is usually easier when your paperwork is ready before you start. The documents needed to open a money market account often include a government-issued form of identification and information used to verify your identity, address, and tax status. Your bank or credit union may also ask for funding information, but the exact requirements can vary by institution and account type.
The application method can affect what you provide and how verification takes place. An online application may use electronic identity checks, while a branch application may require you to show original or acceptable identification. If you are opening a joint account, the financial institution will generally need information from each applicant.
The goal of this guide is simple: help you prepare without carrying a folder full of documents you may never need. We’ll explain the common paperwork, why each item may be requested, and what can change for special account situations. For the bigger picture, start with our money market accounts guide.
What You’ll Learn
- Which identification details and documents a bank or credit union may request.
- Why Social Security numbers or other tax identification information may be required.
- What may be used to verify your residential address and provide account-funding information.
- How joint accounts and certain special ownership situations can change the application requirements.
- What to do if you cannot provide a document the institution requests.
What Do You Need to Open a Money Market Account?
Many applicants will need an acceptable government-issued identification document, personal details such as their legal name and date of birth, and a Social Security number or another tax identification number when applicable. The institution may also need information to verify your residential address and details for making the initial deposit. The exact checklist can vary by bank or credit union, account ownership, and whether you apply online or at a branch.
Key Takeaways
- Have an acceptable government-issued ID or other identification the institution accepts.
- Expect to provide basic personal information, including your legal name, date of birth, address, and contact details.
- A Social Security number or another taxpayer identification number may be requested as part of identity verification and account reporting requirements.
- Address verification may involve information or documents beyond the identification you initially provide.
- Each person opening a joint account may need to provide their own identifying information and complete identity verification.
- Online applications may use electronic identity checks, document uploads, or other verification methods instead of requiring an in-person visit.
The practical approach:
Gather your identification and personal information first, then check the institution’s application requirements for any additional verification or funding details before you apply.
Table of Contents
Documents Needed at a Glance
What Each Document Does
How Account-Opening Verification Works
Benefits and Drawbacks of Preparing Documents First
Document Comparison Table
Costs, Risks and Expert Tips
Common Mistakes and Real-Life Example
Who May Need Extra Documents?
Frequently Asked Questions
Final Verdict
Related Resources and Authority Links
Get Started
Documents Needed at a Glance
The paperwork for a money market account is not identical at every financial institution. Banks and credit unions have their own application requirements and identity-verification procedures. As a starting point, it helps to have the following documents or information available.
| Document or Information | Why It May Be Requested |
|---|---|
| Government-issued identification | To help verify your identity. An accepted driver’s license, state ID, or passport may be used, depending on the institution. |
| Social Security number or other TIN | To provide required tax-identification information and support the institution’s identity-verification process when applicable. |
| Personal information | Details such as your legal name, date of birth, residential address, phone number, and email address may be requested. |
| Address verification | Additional information or documentation may be requested if the institution needs to confirm your residential address. |
| Funding information | Details such as another bank account or debit card information may be needed to make the initial deposit, depending on the funding method. |
One useful distinction:
Not everything on this checklist is a physical document. Some items are personal information or funding details, and your institution may verify certain information electronically rather than asking you to provide a separate piece of paper.
What Each Document Does
The reason behind each request is fairly simple: the financial institution needs enough information to identify you and verify that the information you provide is reliable. Federal customer-identification rules require banks to collect certain basic information before opening an account, while the exact verification process can vary by institution.
Government-Issued Identification
A driver’s license, state identification card, passport, or another acceptable government document may be used to help verify your identity. The institution decides which documents it accepts, so its current requirements should be your final checklist.
Social Security Number or Other TIN
For U.S. persons, a taxpayer identification number is part of the information banks generally collect for account opening. Depending on the applicant’s circumstances, a non-U.S. person may have other acceptable identification-number options under the applicable rules.
Name, Date of Birth and Address
Your name, date of birth, and address are core identifying details used during account opening. A bank may use documents, electronic checks, other verification methods, or a combination of them to confirm the information. Extra address documentation is not automatically required in every application.
How the Account-Opening Verification Works
 When you apply for a money market account, the financial institution needs to establish your identity before opening the account. Federal customer-identification rules require covered institutions to collect certain identifying information, while the methods used to verify that information can vary from one institution to another.
1. You submit your information
The application may ask for your name, date of birth, address, identification number, and other contact or account information.
2. Your identity is verified
The institution may examine an acceptable identification document, use non-documentary checks such as electronic verification, or use a combination of methods.
3. The account application is completed
Depending on the institution, you may review account terms, provide required signatures or confirmations, and arrange the initial funding.
If something cannot be verified:
The institution may request additional information or documentation, or take another step under its account-opening procedures. The outcome depends on the institution and the circumstances of the application.
Benefits and Drawbacks of Preparing Documents First
Getting your basic information together before applying for a money market account can make the process more organized. The key is not to gather every document you own. Prepare the items you are likely to need, then follow the financial institution’s specific instructions for anything else.
Benefits
- Less interruption: Having your identification and personal details ready can reduce the chance of pausing an application to locate information.
- Fewer avoidable mistakes: Checking your information before submitting it can help prevent simple spelling, address, or number errors.
- Clearer preparation: You can identify questions about ownership, address verification, or funding before you begin.
Drawbacks
- Unnecessary paperwork: You might spend time collecting documents the institution does not require.
- Outdated information: An expired ID or old address can lead to additional verification steps.
- Unnecessary exposure: Sharing extra copies of sensitive documents can create privacy and security risks.
A sensible rule:
Prepare the basic information and identification you are likely to need, but provide additional documents only when the institution requests them or its application instructions call for them.
Document Comparison Table
Not every item you provide during a money market account application is a physical document. Some information is entered directly into the application, while other details may be verified electronically or supported with documentation if the institution requests it. This distinction can help you prepare without collecting paperwork you may not need.
| Item | What It Helps With | How It May Be Provided |
|---|---|---|
| Government-issued ID | Identity verification | An accepted ID may be shown, uploaded, or otherwise verified, depending on the application. |
| SSN or other TIN | Taxpayer identification and identity verification | Usually provided as identifying information; additional documentation may depend on the institution and applicant. |
| Residential address | Address identification and verification | Entered in the application; supporting information or documentation may be requested. |
| Personal details | Basic customer identification | Typically entered directly into the application. |
| Funding information | Initial account funding | May include information from another bank account or a debit card, depending on the funding option. |
The takeaway:
Treat the table as a preparation guide, not a universal checklist. The financial institution’s current application instructions determine which documents or verification steps you actually need to complete.
Costs, Risks and Expert Tips
Opening paperwork and account costs are two different things. A money market account may have a minimum opening deposit, minimum balance requirement, monthly maintenance fee, or other account-specific charges, while another account may not. Check the institution’s current fee schedule and account disclosures rather than assuming the document checklist tells you what the account will cost.
Watch for Verification and Privacy Risks
Differences between your application and identification information can trigger additional verification. Do not submit altered, expired, or inaccurate information. For sensitive documents, use the financial institution’s official application or another submission method it specifically provides. Avoid sending copies through an unverified email address or third-party contact.
Expert Tips Before You Apply
- Check that your identification is current and that the name matches the information you submit.
- Review which identification and address-verification methods the institution accepts before gathering additional paperwork.
- Check the minimum opening deposit, minimum balance, monthly fee, and account-access terms separately from the document requirements.
- Keep sensitive documents secure and retain copies only when they are useful for your records.
Common Mistakes and an Illustrative Example
A few avoidable mistakes can add extra steps to a money market account application. Applicants sometimes assume that every financial institution accepts the same identification, use an expired document, enter an old address, or provide information that does not match their application. Another common mix-up is treating the minimum opening deposit and minimum balance requirement as the same thing.
An Illustrative Example
Suppose Alex applies online for a money market account after moving to a new apartment. Alex enters the new address but submits identification showing the previous address. The institution may need additional information or another verification step before it can complete the application.
Alex checks the institution’s instructions and provides the requested information through its designated application or verification channel. The takeaway is straightforward: use current, accurate information and follow the institution’s specific instructions when something needs clarification.
Quick check:
Before submitting your application, review your legal name, date of birth, address, identification details, and funding information for accuracy. Then confirm that the documents and verification methods you plan to use are accepted by the institution.
Who May Need Extra Documents?
Not every applicant will have the same account-opening checklist. A financial institution may request additional information or documentation when the account has multiple owners, the applicant is a minor, identity information needs further verification, or the account is being opened under a special ownership arrangement.
Each owner may need to provide identifying information and complete the institution’s required verification.
Depending on the account structure and institution, a parent, guardian, or other authorized adult may need to provide additional information or documentation.
Identification and taxpayer-identification requirements can differ based on the applicant’s circumstances and the institution’s policies.
An account opened for a trust or another legal arrangement may require documents establishing the arrangement and identifying the people authorized to act for it.
Keep the checklist specific to you:
Extra documentation is not automatically required just because you fall into one of these categories. The institution’s current application instructions determine what it needs to complete verification and open the account.
Frequently Asked Questions
1. What documents do I need to open a money market account?
You may need an acceptable government-issued ID, personal identifying information, and a Social Security number or other identification number that applies to your circumstances. Address verification or funding information may also be requested.
2. Do I need a driver’s license to open a money market account?
Not necessarily. A financial institution may accept a passport, state ID, or another qualifying form of identification. Check its current list of accepted documents before applying.
3. Do I need proof of address?
You may. The institution can use the address information you provide and may use documents, electronic checks, or other verification methods. A separate proof-of-address document is not automatically required in every application.
4. Do I need my Social Security number?
For a U.S. person, a taxpayer identification number is generally part of the identifying information collected when opening a bank account. For a non-U.S. person, the institution may collect another identification number or qualifying government-issued information under applicable requirements.
5. Can I open a money market account online?
Many financial institutions offer online account opening. The process may include electronic identity verification, document uploads, or other checks, and some applications may require additional steps.
6. What documents are needed for a joint money market account?
Each joint owner may need to provide identifying information and complete the institution’s required verification. Additional requirements depend on the account and financial institution.
7. What if my ID has an old address?
Provide your current address in the application and follow the institution’s verification instructions. It may request additional information or documentation before completing the application.
8. Can a bank ask for additional documents after I apply?
Yes. If the institution cannot complete its identity verification using the information initially provided, it may request additional information or documentation under its account-opening procedures.
Remember:
These answers describe common account-opening requirements, not a universal checklist. The financial institution’s current application instructions determine exactly what you need to provide.
Final Verdict
Opening a money market account usually starts with a manageable set of identification and personal information. You may need an acceptable government-issued ID, taxpayer-identification information, and details such as your name, date of birth, and residential address. The institution may ask for additional information if its verification process requires it.
The key is to prepare without overdoing it. Check the institution’s current requirements, use information that is accurate and up to date, and understand how the initial deposit will be made. If additional documentation is requested, submit it through the institution’s designated channel rather than sending sensitive records unnecessarily.
Bottom line:
Have your identification and core personal information ready, verify the institution’s specific checklist, and provide only the additional documentation needed to complete your application.
Leave a Reply