Author: subhashr325

  • Bond Ladder vs Dividend Income for Retirees: Which Retirement Income Strategy Is Better in 2026?

    Bond Ladder vs Dividend Income for Retirees: Which Retirement Income Strategy Is Better in 2026?


    Bond Ladder vs Dividend Income for Retirees: Which Strategy Wins in 2026?

    Author: Subhash Rukade

    Published: June 21, 2026
    Bond Ladder vs Dividend Income

    Why Retirees Compare Bond Ladders and Dividend Income

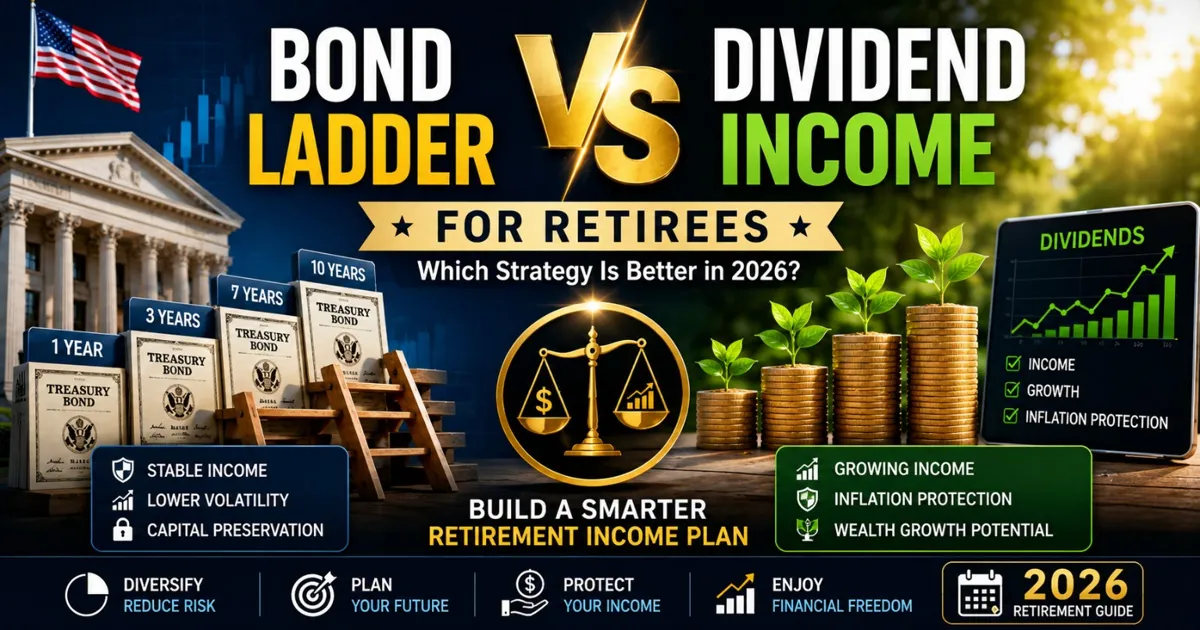
    Bond Ladder vs Dividend Income for Retirees is one of the most important retirement planning discussions in 2026. Retirees want reliable income, protection from market volatility, and enough growth to keep pace with inflation.

    The challenge is that no retirement income strategy is perfect. Some investors prioritize stability and predictable cash flow. Others focus on long-term income growth and wealth preservation.

    This is where the debate between bond ladders and dividend income becomes important.

    A bond ladder uses bonds with different maturity dates. As each bond matures, it provides cash that can be spent or reinvested. Many retirees appreciate this strategy because it creates predictable income and reduces interest-rate risk.

    Dividend income works differently. Investors purchase dividend-paying stocks or ETFs that distribute income regularly. Unlike bonds, dividend investments can increase payments over time and provide stronger growth potential.

    However, dividend income also comes with greater market volatility and the possibility of dividend reductions during difficult economic periods.

    The right choice depends on your retirement goals, risk tolerance, and income needs.

    Before choosing either strategy, retirees should build a complete retirement roadmap. Our

    Retirement Planning Guide for Americans in 2026

    explains retirement income planning, portfolio design, withdrawal strategies, and long-term wealth preservation.

    Many successful retirees ultimately combine bond ladders and dividend income rather than relying entirely on one approach. Understanding the strengths and weaknesses of both strategies is the first step toward building a sustainable retirement income plan.

    In this guide, we’ll compare bond ladders and dividend income, examine real-world examples, discuss common mistakes, and help you determine which retirement income strategy may work best for your financial future.

    Understanding Bond Ladder Strategies for Retirement Income

    A bond ladder is one of the most widely used retirement income strategies because it provides predictable cash flow and helps retirees manage investment risk.

    When comparing Bond Ladder vs Dividend Income for Retirees, many conservative investors prefer bond ladders because they offer scheduled income and lower volatility than stocks.

    A bond ladder is created by purchasing bonds with different maturity dates.

    Instead of investing all your money into a single bond, you spread investments across multiple bonds that mature at different times.

    As each bond matures, you receive your principal back along with interest payments earned during the holding period.

    Example of a Simple Bond Ladder

    • Year 1 Bond: $50,000
    • Year 3 Bond: $50,000
    • Year 5 Bond: $50,000
    • Year 7 Bond: $50,000
    • Year 10 Bond: $50,000

    As each bond matures, retirees can either spend the proceeds or purchase a new long-term bond to maintain the ladder.

    Types of Bonds Used in Retirement Ladders

    1. Treasury Bonds

    Treasury bonds are backed by the U.S. government and are generally considered among the safest investments available.

    Many retirees use Treasury ladders because they provide reliable income and capital preservation.

    2. Corporate Bonds

    Corporate bonds usually offer higher yields than Treasury bonds.

    However, they also carry additional credit risk because repayment depends on the financial strength of the issuing company.

    3. Municipal Bonds

    Municipal bonds can provide tax advantages for retirees, especially those in higher tax brackets.

    Interest earned from many municipal bonds may be exempt from federal income taxes.

    Benefits of a Bond Ladder

    • Predictable retirement cash flow
    • Lower market volatility
    • Reduced interest-rate risk
    • Capital preservation
    • Flexible reinvestment opportunities

    Potential Risks

    Although bond ladders provide stability, they are not perfect.

    Inflation can reduce purchasing power over time, and rising interest rates may affect bond prices.

    For this reason, many retirees combine bond ladders with dividend-paying investments and growth assets.

    Investors concerned about economic uncertainty should also review our

    Recession-Proof Investing 2026

    guide.

    Bond ladders can provide stability and peace of mind, but they are only one side of the retirement income equation. In the next section, we’ll explore how dividend income strategies work and why many retirees use them to generate growing retirement cash flow.

    Understanding Dividend Income for Retirees

    When comparing Bond Ladder vs Dividend Income for Retirees, dividend investing is often viewed as the growth-oriented alternative.

    While bond ladders focus on predictable income and capital preservation, dividend investments aim to generate cash flow while still allowing portfolios to grow over time.

    Many retirees prefer dividend income because it offers the potential for rising income streams. Unlike fixed bond payments, dividend payments can increase when companies raise their dividends.

    This feature makes dividend investing particularly attractive during periods of inflation.

    What Is Dividend Income?

    Dividend income comes from companies that share a portion of their profits with shareholders.

    When you own dividend-paying stocks or dividend-focused ETFs, you receive regular cash payments that can be used for retirement expenses or reinvested.

    Many established companies have long histories of paying and increasing dividends.

    Dividend Stocks vs Dividend ETFs

    Retirees generally choose between individual dividend stocks and diversified dividend ETFs.

    Dividend stocks may offer higher yields and greater income growth potential.

    Dividend ETFs provide diversification and reduce company-specific risk.

    Many retirees use a combination of both approaches.

    If you’re building a retirement dividend strategy, read our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource for income ideas.

    Retirement Income Calculator Example

    Let’s compare a simple dividend portfolio example.

    Assume a retiree has a $500,000 portfolio invested in dividend-paying stocks and ETFs with an average dividend yield of 4%.

    • Portfolio Value: $500,000
    • Dividend Yield: 4%
    • Annual Dividend Income: $20,000
    • Monthly Dividend Income: Approximately $1,667

    If dividend payments grow by 5% annually, retirement income may increase over time without requiring additional contributions.

    Benefits of Dividend Income

    • Potential for growing income
    • Inflation protection
    • Long-term capital appreciation
    • Flexible retirement cash flow
    • Passive income generation

    Potential Risks

    Dividend income is not guaranteed.

    Companies can reduce or suspend dividends during economic downturns. Stock prices may also experience significant volatility.

    This is one reason many retirees combine dividend investing with bond ladders rather than relying exclusively on one strategy.

    The debate around Bond Ladder vs Dividend Income for Retirees often comes down to one question: stability versus growth. In the next section, we’ll compare both strategies side by side and analyze a real-world retirement income case study.

    Bond Ladder vs Dividend Income: Which Is Better for Retirees?

    The debate around Bond Ladder vs Dividend Income for Retirees often comes down to one key question:

    Do you want maximum income stability or greater long-term income growth?

    Both strategies can play an important role in retirement planning. However, they serve different purposes and perform differently under changing market conditions.

    Understanding these differences can help retirees create a more reliable retirement income plan.

    Bond Ladder vs Dividend Income Comparison

    FeatureBond LadderDividend Income
    Income StabilityHighModerate
    Growth PotentialLow to ModerateHigh
    Inflation ProtectionLimitedStrong
    Market VolatilityLowHigher
    Capital AppreciationLimitedStrong
    Tax EfficiencyModerateCan Be Favorable

    When Bond Ladders May Be Better

    Bond ladders are often preferred by conservative retirees who prioritize predictable income and capital preservation.

    They can help reduce stress during market downturns because bond maturity dates and interest payments are generally known in advance.

    For retirees who depend heavily on investment income, stability can be extremely valuable.

    When Dividend Income May Be Better

    Dividend investing may be a better choice for retirees seeking long-term income growth and inflation protection.

    Many dividend-paying companies increase their payouts over time, helping investors maintain purchasing power throughout retirement.

    Dividend portfolios may also benefit from stock price appreciation.

    Real-World Retirement Case Study

    Consider two retirees, each with a $1 million retirement portfolio.

    Retiree A chooses a bond ladder:

    • Portfolio Value: $1,000,000
    • Average Yield: 4%
    • Annual Income: $40,000
    • Lower Volatility

    Retiree B chooses dividend investments:

    • Portfolio Value: $1,000,000
    • Average Yield: 4%
    • Annual Income: $40,000
    • Potential Dividend Growth
    • Potential Capital Appreciation

    Initially, both retirees receive similar income.

    However, over the next ten years, Retiree B may experience increasing dividend payments if underlying companies continue growing profits and raising dividends.

    Meanwhile, Retiree A benefits from greater income stability and reduced market volatility.

    This example demonstrates why many retirees combine both approaches rather than choosing only one.

    For a complete retirement strategy, review our

    Retirement Planning Guide for Americans in 2026
    .

    The most successful retirement plans often balance stability and growth. A combination of bond ladders and dividend income may provide the best of both worlds for many retirees.

    In the next section, we’ll examine common mistakes retirees make when using bond ladders and dividend income strategies and how to avoid them.

    Common Mistakes Retirees Make With Bond Ladders and Dividend Income

    Even the best retirement strategy can fail if investors make avoidable mistakes. When comparing Bond Ladder vs Dividend Income for Retirees, many retirees focus on income potential but overlook the risks that can reduce long-term financial security.

    Understanding these common mistakes can help retirees protect their portfolios and create more reliable retirement income.

    Mistake #1: Chasing the Highest Yield

    Many retirees are attracted to investments with unusually high yields.

    While a high yield may seem appealing, it often signals increased risk.

    Some companies maintain unsustainably high dividend payouts that may eventually be reduced or eliminated.

    Similarly, high-yield bonds typically carry greater credit risk.

    Retirees should focus on quality and sustainability rather than yield alone.

    Mistake #2: Ignoring Inflation

    Inflation remains one of the biggest threats to retirement income.

    Bond ladders provide predictable cash flow, but fixed interest payments may lose purchasing power over time.

    Dividend-paying companies often have the ability to increase payouts, helping investors keep pace with rising living costs.

    This is why many retirees combine bond ladders with dividend growth investments.

    Mistake #3: Poor Diversification

    Some retirees invest too heavily in a single strategy.

    A portfolio built entirely around bonds may struggle to generate long-term growth. On the other hand, a portfolio invested only in dividend stocks may experience greater volatility.

    Diversification remains one of the most effective ways to manage retirement risk.

    Mistake #4: Ignoring Technology and Modern Planning Tools

    Today’s retirees have access to powerful planning tools that previous generations never had.

    AI-driven investment platforms can help monitor risk, evaluate retirement income needs, and improve decision-making.

    To learn more, read our

    AI Investing Guide 2026
    .

    Mistake #5: Failing to Follow a Long-Term Investment Plan

    Many investors react emotionally during market downturns.

    Selling quality investments after temporary market declines can permanently damage retirement income plans.

    A disciplined investment process is essential for long-term success.

    Investors who prefer systematic investing approaches can also review our

    SIP Investing Guide 2026
    .

    Mistake #6: Overlooking Tax Planning

    Taxes can significantly affect retirement income.

    Interest income, dividends, and capital gains may be taxed differently depending on account type and income level.

    Retirees should understand the tax implications of both bond ladders and dividend portfolios before making major investment decisions.

    The most successful retirees focus on building balanced portfolios rather than searching for a perfect investment. Avoiding these common mistakes can help improve retirement income stability and long-term financial confidence.

    In the next section, we’ll cover practical retirement income strategies, trusted financial resources, and investment tools that can help retirees strengthen their retirement plans in 2026.

    Practical Tips for Retirees: Combining Bond Ladders and Dividend Income

    For many investors, the answer to the Bond Ladder vs Dividend Income for Retirees debate is not choosing one strategy over the other. Instead, it is learning how to combine both approaches effectively.

    Bond ladders provide stability and predictable income. Dividend investments offer growth potential and inflation protection. Together, they can create a balanced retirement income plan.

    1. Match Income Sources to Your Retirement Goals

    Retirees who depend heavily on investment income may allocate a larger percentage of their portfolio to bonds and fixed-income investments.

    Those seeking long-term income growth may prefer a higher allocation to dividend-paying stocks and ETFs.

    2. Maintain Adequate Cash Reserves

    Unexpected expenses are inevitable during retirement.

    Keeping one to two years of living expenses in cash can help retirees avoid selling investments during market downturns.

    3. Reinvest Excess Income

    If retirement income exceeds spending needs, consider reinvesting excess cash flow.

    Reinvestment can strengthen future income and support long-term portfolio growth.

    4. Review Portfolio Allocations Annually

    Interest rates, inflation, and market conditions change over time.

    Annual portfolio reviews help ensure retirement income strategies remain aligned with personal goals.

    Retirement Income Checklist

    Checklist ItemStatus
    Diversified Income Sources✓
    Bond Ladder Established✓
    Dividend Income Portfolio Built✓
    Emergency Cash Reserve Available✓
    Annual Portfolio Review Scheduled✓
    Inflation Protection Included✓

    Trusted Retirement Resources

    Recommended Retirement Books


    The Intelligent Investor


    The Bogleheads’ Guide to Retirement Planning


    The Simple Path to Wealth

    The strongest retirement plans often combine stability, growth, and flexibility. By blending bond ladders with dividend income, retirees can create a retirement income system that is better prepared for inflation, market volatility, and changing financial needs.

    In the final section, we’ll explore future retirement income trends, answer common questions, and summarize which strategy may be best for retirees in 2026.

    The Future of Retirement Income Planning in 2026 and Beyond

    The retirement landscape continues to evolve. Rising life expectancy, changing interest rates, inflation concerns, and advancements in technology are transforming how retirees generate income.

    The debate around Bond Ladder vs Dividend Income for Retirees will likely continue for years. However, many financial experts believe the future belongs to diversified retirement income strategies rather than relying on a single approach.

    Today’s retirees have more tools, resources, and investment options than ever before. As a result, retirement income planning is becoming more personalized and flexible.

    How AI Is Changing Retirement Planning

    Artificial intelligence is becoming an important part of retirement investing.

    AI-powered tools can analyze portfolios, monitor spending patterns, estimate retirement income needs, and identify risks that may affect long-term financial security.

    Investors interested in these innovations should explore our

    AI Investing Guide 2026
    .

    Frequently Asked Questions

    1. Are bond ladders safer than dividend stocks?

    Generally, bond ladders provide more predictable income and lower volatility. However, dividend stocks often offer stronger long-term growth potential.

    2. Can retirees use both strategies together?

    Yes. Many retirees combine bond ladders and dividend income to balance stability, growth, and inflation protection.

    3. Which strategy is better for inflation?

    Dividend income often provides stronger inflation protection because many companies increase dividends over time.

    4. How much of a retirement portfolio should be allocated to bonds?

    The answer depends on age, risk tolerance, and retirement goals. Many retirees use a mix of bonds, dividend stocks, and cash reserves.

    5. Is a bond ladder still useful in 2026?

    Yes. Bond ladders remain one of the most effective tools for generating predictable retirement cash flow and reducing interest-rate risk.

    Conclusion

    The choice between Bond Ladder vs Dividend Income for Retirees is not always an either-or decision.

    Bond ladders provide stability, predictable income, and capital preservation. Dividend investments offer income growth, inflation protection, and long-term wealth-building opportunities.

    For many retirees, combining both strategies creates the strongest retirement income plan.

    If you’re building a complete retirement roadmap, don’t miss our

    Retirement Planning Guide for Americans in 2026
    .

    With proper planning, diversification, and regular portfolio reviews, retirees can create dependable income streams that support financial independence for decades.

    📩 Retirement Wealth Newsletter

    Get retirement income ideas, dividend strategies, Social Security updates, and wealth-building insights delivered directly to your inbox.

    Build smarter retirement income. Stay ahead of market changes.


    ✍️ About the Author

    Subhash Rukade is the founder of
    FinanceInvestment.site and writes about retirement planning, dividend investing, passive income, personal finance, and long-term wealth creation. His mission is to help American investors make confident financial decisions and build lasting wealth through practical, easy-to-understand strategies.
  • Retirement Income Ladder Strategy Explained: How to Create Reliable Retirement Cash Flow in 2026

    Retirement Income Ladder Strategy Explained: How to Create Reliable Retirement Cash Flow in 2026


    Retirement Income Ladder Strategy Explained: Build Reliable Retirement Cash Flow in 2026

    Author: Subhash Rukade

    Published: June 20, 2026

    Retirement Income Ladder Strategy

    What Is a Retirement Income Ladder Strategy?

    A Retirement Income Ladder Strategy is one of the most effective ways to create predictable income during retirement. Instead of relying entirely on stock market performance or withdrawing money randomly from investment accounts, retirees build a series of investments that mature at different times and generate scheduled income.

    Think of a ladder. Each rung represents an investment with a different maturity date. As one investment matures, it provides cash that can be used for living expenses or reinvested into a new rung of the ladder.

    This approach helps retirees manage risk while creating a more dependable retirement income stream.

    Many financial planners recommend ladder strategies because they reduce uncertainty. Rather than worrying about market volatility every day, retirees know when certain investments will mature and how much income they can expect.

    A retirement income ladder can be built using Treasury bonds, corporate bonds, certificates of deposit (CDs), municipal bonds, or even dividend-focused investments.

    For retirees who value stability, a ladder strategy can provide confidence and peace of mind throughout retirement.

    If you’re building a complete retirement roadmap, start with our

    Retirement Planning Guide for Americans in 2026
    .
    This guide explains retirement investing, withdrawal strategies, income planning, and long-term wealth preservation.

    The biggest advantage of a retirement income ladder strategy is predictability. Instead of depending on one source of income, retirees create a structured system that delivers cash flow year after year.

    In this guide, you’ll learn how retirement income ladders work, how to build one, common mistakes to avoid, and practical ways to use ladder strategies to strengthen retirement security in 2026 and beyond.

    Types of Retirement Income Ladder Strategies

    A Retirement Income Ladder Strategy is not limited to a single investment type. In fact, retirees can build different kinds of ladders depending on their income goals, risk tolerance, and retirement timeline.

    The best ladder strategy often combines safety, predictable cash flow, and flexibility.

    1. Bond Ladder Strategy

    A bond ladder is the most common retirement income ladder.

    Investors purchase bonds with different maturity dates. For example, some bonds mature in one year, others in three years, five years, seven years, and ten years.

    As each bond matures, the proceeds can be used for retirement expenses or reinvested into a new bond.

    This strategy helps retirees reduce interest-rate risk while creating a predictable income schedule.

    2. CD Ladder Strategy

    Certificates of Deposit (CDs) are another popular ladder option.

    A CD ladder spreads money across CDs with different maturity dates. Because CDs are generally considered low-risk investments, they can provide stability for conservative retirees.

    When one CD matures, the funds can be used for income needs or reinvested into a longer-term CD.

    3. Treasury Ladder Strategy

    Many retirees prefer Treasury bonds because they are backed by the U.S. government.

    Treasury ladders can generate dependable income while helping preserve capital.

    This approach is particularly attractive during periods of economic uncertainty.

    4. Dividend Income Ladder

    Some retirees create a dividend ladder using stocks and ETFs that pay dividends at different times throughout the year.

    The goal is to generate regular monthly income without selling investments.

    If you’re interested in dividend-focused retirement income, read our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource.

    Advantages of Ladder Strategies

    • Predictable retirement cash flow
    • Reduced interest-rate risk
    • Portfolio diversification
    • Lower emotional investing decisions
    • Greater retirement income stability

    Potential Drawbacks

    • Lower growth compared to stock-heavy portfolios
    • Inflation can reduce purchasing power
    • Reinvestment decisions are still required

    The best Retirement Income Ladder Strategy depends on your retirement goals and overall portfolio design. Many successful retirees combine ladders with dividend income and long-term growth investments to create a balanced retirement plan.

    In the next section, we’ll build a retirement income ladder step-by-step and calculate how much retirement income different ladder portfolios can generate.

    How to Build a Retirement Income Ladder Step by Step

    A Retirement Income Ladder Strategy works best when it is carefully planned around your retirement expenses, income needs, and investment goals.

    The objective is simple: create a steady stream of cash flow that can support your lifestyle without forcing you to sell investments during unfavorable market conditions.

    Step 1: Calculate Your Annual Retirement Expenses

    Start by estimating how much money you’ll need each year during retirement.

    Include:

    • Housing expenses
    • Utilities
    • Healthcare costs
    • Insurance premiums
    • Travel and leisure
    • Food and groceries
    • Emergency expenses

    For example, if your retirement budget is $60,000 per year, that becomes your target income requirement.

    Step 2: Determine Guaranteed Income Sources

    Next, subtract predictable income sources such as Social Security or pensions.

    Example:

    • Annual Retirement Spending Goal: $60,000
    • Social Security Income: $30,000

    Remaining Income Need:
    $30,000 per year

    Your retirement income ladder should help generate this remaining amount.

    Step 3: Build the Ladder

    Suppose you have a $1 million retirement portfolio.

    You might divide part of it like this:

    • $100,000 Bond Maturing in Year 1
    • $100,000 Bond Maturing in Year 2
    • $100,000 Bond Maturing in Year 3
    • $100,000 Bond Maturing in Year 4
    • $100,000 Bond Maturing in Year 5

    As each bond matures, it provides cash for retirement expenses while the remaining portfolio continues to grow.

    Retirement Income Ladder Calculator Example

    Let’s assume a retiree needs $2,500 per month from investments:

    • Monthly Income Goal = $2,500
    • Annual Income Goal = $30,000
    • Five-Year Ladder Target = $150,000

    A ladder portfolio can be structured to cover these income needs while reducing exposure to market volatility.

    Example Retirement Ladder Cash Flow

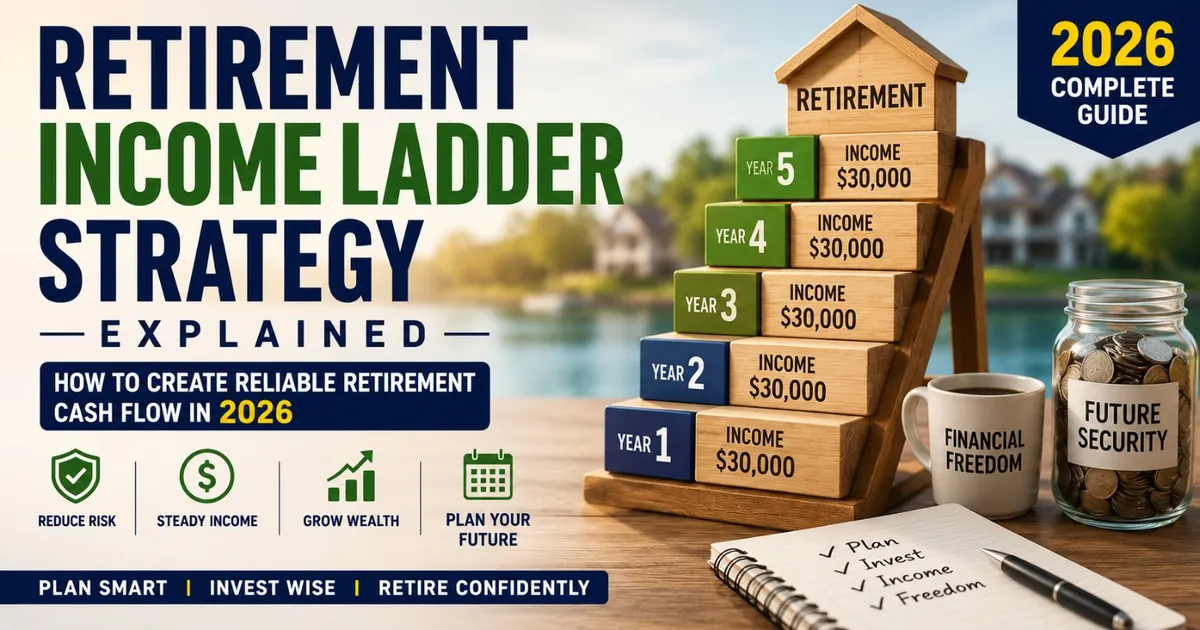
    • Year 1 Maturity = $30,000 Income
    • Year 2 Maturity = $30,000 Income
    • Year 3 Maturity = $30,000 Income
    • Year 4 Maturity = $30,000 Income
    • Year 5 Maturity = $30,000 Income

    This predictable cash flow is one reason many retirees prefer ladder strategies over relying entirely on portfolio withdrawals.

    A well-designed Retirement Income Ladder Strategy can provide stability, improve confidence, and reduce the emotional stress that often comes with retirement investing.

    In the next section, we’ll compare retirement income ladders with other retirement income strategies and review a real-world case study showing how a ladder strategy can support a $1 million retirement portfolio.

    Retirement Income Ladder vs Other Retirement Income Strategies

    A Retirement Income Ladder Strategy is popular because it creates predictable cash flow and reduces uncertainty. However, it is not the only retirement income strategy available.

    Many retirees combine ladder strategies with dividend investing, portfolio withdrawals, and growth investments to create a more balanced retirement plan.

    Understanding how these approaches compare can help investors choose the strategy that best fits their retirement goals.

    Retirement Income Strategy Comparison

    StrategyIncome StabilityGrowth PotentialRisk Level
    Income LadderHighLow to ModerateLow
    Dividend InvestingModerate to HighHighModerate
    Portfolio WithdrawalsModerateHighModerate to High
    Hybrid StrategyHighHighModerate

    Retirement Income Ladder Strategy

    The biggest advantage of an income ladder is predictability.

    Because investments mature at scheduled intervals, retirees know when cash will become available. This can reduce anxiety during market downturns and help retirees avoid selling stocks when prices are low.

    Dividend Income Strategy

    Dividend investing focuses on generating income from dividend-paying companies and ETFs.

    This approach offers stronger long-term growth potential than most bond ladders.

    However, dividend payments can fluctuate, and stock prices remain subject to market volatility.

    Hybrid Strategy

    Many financial planners consider the hybrid strategy the most flexible approach.

    A hybrid plan combines income ladders, dividend investments, cash reserves, and portfolio withdrawals.

    This diversification helps retirees balance growth, income, and risk management.

    Real-World Case Study

    Consider a retired couple with a $1 million retirement portfolio.

    • $300,000 Bond Ladder
    • $300,000 Dividend Stocks
    • $300,000 Broad Market Index Funds
    • $100,000 Cash Reserve

    Their annual retirement income sources include:

    • Social Security: $32,000
    • Bond Ladder Income: $12,000
    • Dividend Income: $10,000
    • Portfolio Withdrawals: $8,000

    Total Retirement Income:
    $62,000 Per Year

    Because income comes from multiple sources, they are less dependent on any single investment category.

    For a complete retirement roadmap, review our

    Retirement Planning Guide for Americans in 2026
    .

    This example demonstrates why many retirees prefer combining strategies rather than relying solely on one source of retirement income.

    A well-designed Retirement Income Ladder Strategy can serve as the foundation of a broader retirement income plan while providing predictable cash flow and financial confidence.

    In the next section, we’ll examine the most common mistakes retirees make when building income ladders and how to avoid them.

    Common Retirement Income Ladder Mistakes to Avoid

    A Retirement Income Ladder Strategy can provide reliable retirement cash flow, but it is not completely risk-free. Like any investment strategy, mistakes can reduce income, increase risk, and weaken long-term retirement security.

    Fortunately, most ladder-related problems can be avoided through careful planning and regular portfolio reviews.

    Mistake #1: Creating Large Gaps in the Ladder

    One of the most common mistakes is building a ladder with uneven maturity dates.

    For example, if multiple bonds mature in the same year while no investments mature during another period, retirees may face unexpected cash flow shortages.

    A properly structured ladder should provide income at regular intervals.

    Mistake #2: Ignoring Interest Rate Risk

    Interest rates play a major role in bond and CD ladder performance.

    Locking too much money into long-term investments during low-rate environments may reduce future income opportunities.

    Many retirees address this issue by staggering maturities and maintaining flexibility when reinvesting proceeds.

    Mistake #3: Underestimating Inflation

    Inflation can gradually reduce the purchasing power of retirement income.

    While ladder strategies provide stability, they may not generate enough growth to keep pace with rising living costs over long retirement periods.

    This is one reason many retirees combine ladders with dividend-paying stocks and growth investments.

    Mistake #4: Reinvestment Errors

    When investments mature, retirees must decide how to reinvest the proceeds.

    Poor reinvestment decisions can weaken future income streams and reduce ladder effectiveness.

    A disciplined reinvestment process helps maintain ladder strength over time.

    Mistake #5: Lack of Diversification

    Some investors rely entirely on bonds or CDs.

    While these investments offer stability, they may not provide enough growth for long retirements.

    Diversification remains essential for balancing income, growth, and risk.

    Investors concerned about economic uncertainty should also review our

    Recession-Proof Investing 2026

    guide.

    Mistake #6: Ignoring Modern Planning Tools

    Technology is transforming retirement planning.

    AI-powered tools can help retirees monitor income needs, evaluate portfolio risks, and improve retirement decision-making.

    Learn more in our

    AI Investing Guide 2026
    .

    The strongest Retirement Income Ladder Strategy is one that adapts to changing market conditions while continuing to generate dependable income. Avoiding these common mistakes can help retirees improve financial security and maintain confidence throughout retirement.

    In the next section, we’ll explore practical ladder-building tips, trusted retirement resources, and tools that can help strengthen your retirement income plan.

    Practical Tips for Building a Strong Retirement Income Ladder Strategy

    A successful Retirement Income Ladder Strategy is not just about buying bonds or CDs with different maturity dates. The real goal is to create a reliable retirement income system that can support your lifestyle while reducing financial stress.

    The following strategies can help retirees build a stronger and more sustainable retirement income ladder in 2026.

    1. Match Ladder Maturities to Spending Needs

    Before purchasing bonds or CDs, estimate your future retirement expenses.

    Align ladder maturities with expected cash flow needs. This helps ensure income is available when expenses arise.

    2. Combine Ladders With Dividend Income

    Many retirees use ladders for stability and dividend stocks for growth.

    This combination can create predictable income while helping portfolios keep pace with inflation.

    Investors interested in dividend income should review our

    How to Build a Dividend Portfolio

    guide.

    3. Maintain an Emergency Cash Reserve

    Unexpected expenses can happen at any time.

    Keeping one to two years of living expenses in cash may help retirees avoid selling investments during market downturns.

    4. Review the Ladder Every Year

    Interest rates, inflation, and personal spending needs change over time.

    Annual reviews help ensure the ladder continues meeting retirement income goals.

    5. Diversify Beyond Fixed Income

    While ladders provide stability, retirees should avoid putting all retirement assets into bonds or CDs.

    A diversified portfolio often includes dividend stocks, broad-market funds, cash reserves, and fixed-income investments.

    Retirement Income Ladder Checklist

    Checklist ItemStatus
    Retirement Income Goal Calculated✓
    Ladder Maturities Scheduled✓
    Emergency Cash Reserve Established✓
    Dividend Income Included✓
    Annual Review Planned✓
    Inflation Protection Included✓

    Trusted Retirement Resources

    Recommended Retirement Books


    The Bogleheads’ Guide to Retirement Planning


    The Intelligent Investor


    The Simple Path to Wealth

    The most successful Retirement Income Ladder Strategy is one that balances stability, flexibility, and long-term growth. Small improvements today can make a significant difference to retirement income security over the coming decades.

    In the final section, we’ll discuss future retirement income trends, answer common questions, and summarize how retirees can use ladder strategies to create dependable retirement cash flow.

    The Future of Retirement Income Ladders in 2026 and Beyond

    The retirement landscape is changing rapidly. Rising life expectancy, evolving interest rates, inflation concerns, and advances in financial technology are encouraging retirees to rethink how they generate income.

    As a result, the Retirement Income Ladder Strategy is becoming increasingly popular among retirees who want predictable cash flow without depending entirely on stock market performance.

    While bond ladders and CD ladders have existed for decades, modern retirees are combining them with dividend portfolios, broad-market index funds, and cash reserves to create more flexible retirement income plans.

    The future of retirement income will likely focus on diversification, income stability, and personalized planning rather than relying on a single investment strategy.

    How AI Is Transforming Retirement Planning

    Artificial intelligence is beginning to play a larger role in retirement income planning.

    AI-powered tools can analyze spending habits, evaluate withdrawal strategies, estimate future retirement income needs, and identify portfolio risks.

    Investors interested in these technologies should review our

    AI Investing Guide 2026
    .

    While technology cannot eliminate investment risk, it can help retirees make more informed financial decisions.

    Frequently Asked Questions

    1. What is a Retirement Income Ladder Strategy?

    A Retirement Income Ladder Strategy uses investments with staggered maturity dates to create predictable retirement income over time.

    2. Are bond ladders good for retirees?

    Many retirees use bond ladders because they provide scheduled cash flow and help reduce interest-rate risk.

    3. Can I combine a ladder strategy with dividend investing?

    Yes. Many retirees combine bond ladders and dividend portfolios to balance income stability and long-term growth.

    4. How often should I review my retirement ladder?

    At least once per year. Regular reviews help ensure the ladder remains aligned with retirement goals and market conditions.

    5. Is a ladder strategy better than the 4% rule?

    Not necessarily. Both approaches have strengths. Many retirees use ladder strategies alongside withdrawal plans and dividend income strategies.

    Conclusion

    A Retirement Income Ladder Strategy can provide structure, predictability, and financial confidence throughout retirement.

    By spreading investments across multiple maturity dates, retirees can create dependable cash flow while reducing exposure to market volatility.

    Many successful retirees combine ladders with dividend income, growth investments, and emergency cash reserves to create a balanced retirement income plan.

    If you’re building a complete retirement roadmap, don’t miss our

    Retirement Planning Guide for Americans in 2026
    .

    With proper planning, diversification, and regular portfolio reviews, a Retirement Income Ladder Strategy can help support your lifestyle for decades while preserving long-term financial security.

    📩 Join Our Retirement Income Newsletter

    Get retirement planning tips, income strategies, dividend investing ideas, and wealth-building insights delivered directly to your inbox.

    Stay informed. Build reliable retirement income. Retire with confidence.


    👨‍💼 About the Author

    Subhash Rukade is the founder of FinanceInvestment.site and writes about retirement planning, dividend investing, passive income, personal finance, and wealth building. His mission is to help American investors make smarter financial decisions and create long-term financial security.

  • How to Create a Retirement Paycheck From Investments in 2026: A Complete Income Strategy Guide

    How to Create a Retirement Paycheck From Investments in 2026: A Complete Income Strategy Guide


    How to Create a Retirement Paycheck From Investments in 2026

    Author: Subhash Rukade

    Published: June 20, 2026

    Retirement Paycheck From Investments

    Why Every Retiree Needs a Retirement Paycheck

    Creating a retirement paycheck from investments is one of the most important financial goals for Americans approaching retirement in 2026. During your working years, a paycheck arrives regularly from an employer. Retirement changes that completely. Instead of relying on salary income, retirees must depend on Social Security, investment income, savings, and retirement accounts to cover everyday expenses.

    Unfortunately, many retirees enter retirement without a clear income strategy. They may have substantial savings but no structured plan for turning those assets into predictable monthly cash flow.

    That is where a retirement paycheck becomes essential.

    A retirement paycheck is a system that converts investments into consistent income. The goal is simple: create dependable monthly cash flow while protecting your portfolio from running out of money too early.

    Successful retirees often combine multiple income sources. These may include dividend-paying stocks, bonds, retirement accounts, interest income, and Social Security benefits. When these sources work together, they can provide financial stability and peace of mind throughout retirement.

    If you’re building a complete retirement strategy, start with our

    Retirement Planning Guide for Americans in 2026
    .
    This pillar guide explains the foundation of retirement investing, income planning, and wealth preservation.

    The good news is that creating a retirement paycheck from investments does not require a multi-million-dollar portfolio. Even investors with moderate retirement savings can build sustainable income streams using proven strategies.

    In this guide, you’ll learn how retirement paychecks work, which investments can generate income, common mistakes to avoid, and practical ways to create reliable cash flow throughout retirement.

    By the end of this article, you’ll have a clear roadmap for transforming your retirement portfolio into an income-producing machine that supports your lifestyle for decades.

    The Building Blocks of a Retirement Paycheck From Investments

    A successful retirement paycheck from investments is rarely built from a single income source. Most financially secure retirees combine multiple streams of income to create predictable monthly cash flow while reducing risk.

    Think of retirement income as a table. If one leg becomes weak, the other legs help keep everything stable. The more diversified your income sources are, the more reliable your retirement paycheck can become.

    1. Social Security: The Foundation of Retirement Income

    For millions of Americans, Social Security provides the first layer of retirement income. While Social Security alone may not cover all living expenses, it creates a dependable monthly payment that continues throughout retirement.

    Many retirees use Social Security to cover essential expenses such as housing, utilities, groceries, and healthcare costs.

    2. Dividend Income

    Dividend-paying stocks can provide regular cash flow without requiring investors to sell shares.

    Many retirees prefer dividend investing because it creates income while allowing their portfolios to continue growing over time.

    To learn more, read our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource for retirement income ideas.

    3. Bond Income

    Bonds can provide predictable interest payments and help reduce portfolio volatility.

    Many retirees use Treasury bonds, municipal bonds, and high-quality corporate bonds as part of their retirement income strategy.

    A bond ladder can further improve income stability by spreading bond maturities across multiple years.

    4. Interest Income and Cash Reserves

    High-yield savings accounts, certificates of deposit (CDs), and money market accounts can generate additional income while preserving capital.

    Although these investments typically offer lower returns than stocks, they provide valuable liquidity and emergency funds.

    Why Multiple Income Sources Matter

    The goal is not to find one perfect investment. The goal is to build a retirement paycheck from investments that can continue paying you through different market environments.

    When Social Security, dividends, bonds, and cash reserves work together, retirees often experience greater financial confidence and flexibility.

    In the next section, we’ll build a retirement paycheck step-by-step and calculate how much monthly income a retirement portfolio can realistically generate.

    How to Build a Retirement Paycheck Step by Step

    Once you understand the income sources available during retirement, the next step is combining them into a structured income plan. A successful retirement paycheck from investments should provide reliable monthly cash flow while protecting your portfolio from unnecessary risk.

    The objective is simple: replace your employment paycheck with investment income and retirement assets.

    Step 1: Calculate Your Monthly Retirement Expenses

    Start by estimating your retirement spending needs.

    Include:

    • Housing costs
    • Utilities
    • Healthcare expenses
    • Food and groceries
    • Insurance premiums
    • Travel and entertainment
    • Emergency expenses

    Suppose your estimated retirement budget is $5,000 per month.

    That means you need approximately $60,000 annually to support your lifestyle.

    Step 2: Subtract Guaranteed Income Sources

    Next, determine how much income will come from Social Security and other guaranteed sources.

    Example:

    • Social Security Income = $2,500/month
    • Annual Social Security Income = $30,000

    If your retirement spending target is $60,000 annually, your investments must generate the remaining $30,000.

    Step 3: Calculate Portfolio Income Needs

    Using the popular 4% withdrawal guideline:

    Required Portfolio = $30,000 ÷ 0.04

    Required Portfolio = $750,000

    This simple calculation gives retirees a starting point for retirement income planning.

    Retirement Paycheck Examples

    • $500,000 Portfolio → Approximately $20,000 Annual Income (4%)
    • $1,000,000 Portfolio → Approximately $40,000 Annual Income (4%)
    • $2,000,000 Portfolio → Approximately $80,000 Annual Income (4%)

    Monthly Retirement Income Example

    Let’s assume a retiree has:

    • Social Security: $2,500/month
    • Dividend Income: $800/month
    • Portfolio Withdrawals: $1,700/month

    Total Retirement Paycheck:

    $5,000 Per Month

    This structure creates a predictable retirement paycheck without relying entirely on portfolio withdrawals.

    Many retirees also combine dividend investing with withdrawal strategies to improve income stability. Diversified income sources often provide greater flexibility during market downturns.

    The most successful retirement paycheck from investments is designed to survive both strong markets and difficult economic periods.

    In the next section, we’ll compare the most popular retirement income strategies and analyze a real-world case study showing how retirees generate monthly income from a $1 million portfolio.

    Best Retirement Income Strategies Compared

    There is no single way to create a retirement paycheck from investments. Some retirees prefer dividend income, others rely on portfolio withdrawals, and many use a combination of strategies.

    The best approach depends on your retirement goals, risk tolerance, portfolio size, and income needs.

    Let’s compare the most popular retirement income strategies used by American retirees in 2026.

    Retirement Income Strategy Comparison

    StrategyIncome StabilityGrowth PotentialRisk Level
    Dividend InvestingHighModerateModerate
    Bond LadderHighLowLow
    Portfolio WithdrawalsModerateHighModerate
    Hybrid StrategyHighHighModerate

    Dividend Income Strategy

    Dividend investing remains one of the most popular methods for generating retirement income.

    Instead of selling investments every month, retirees collect cash payments from dividend-paying companies.

    This strategy may help preserve portfolio assets while providing consistent income.

    Investors interested in building a dividend-based retirement paycheck should review our

    How to Build a Dividend Portfolio

    guide.

    Bond Ladder Strategy

    Bond ladders create predictable income by holding bonds with different maturity dates.

    As bonds mature, retirees can use the proceeds for living expenses or reinvest them into new bonds.

    This approach often appeals to conservative investors seeking income stability.

    Hybrid Retirement Income Strategy

    Many financial planners favor a hybrid approach.

    This strategy combines Social Security, dividend income, bond income, and carefully planned withdrawals.

    The result is a diversified retirement paycheck that does not depend entirely on any one income source.

    Real-World Retirement Case Study

    Consider a retired couple with a $1 million portfolio.

    • 40% Dividend Stocks
    • 30% Bonds
    • 20% Broad Market Index Funds
    • 10% Cash Reserves

    Their annual retirement income looks like this:

    • Social Security: $32,000
    • Dividend Income: $12,000
    • Bond Interest: $6,000
    • Portfolio Withdrawals: $10,000

    Total Retirement Income:
    $60,000 Per Year

    Because income comes from multiple sources, they are less vulnerable to market downturns.

    For a complete retirement roadmap, review our

    Retirement Planning Guide for Americans in 2026
    .

    This example highlights an important lesson: a successful retirement paycheck from investments is usually built through diversification rather than relying on a single strategy.

    In the next section, we’ll examine the biggest retirement paycheck mistakes that can reduce income and increase financial stress during retirement.

    Common Mistakes That Can Destroy Your Retirement Paycheck

    Building a retirement paycheck from investments takes years of planning. Unfortunately, even a well-designed retirement income strategy can fail if common mistakes are ignored.

    Many retirees focus on growing their portfolios but spend very little time managing retirement income. As a result, avoidable mistakes can reduce cash flow, increase financial stress, and shorten portfolio life expectancy.

    The good news is that most of these problems can be prevented with proper planning.

    Mistake #1: Ignoring Inflation

    Inflation remains one of the biggest threats to retirement income.

    A retiree earning $60,000 annually today may need significantly more income ten or twenty years from now to maintain the same lifestyle.

    Healthcare, food, insurance, and housing expenses tend to rise over time.

    This is why retirement portfolios often need some exposure to growth investments even after retirement begins.

    Mistake #2: Overspending During Strong Markets

    Bull markets often make retirees feel wealthier.

    When portfolio balances rise, some investors increase spending too aggressively.

    The problem is that markets rarely move upward forever.

    Higher spending during strong years can create challenges when markets eventually decline.

    Mistake #3: Failing to Prepare for Market Downturns

    Every retirement plan should include a strategy for recessions and market corrections.

    Retirees who panic and sell investments during downturns may permanently damage portfolio performance.

    Investors looking for defensive strategies should read our

    Recession-Proof Investing 2026

    guide.

    Mistake #4: Ignoring New Planning Tools

    Technology is rapidly changing retirement planning.

    Modern AI tools can help investors monitor portfolios, analyze risk levels, and improve retirement income projections.

    To learn more, explore our

    AI Investing Guide 2026
    .

    Mistake #5: Lack of Diversification

    Some retirees rely too heavily on one stock, one fund, or one income source.

    A diversified retirement paycheck from investments usually combines Social Security, dividends, bonds, cash reserves, and portfolio withdrawals.

    Diversification can help reduce risk while improving income stability.

    Mistake #6: No Emergency Cash Reserve

    Unexpected expenses are inevitable.

    Medical bills, home repairs, and family emergencies can force retirees to sell investments at the wrong time.

    Maintaining cash reserves helps protect long-term retirement income plans.

    The strongest retirement paycheck from investments is not necessarily the highest-paying one. It is the paycheck that can survive inflation, market volatility, and unexpected life events while continuing to provide reliable income year after year.

    In the next section, we’ll look at practical strategies that can help retirees strengthen retirement income and improve long-term financial security.

    Practical Tips for Creating a Reliable Retirement Paycheck

    A successful retirement paycheck from investments is not created by chance. It requires planning, discipline, and a strategy that balances income, growth, and risk management.

    Fortunately, several practical techniques can help retirees improve cash flow while protecting long-term financial security.

    1. Build Multiple Income Streams

    The most financially secure retirees rarely depend on a single source of income.

    Instead, they combine Social Security, dividend income, bond interest, retirement account withdrawals, and cash reserves.

    This diversification helps create a more stable retirement paycheck and reduces dependence on market performance.

    2. Maintain a Cash Reserve

    Keeping one to three years of essential expenses in cash can help retirees avoid selling investments during market downturns.

    Cash reserves act as a financial buffer when markets become volatile.

    3. Focus on Quality Dividend Investments

    Dividend-paying companies can provide regular income while still offering long-term growth potential.

    Many retirees use dividend portfolios to supplement Social Security and reduce withdrawal pressure on retirement accounts.

    4. Review Your Retirement Plan Annually

    Retirement is not a set-it-and-forget-it process.

    Income needs, inflation rates, healthcare costs, and market conditions change over time. Reviewing your retirement paycheck strategy at least once per year helps ensure that your plan remains aligned with your goals.

    Retirement Income Checklist

    StrategyImportance
    Diversified Income SourcesHigh
    Emergency Cash ReserveHigh
    Dividend IncomeHigh
    Annual Portfolio ReviewHigh
    Inflation ProtectionEssential

    Trusted Retirement Resources

    Recommended Retirement Books


    The Bogleheads’ Guide to Retirement Planning


    The Simple Path to Wealth


    The Intelligent Investor

    The strongest retirement paycheck from investments is built through preparation, diversification, and consistent decision-making. Small improvements today can create significant financial benefits throughout retirement.

    In the final section, we’ll explore future retirement income trends, answer common questions, and summarize the key steps for building a dependable retirement paycheck in 2026.

    The Future of Retirement Income in 2026 and Beyond

    Retirement planning continues to evolve. Today’s retirees have access to tools, investment options, and financial resources that previous generations could only imagine.

    As retirement continues to change, the concept of a retirement paycheck from investments is becoming more personalized and flexible.

    Instead of relying solely on traditional withdrawal rules, many retirees now combine dividend income, bond income, cash reserves, Social Security, and technology-driven planning tools to create sustainable retirement income.

    How AI Is Changing Retirement Planning

    Artificial intelligence is becoming an important retirement planning tool.

    Modern platforms can analyze spending patterns, estimate retirement income needs, monitor portfolios, and help retirees make better financial decisions.

    Investors who want to learn more about this growing trend should explore our

    AI Investing Guide 2026
    .

    While AI will not replace good financial judgment, it can help retirees make more informed decisions and improve long-term retirement outcomes.

    Frequently Asked Questions

    1. What is a retirement paycheck?

    A retirement paycheck is a structured income plan that converts retirement assets into predictable monthly cash flow after leaving the workforce.

    2. How much money do I need to create a retirement paycheck?

    The amount depends on your lifestyle, retirement goals, Social Security benefits, and withdrawal strategy. Many retirees target annual income equal to 70%–80% of their pre-retirement earnings.

    3. Are dividend stocks good for retirement income?

    Many retirees use dividend-paying stocks because they can generate regular income while still offering long-term growth potential.

    4. Should retirees keep cash reserves?

    Yes. Maintaining cash reserves can help cover unexpected expenses and reduce the need to sell investments during market downturns.

    5. How often should I review my retirement income plan?

    Most financial professionals recommend reviewing retirement income strategies at least once per year.

    Conclusion

    Creating a retirement paycheck from investments is one of the most important steps toward financial independence during retirement.

    A successful retirement income plan combines multiple income sources, manages risk carefully, and adapts to changing market conditions.

    Whether your retirement income comes from Social Security, dividend stocks, bonds, portfolio withdrawals, or a combination of strategies, the goal remains the same: generate dependable income while preserving long-term wealth.

    If you are building a complete retirement roadmap, don’t miss our

    Retirement Planning Guide for Americans in 2026
    .

    With proper planning, disciplined investing, and consistent reviews, your retirement portfolio can become a reliable paycheck that supports your lifestyle for decades.

    📩 Join Our Retirement Newsletter

    Get retirement planning tips, investing strategies, dividend income ideas, and wealth-building insights delivered directly to your inbox.

    Stay informed. Stay prepared. Retire with confidence.


    👨‍💼 About the Author

    Subhash Rukade is the founder of FinanceInvestment.site and writes about retirement planning, dividend investing, passive income, personal finance, and long-term wealth building. His goal is to help everyday Americans make smarter money decisions and create lasting financial security.

  • Safe Withdrawal Rate in 2026: 3%, 4%, or 5%? The Complete Retirement Income Guide

    Safe Withdrawal Rate in 2026: 3%, 4%, or 5%? The Complete Retirement Income Guide


    Safe Withdrawal Rate in 2026: 3%, 4%, or 5%?

    Author: Subhash Rukade

    Published: June 20, 2026

    Safe Withdrawal Rate 2026

    Why the Safe Withdrawal Rate in 2026 Matters More Than Ever

    Safe Withdrawal Rate 2026 is one of the most important topics for retirees planning their retirement income. Choosing between a 3%, 4%, or 5% withdrawal rate can significantly affect how long your retirement savings last and how much income you can safely generate throughout retirement.

    For decades, many financial planners relied on the famous 4% rule. The idea was simple. Retirees could withdraw 4% of their portfolio during the first year of retirement and then adjust that amount for inflation each year. Historically, this approach worked reasonably well for many investors.

    However, retirement planning in 2026 looks very different. Inflation spikes, changing interest rates, and longer life expectancies have sparked a new debate. Should retirees use a conservative 3% withdrawal rate? Is the traditional 4% rule still reliable? Or can some investors safely withdraw 5%?

    The answer depends on several factors. Portfolio size, investment allocation, retirement age, health conditions, and income sources such as Social Security all play a role.

    Before deciding on a withdrawal strategy, it is important to build a strong retirement foundation. If you have not already done so, read our comprehensive
    Retirement Planning Guide for Americans in 2026.
    This pillar guide explains retirement investing, income planning, tax strategies, and long-term wealth preservation.

    Modern retirees also have access to new planning tools. Artificial intelligence is helping investors analyze risk and improve decision-making. You can learn more in our
    AI Investing Guide 2026.

    In this article, we will compare the 3%, 4%, and 5% withdrawal rules. We will look at real-world examples, retirement income strategies, portfolio risks, common mistakes, and future retirement trends. By the end, you will have a much clearer idea of which withdrawal rate may fit your retirement goals in 2026.

    The goal is not simply to maximize income today. The goal is to create a retirement paycheck that can support your lifestyle for decades while protecting the wealth you worked so hard to build.

    Understanding the 3%, 4%, and 5% Withdrawal Rules

    To understand the Safe Withdrawal Rate in 2026, it helps to know where the popular withdrawal rules came from.

    The most widely known strategy is the 4% rule. It originated from retirement research that analyzed historical market performance and portfolio survival rates. The goal was simple: determine how much retirees could withdraw each year without running out of money during a 30-year retirement.

    The Safe Withdrawal Rate 2026 debate continues to be one of the most important retirement planning discussions for American retirees.

    For many years, the 4% rule became a standard retirement planning guideline. However, changing market conditions and increasing life expectancy have caused many investors to reconsider whether 4% remains the ideal withdrawal rate.

    The 3% Withdrawal Rule

    The 3% withdrawal strategy is considered the most conservative option.

    Retirees who use this approach withdraw less money each year, which can increase the likelihood that their portfolio survives longer market downturns and extended retirement periods.

    The downside is lower annual income. Some retirees may find that a 3% withdrawal rate does not provide enough spending flexibility.

    The 4% Withdrawal Rule

    The traditional 4% rule attempts to balance income and portfolio preservation.

    For many retirees, it offers a reasonable compromise between maintaining lifestyle needs and protecting long-term retirement assets.

    This strategy remains popular because it has historically worked across many different market environments.

    The 5% Withdrawal Rule

    The 5% strategy generates higher retirement income immediately.

    Retirees with larger portfolios often find this approach attractive because it increases available cash flow. However, higher withdrawals also increase the risk of portfolio depletion during prolonged market declines.

    Investors considering a 5% withdrawal rate should carefully evaluate risk tolerance, retirement duration, and alternative income sources.

    Which Withdrawal Rate Is Best?

    There is no universal answer.

    A retiree with strong dividend income, Social Security benefits, and a diversified portfolio may be comfortable with a different withdrawal rate than someone relying entirely on investment withdrawals.

    That is why the Safe Withdrawal Rate in 2026 should be viewed as a personalized decision rather than a fixed rule.

    In the next section, we will compare exactly how much retirement income a portfolio can generate using the 3%, 4%, and 5% withdrawal strategies.

    Safe Withdrawal Rate 2026: Understanding the 3%, 4%, and 5% Rules

    Understanding percentages is helpful, but most retirees want to know how withdrawal rates translate into actual dollars. This section of our Safe Withdrawal Rate in 2026 guide shows how different portfolio sizes perform under the 3%, 4%, and 5% withdrawal strategies.

    The Safe Withdrawal Rate 2026 debate continues to be one of the most important retirement planning discussions for American retirees.

    The difference between these withdrawal rates may seem small. However, over a 20- to 30-year retirement, even a 1% change can significantly impact portfolio longevity and retirement income.

    Retirement Income Comparison Table

    Portfolio Size3% Withdrawal4% Withdrawal5% Withdrawal
    $250,000$7,500/year$10,000/year$12,500/year
    $500,000$15,000/year$20,000/year$25,000/year
    $1,000,000$30,000/year$40,000/year$50,000/year
    $2,000,000$60,000/year$80,000/year$100,000/year

    Retirement Income Calculator Example

    Suppose a retiree has a portfolio worth $1 million.

    • 3% Rule = $30,000 annual income
    • 4% Rule = $40,000 annual income
    • 5% Rule = $50,000 annual income

    At first glance, the 5% withdrawal strategy appears attractive because it provides an additional $20,000 per year compared to the 3% rule.

    However, the higher withdrawal amount may increase the risk of depleting retirement assets during periods of market weakness.

    Inflation Makes a Big Difference

    Inflation is one of the biggest threats to retirement income.

    A retiree withdrawing $40,000 today may need significantly more income ten or twenty years from now to maintain the same purchasing power.

    This is why many retirees combine withdrawal strategies with dividend investing and long-term growth investments.

    Investors interested in generating additional retirement income should read our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource for dividend income opportunities.

    The best Safe Withdrawal Rate in 2026 is often the one that balances current income needs with long-term portfolio survival. In the next section, we’ll examine a real-world retirement case study and see how different withdrawal rates affect actual retirees.

    Real-World Case Study: Which Withdrawal Rate Works Best in Retirement?

    Understanding retirement withdrawal strategies becomes much easier when we look at a real-world example. This case study shows how different withdrawal rates can affect retirement income and long-term portfolio sustainability.

    The purpose of this example is not to identify a perfect strategy. Instead, it demonstrates how the Safe Withdrawal Rate in 2026 depends on personal circumstances, market conditions, and retirement goals.

    Meet Robert and Linda

    Robert is 66 and Linda is 64. They recently retired after working for more than 35 years.

    Their financial situation looks like this:

    • Retirement Portfolio: $1,000,000
    • Social Security Income: $32,000 per year
    • Mortgage: Paid Off
    • Emergency Fund: $50,000
    • Desired Retirement Spending: $75,000 per year

    Because Social Security covers only part of their expenses, they need their investment portfolio to generate additional retirement income.

    Scenario 1: Using the 3% Withdrawal Rule

    A 3% withdrawal rate generates approximately $30,000 annually from their portfolio.

    Combined with Social Security, total retirement income equals about $62,000 per year.

    While this approach offers strong portfolio protection, it falls short of their desired spending target.

    Scenario 2: Using the 4% Withdrawal Rule

    The traditional 4% rule provides approximately $40,000 annually.

    Combined with Social Security, total income increases to roughly $72,000 per year.

    This amount comes much closer to their retirement income goal while maintaining a reasonable balance between spending and portfolio preservation.

    Scenario 3: Using the 5% Withdrawal Rule

    A 5% withdrawal rate produces approximately $50,000 annually.

    Combined retirement income rises to about $82,000 per year.

    Although this provides greater spending flexibility, it also increases the risk of portfolio depletion during prolonged market downturns.

    Portfolio Allocation Matters

    Robert and Linda maintain a diversified retirement portfolio:

    • 55% Stocks
    • 30% Bonds
    • 10% Dividend Investments
    • 5% Cash Reserves

    This allocation helps balance growth, income generation, and risk management.

    Investors concerned about market downturns should also read our

    Recession-Proof Investing 2026

    guide.

    Technology is also helping retirees evaluate withdrawal strategies more effectively. Our

    AI Investing Guide 2026

    explains how modern tools can support retirement decision-making.

    This case study highlights an important lesson: the best Safe Withdrawal Rate in 2026 is not necessarily the highest one. It is the rate that provides enough income while preserving financial security throughout retirement.

    In the next section, we’ll explore the most common withdrawal mistakes retirees make and how to avoid them.

    Common Withdrawal Mistakes That Can Damage Retirement Income

    Even the best retirement portfolio can struggle if withdrawals are not managed carefully. Many retirees focus on investment performance but overlook spending habits and withdrawal decisions.Safe Withdrawal Rate 2026

    Choosing the right Safe Withdrawal Rate 2026 depends on portfolio size, retirement age, and expected investment returns.

    That is why understanding common mistakes is an important part of choosing the right Safe Withdrawal Rate in 2026.

    Most retirement income problems do not happen overnight. They develop gradually through a series of small financial decisions that compound over time.

    Mistake #1: Ignoring Inflation

    One of the most common retirement mistakes is underestimating inflation.

    A retiree may feel comfortable withdrawing $40,000 annually today. However, rising prices can reduce purchasing power significantly over the next 10 to 20 years.

    Healthcare, housing, insurance, and food costs often increase faster than expected.

    A successful retirement plan should include investments that have the potential to grow alongside inflation.

    Mistake #2: Increasing Withdrawals During Bull Markets

    Strong markets can create a false sense of security.

    When portfolios grow rapidly, some retirees increase spending and withdrawals beyond sustainable levels.

    Unfortunately, market conditions can change quickly.

    Excessive withdrawals during good years may reduce financial flexibility during future downturns.

    Mistake #3: Poor Diversification

    Many retirees hold too much money in a single investment, sector, or asset class.

    Concentrated portfolios often experience larger losses during market corrections.

    Diversification across stocks, bonds, dividend investments, and cash reserves can improve long-term portfolio stability.

    Mistake #4: No Emergency Cash Reserve

    Unexpected expenses are inevitable.

    Medical bills, home repairs, family emergencies, and vehicle replacements can force retirees to sell investments at unfavorable times.

    Maintaining a dedicated emergency fund helps reduce this risk.

    Mistake #5: Using Credit to Support Retirement Spending

    Some retirees rely heavily on credit cards when investment income falls short.

    While credit can provide short-term flexibility, excessive debt may place unnecessary pressure on retirement finances.

    Investors evaluating financial products can review our

    Best Credit Cards 2026

    guide.

    Mistake #6: Stopping Investments Too Early

    Many retirees believe investing ends once retirement begins.

    In reality, retirement portfolios often need continued growth to combat inflation and support long-term income needs.

    Investors interested in disciplined long-term investing strategies can explore our

    SIP Investing Guide 2026
    .

    The key lesson is simple: the best Safe Withdrawal Rate in 2026 cannot compensate for poor financial habits. Successful retirees combine smart withdrawal strategies with diversification, inflation protection, disciplined spending, and long-term planning.

    In the next section, we’ll explore practical retirement income strategies that can help retirees increase cash flow while reducing portfolio risk.

    Practical Retirement Income Strategies for 2026

    Choosing the right Safe Withdrawal Rate in 2026 is important, but withdrawal rates alone do not determine retirement success. The most financially secure retirees often combine multiple income strategies to create stable cash flow while protecting their portfolios.

    Many investors use the Safe Withdrawal Rate 2026 framework to estimate how much income their portfolio can safely generate.

    A diversified retirement income plan can reduce dependence on any single asset class and improve long-term financial flexibility.

    Dividend Income Strategy

    Dividend investing remains one of the most popular retirement income approaches.Safe Withdrawal Rate 2026

    Instead of selling shares regularly, retirees can collect dividend payments from high-quality companies and income-focused funds.

    This approach may help preserve capital while generating consistent cash flow.

    Investors interested in this strategy should review our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource.

    Bond Ladder Strategy

    Many retirees use bond ladders to create predictable income.

    A bond ladder consists of bonds with different maturity dates. As bonds mature, the proceeds can be used for retirement expenses or reinvested.Safe Withdrawal Rate 2026

    This strategy may reduce interest-rate risk while providing dependable income streams.

    Bucket Strategy

    The bucket strategy separates retirement assets into different categories based on time horizons.

    • Short-Term Bucket: Cash and money market funds
    • Medium-Term Bucket: Bonds and income investments
    • Long-Term Bucket: Stocks and growth investments

    This approach can help retirees avoid selling growth assets during market downturns.

    Dynamic Withdrawal Strategy

    Rather than withdrawing the same percentage every year, some retirees adjust withdrawals based on portfolio performance.Safe Withdrawal Rate 2026

    When markets perform well, withdrawals may increase modestly. During weaker markets, spending adjustments can help preserve portfolio longevity.

    Retirement Strategy Comparison

    StrategyRisk LevelIncome Stability
    Dividend IncomeModerateHigh
    Bond LadderLowHigh
    Bucket StrategyModerateHigh
    Dynamic WithdrawalsModerateVariable

    Trusted Retirement Resources

    📘 Recommended Retirement Book


    The Bogleheads’ Guide to Retirement Planning

    This book covers retirement investing, withdrawal strategies, tax planning, and portfolio management in a practical and easy-to-understand format.

    The best Safe Withdrawal Rate in 2026 often works alongside a broader retirement income strategy. Combining dividend income, bond ladders, cash reserves, and disciplined withdrawals can help retirees maintain income while reducing long-term portfolio risk.

    Future Retirement Trends, FAQ, and Final Thoughts

    The retirement landscape is changing rapidly. Longer life expectancy, evolving investment markets, and new technology are reshaping how Americans prepare for retirement.

    Is the Safe Withdrawal Rate 2026 still based on the 4% rule?

    As we move further into 2026 and beyond, many retirees are shifting away from rigid retirement rules and adopting more flexible income strategies. Rather than relying solely on the traditional 4% rule, investors are increasingly using dynamic withdrawal methods, dividend income, and personalized retirement planning.

    Technology is also becoming a valuable retirement tool. Artificial intelligence can help investors monitor portfolios, analyze risk, and identify opportunities to improve retirement income.

    If you want a broader understanding of retirement investing and long-term financial security, be sure to read our

    Retirement Planning Guide for Americans in 2026
    .

    Frequently Asked Questions

    1. Is the 4% rule still safe in 2026?

    For many retirees, the 4% rule remains a useful guideline. However, portfolio size, market conditions, inflation, and retirement length should all be considered before choosing a withdrawal rate.

    2. Is a 3% withdrawal rate too conservative?

    Not necessarily. A 3% withdrawal rate may provide greater portfolio protection, especially for retirees expecting a long retirement.

    3. Can I use a 5% withdrawal rate?

    Some retirees can sustain a 5% withdrawal rate, particularly if they have additional income sources. However, the risk of running out of money increases.

    4. What investments work best for retirement income?

    Dividend stocks, bonds, income-focused ETFs, and diversified portfolios are commonly used retirement income investments.

    5. How often should retirees review withdrawal strategies?

    At least once per year. Portfolio performance, inflation, and spending needs can change over time.

    Conclusion

    The best Safe Withdrawal Rate in 2026 depends on your goals, risk tolerance, portfolio structure, and retirement income needs.

    The Safe Withdrawal Rate 2026 is not a one-size-fits-all solution. Every retiree should evaluate their goals, risk tolerance, and income needs before selecting a withdrawal strategy.

    A 3% withdrawal rate prioritizes safety. A 4% withdrawal rate balances income and portfolio preservation. A 5% withdrawal rate provides higher income but carries greater long-term risk.

    The most successful retirees focus on flexibility rather than following a single rule forever. By combining smart withdrawals, diversified investments, dividend income, and disciplined spending, investors can improve their chances of achieving lasting financial security.

    📩 Free Retirement Newsletter

    Get retirement income strategies, investing ideas, Social Security updates, and wealth-building tips delivered directly to your inbox.

    Join thousands of investors preparing for a smarter retirement.


    👨‍💼 Subhash Rukade

    Personal Finance & Retirement Writer | Helping Americans build retirement income, grow wealth, and make smarter investing decisions for a secure financial future.

  • Retirement Planning Guide for Americans in 2026: Build Wealth, Generate Income, and Retire With Confidence

    Retirement Planning Guide for Americans in 2026: Build Wealth, Generate Income, and Retire With Confidence


    Retirement Planning Guide for Americans in 2026

    Author: Subhash Rukade

    Published: June 19, 2026

    Retirement Planning Guide

    Why Retirement Planning Matters More Than Ever in 2026

    A comfortable retirement rarely happens by chance. It is usually the result of years of saving, investing, and making smart financial decisions. That is why following a reliable Retirement Planning Guide is more important than ever for Americans in 2026.

    The retirement landscape has changed dramatically over the last decade. Inflation continues to affect everyday expenses, healthcare costs remain high, and people are living longer lives. While longer life expectancy is positive, it also means retirement savings may need to support 25 to 35 years of living expenses.

    Many Americans still believe Social Security will provide enough income during retirement. However, for most households, Social Security replaces only a portion of pre-retirement income. Investors often need additional retirement income sources such as 401(k) plans, IRAs, dividend-paying investments, taxable brokerage accounts, and personal savings.

    Fortunately, building retirement wealth is more accessible than ever. Low-cost investment platforms, retirement accounts, and financial education resources allow investors to create long-term wealth without needing large amounts of capital to get started.

    Technology is also transforming retirement planning. Artificial intelligence is helping investors analyze portfolios, monitor retirement goals, and make more informed decisions. Readers interested in this growing trend should explore our
    AI Investing Guide 2026.

    One of the most common retirement mistakes is delaying the planning process. Many people assume retirement preparation can wait until their 50s. In reality, time is one of the most valuable assets an investor has because of compound growth.

    Even modest monthly contributions can grow substantially over decades. Consistent investing often matters more than trying to find the perfect investment.

    This Retirement Planning Guide will walk you through retirement savings goals, retirement income strategies, Social Security planning, portfolio allocation, tax-efficient investing, and wealth-preservation techniques designed specifically for Americans in 2026.

    Whether retirement is five years away or thirty years away, building a clear plan today can improve your financial confidence tomorrow.

    The ultimate goal of retirement planning is simple: create enough income-producing assets so your money continues working long after your career ends.

    How Much Money Do Americans Need to Retire Comfortably?

    One of the most common questions in any Retirement Planning Guide is simple: how much money is enough for retirement?

    The answer depends on lifestyle, location, healthcare expenses, inflation, and retirement goals. However, most financial experts agree that Americans should focus on building enough assets to replace a significant portion of their working income during retirement.

    A common guideline suggests retirees may need approximately 70% to 80% of their pre-retirement income each year. For example, if someone earns $100,000 annually before retirement, they may need between $70,000 and $80,000 per year during retirement.

    The exact number varies based on spending habits and financial obligations. Someone with a paid-off home and minimal debt may require less retirement income than someone with ongoing housing costs and higher living expenses.

    Retirement Savings Benchmarks by Age

    While every investor’s situation is different, many financial planners use age-based retirement savings benchmarks as a general guide.

    AgeSuggested Retirement Savings
    301× Annual Salary
    403× Annual Salary
    506× Annual Salary
    608× to 10× Annual Salary
    6710× to 12× Annual Salary

    Investors approaching retirement often wonder whether they are on track. Readers can explore our upcoming guide,

    How Much Should You Have in a 401(k) by Age 50?

    for a deeper breakdown of retirement savings targets.

    Retirement Calculator Example

    Suppose an investor wants to generate $60,000 per year during retirement.

    Using a 4% withdrawal strategy, the retirement portfolio target would be:

    $60,000 ÷ 0.04 = $1.5 Million

    This example illustrates why long-term saving and investing are so important. Retirement wealth is usually built over decades, not years.

    Factors That Impact Retirement Needs

    • Expected retirement age
    • Healthcare costs
    • Inflation rates
    • Social Security benefits
    • Housing expenses
    • Investment returns
    • Life expectancy

    A strong Retirement Planning Guide focuses on preparing for these variables rather than relying on one specific savings target.

    The goal is not simply accumulating a large portfolio. The goal is creating reliable retirement income that can support your lifestyle for decades while protecting purchasing power from inflation.

    The earlier investors begin planning, the more flexibility they typically have when retirement eventually arrives.

    Building a Retirement Paycheck: Creating Reliable Income After You Stop Working

    Saving for retirement is only half the challenge. The other half is turning those savings into dependable income. A successful Retirement Planning Guide focuses not only on building wealth but also on creating a retirement paycheck that can support your lifestyle for decades.

    Unlike traditional employment, retirement does not come with a regular paycheck from an employer. Instead, retirees must create their own income system using multiple sources.

    The most financially secure retirees often combine several income streams rather than relying on a single source.

    Common Retirement Income Sources

    • Social Security Benefits
    • 401(k) Withdrawals
    • Traditional IRA Distributions
    • Roth IRA Withdrawals
    • Dividend Income
    • Bond Interest
    • Rental Property Income
    • Part-Time Work
    • Annuities

    The goal is to create a steady stream of income that covers living expenses while preserving as much investment capital as possible.

    Creating a Retirement Paycheck Strategy

    Many retirees prefer a structured approach that mimics a traditional paycheck.

    Instead of withdrawing money randomly, investors can schedule monthly transfers from retirement accounts into a checking account. This creates predictable cash flow and makes budgeting easier.

    Readers interested in building a structured income plan can explore our upcoming guide:


    How to Create a Retirement Paycheck From Investments

    Dividend Income in Retirement

    Dividend-paying stocks remain one of the most popular retirement income strategies.

    Rather than selling investments every month, retirees can use dividend payments to generate cash flow while continuing to own the underlying assets.

    Investors looking to develop this strategy should read our

    How to Build a Dividend Portfolio

    guide.

    You can also review our

    Top Dividend Stocks USA 2026

    resource for additional ideas.

    Monthly Income Investments

    Many retirees prioritize investments that provide regular monthly income.

    These may include dividend-focused funds, bond funds, real estate investments, and income-oriented portfolios.

    Additional ideas will be covered in our upcoming guide:
    Best Monthly Income Investments for Retirees

    Balancing Growth and Income

    A common retirement mistake is focusing only on income and ignoring growth.

    Even during retirement, portfolios often need some exposure to growth investments to help offset inflation and maintain purchasing power.

    A strong Retirement Planning Guide balances current income needs with long-term portfolio growth. This approach can help retirees generate reliable income today while protecting financial security for the future.

    The next step is understanding how much money can safely be withdrawn from a retirement portfolio each year without running out of assets too early.

    Safe Withdrawal Strategies: How Much Can Retirees Spend Each Year?

    One of the biggest concerns retirees face is running out of money too early. After spending decades building savings, the challenge becomes turning those assets into reliable income without depleting the portfolio too quickly.

    This is where withdrawal strategies become an important part of every Retirement Planning Guide.

    A withdrawal strategy determines how much money retirees can safely take from their investment portfolio each year while maintaining long-term financial security.

    Financial experts have debated this topic for decades. While no withdrawal rate works perfectly for every retiree, several commonly used approaches can provide useful guidelines.

    The 3% Withdrawal Rule

    The 3% rule is considered the most conservative approach.

    Under this strategy, a retiree withdraws 3% of their portfolio annually.

    For example:

    Portfolio Value: $1,000,000

    Annual Withdrawal: $30,000

    This method offers greater protection against market downturns and longer retirement periods.

    The 4% Withdrawal Rule

    The 4% rule remains one of the most widely discussed retirement income strategies.

    With a $1 million portfolio, retirees could withdraw approximately $40,000 annually.

    Many retirement studies suggest this approach can support retirement income for approximately 30 years under various market conditions.

    A deeper analysis will be available in our upcoming guide:


    Safe Withdrawal Rate in 2026: 3%, 4%, or 5%?

    The 5% Withdrawal Rule

    A 5% withdrawal rate provides higher income but increases the risk of exhausting retirement assets.

    For a $1 million portfolio, annual withdrawals would equal $50,000.

    While attractive during strong market periods, this strategy may create challenges during extended market declines.

    Comparison Table: Withdrawal Strategies

    Withdrawal Rate$1 Million PortfolioRisk Level
    3%$30,000 per yearLow
    4%$40,000 per yearModerate
    5%$50,000 per yearHigher

    Factors That Influence Safe Withdrawals

    • Retirement age
    • Life expectancy
    • Investment allocation
    • Inflation rates
    • Healthcare expenses
    • Market performance
    • Social Security income

    Retirees with multiple income sources often have greater flexibility. Social Security benefits, dividend income, rental income, and part-time work can reduce pressure on investment portfolios.

    A successful Retirement Planning Guide focuses on sustainability rather than maximizing withdrawals. The objective is to create reliable retirement income that can support spending needs throughout retirement without sacrificing long-term financial security.

    Understanding withdrawal strategies is important, but retirement income planning becomes even more powerful when combined with an optimized Social Security strategy. For many Americans, Social Security remains one of the most valuable retirement assets available.

    Social Security Planning: Maximizing One of Your Most Valuable Retirement Benefits

    For millions of Americans, Social Security serves as the foundation of retirement income. While it may not cover all retirement expenses, it can provide a reliable source of lifetime income that helps reduce pressure on investment portfolios.

    That is why every comprehensive Retirement Planning Guide should include a clear Social Security strategy.

    The decisions you make regarding Social Security can impact your retirement income for decades. Claiming benefits too early may permanently reduce monthly payments, while delaying benefits can significantly increase lifetime income.
    How Working After Retirement Affects Social Security

    Choosing the Best Age to Claim Social Security

    One of the most important retirement decisions involves determining when to begin collecting Social Security benefits.

    Americans can generally start claiming benefits as early as age 62. However, doing so usually results in reduced monthly payments.

    Waiting until Full Retirement Age (FRA) or delaying benefits until age 70 can increase monthly income substantially.

    Readers who want a deeper analysis can explore our upcoming guide:

    Best Age to Claim Social Security Benefits in 2026

    Social Security and Married Couples

    Married couples often have additional planning opportunities.

    Spousal benefits, survivor benefits, and coordinated claiming strategies can significantly affect household retirement income.

    Proper planning may help maximize total lifetime benefits for both spouses.

    Additional strategies will be discussed in:

    Married Couples Social Security Strategy Guide for 2026

    Working After Retirement

    Many Americans continue working after claiming Social Security benefits.

    While this can provide additional income, earnings may temporarily affect benefits if claimed before reaching Full Retirement Age.

    Understanding these rules is important for avoiding unexpected surprises.

    Future readers can learn more through:

    Social Security Mistakes That Reduce Retirement Income

    Understanding COLA Adjustments

    Inflation can significantly impact retirement purchasing power over time.

    To help retirees keep pace with rising costs, Social Security benefits may receive annual Cost-of-Living Adjustments (COLA).

    Although COLA increases are helpful, they may not always fully offset inflation.

    More details will be covered in:

    Social Security COLA Changes and Retirement Planning

    How Social Security Fits Into Your Retirement Plan

    Social Security should be viewed as one component of a broader retirement strategy rather than the sole source of retirement income.

    Most retirees combine Social Security with retirement accounts, investment income, dividend-paying stocks, and personal savings.

    This diversified approach can improve financial security and reduce reliance on any single income source.

    A strong Retirement Planning Guide focuses on integrating Social Security into a larger retirement income plan. When combined with smart investing and disciplined savings, Social Security can help create a more stable and predictable financial future throughout retirement.

    401(k), IRA, and Roth Accounts: Building the Foundation of Retirement Wealth

    Retirement accounts play a central role in every successful Retirement Planning Guide. These accounts provide tax advantages, long-term growth opportunities, and a structured way to build wealth throughout your working years.

    For most Americans, retirement savings begin with employer-sponsored plans such as a 401(k) and later expand into Individual Retirement Accounts (IRAs). Understanding how these accounts work can help investors maximize retirement savings and potentially reduce taxes.

    Why 401(k) Plans Matter

    A 401(k) remains one of the most powerful retirement savings tools available.

    Contributions are often made directly from a paycheck, making investing automatic and consistent. Many employers also offer matching contributions, which can significantly increase retirement savings over time.

    Employer matching is essentially free money and should be prioritized whenever possible.

    Investors who want a detailed comparison can explore our upcoming guide:

    401(k) vs Roth IRA for Retirement in 2026

    Traditional IRA vs Roth IRA

    IRAs provide additional retirement savings opportunities outside employer-sponsored plans.

    A Traditional IRA may offer tax-deductible contributions, while a Roth IRA allows qualified withdrawals to be tax-free during retirement.

    Choosing between these accounts depends on factors such as current income, expected future tax rates, and retirement goals.

    A full comparison will be available in:

    Traditional IRA vs Roth IRA: Which Wins for Retirement?

    Catch-Up Contributions After Age 50

    Americans age 50 and older often have additional opportunities to accelerate retirement savings through catch-up contributions.

    These higher contribution limits allow older investors to strengthen retirement accounts during the final years of their careers.

    This strategy can be particularly valuable for individuals who started saving later than expected.

    Additional details will be covered in:

    Catch-Up Contributions Explained for Investors Over 50

    Roth Conversion Strategies

    Many retirees explore Roth conversions as part of their tax-planning strategy.

    Converting portions of a Traditional IRA into a Roth IRA may reduce future tax burdens and provide greater flexibility during retirement.

    However, conversions require careful planning because taxes may be owed during the conversion year.

    Readers interested in advanced retirement tax planning can explore:

    Best Roth Conversion Strategies to Maximize Retirement Savings

    Building Retirement Wealth Consistently

    The most important lesson is consistency.

    Investors who contribute regularly to retirement accounts often benefit from compound growth, market appreciation, and tax advantages over time.

    A strong Retirement Planning Guide does not focus on finding perfect investments. Instead, it emphasizes maximizing available retirement accounts, taking advantage of employer benefits, and maintaining a disciplined long-term investing strategy.

    For many Americans, retirement success begins with understanding how these accounts work and using them effectively throughout their careers.

    Retirement Tax Planning: Keeping More of Your Retirement Income

    Building retirement wealth is important, but keeping more of that wealth is equally important. Taxes can significantly affect retirement income, which is why tax planning should be a key part of every Retirement Planning Guide.

    Many retirees focus heavily on investment returns but overlook the impact taxes can have on withdrawals, Social Security benefits, and retirement accounts. A smart tax strategy can potentially increase the amount of money available throughout retirement without requiring additional investment risk.

    Why Retirement Tax Planning Matters

    Different retirement income sources are taxed differently.

    • Traditional 401(k) withdrawals are generally taxable.
    • Traditional IRA withdrawals are generally taxable.
    • Roth IRA qualified withdrawals are typically tax-free.
    • Dividend income may receive favorable tax treatment.
    • Social Security benefits may be partially taxable depending on income.

    Understanding how these income sources interact can help retirees reduce unnecessary tax burdens.

    Readers who want a complete framework can explore our upcoming guide:

    Retirement Tax Planning Checklist Every American Should Follow

    Reducing Taxes on Retirement Income

    One common strategy involves managing withdrawal timing.

    Rather than withdrawing large amounts from retirement accounts in a single year, retirees may benefit from spreading withdrawals across multiple years to remain in lower tax brackets.

    Strategic Roth conversions, dividend income, and taxable account withdrawals can also play important roles.

    More detailed strategies will be covered in:

    How to Reduce Retirement Income Taxes in 2026

    Reduce Taxes on Retirement Income: Smart Tax-Saving Strategies for 2026

    State Taxes Matter Too

    Federal taxes are only part of the equation.

    Some states tax retirement income heavily, while others provide favorable treatment for retirees. State tax differences can affect long-term retirement spending power.

    Investors considering relocation should review:
    State Taxes That Matter Most for Retirees

    Tax-Efficient Withdrawal Strategies

    The order in which retirees withdraw money from various accounts can influence total lifetime taxes.

    Many financial planners recommend coordinating withdrawals from taxable accounts, tax-deferred accounts, and tax-free accounts to improve tax efficiency.

    Future readers can learn more in:
    Retirement Tax Checklist for Americans

    Common Retirement Tax Mistakes

    • Ignoring Required Minimum Distributions (RMDs)
    • Withdrawing too much in a single year
    • Overlooking Roth conversion opportunities
    • Failing to consider state taxes
    • Ignoring Social Security tax implications

    A successful Retirement Planning Guide focuses not only on building retirement assets but also on managing taxes effectively. Small tax-saving decisions made each year can compound into significant savings throughout retirement.

    For many Americans, smart tax planning may be one of the easiest ways to improve retirement income without increasing investment risk.

    Building the Right Retirement Portfolio in 2026

    A retirement portfolio should do more than grow wealth. It should also provide stability, generate income, and help retirees maintain purchasing power throughout retirement.

    That is why portfolio allocation remains one of the most important topics in any Retirement Planning Guide.

    The ideal portfolio depends on age, income needs, risk tolerance, and retirement goals. However, most retirees benefit from a diversified mix of stocks, bonds, cash reserves, and income-producing investments.

    Best Retirement Portfolio Allocation by Age

    Investors often reduce portfolio risk as retirement approaches. While there is no perfect allocation for everyone, many financial planners recommend gradually increasing exposure to lower-risk assets over time.

    Readers interested in detailed age-based strategies can explore:

    Best Retirement Portfolio Allocation by Age

    Stocks vs Bonds in Retirement

    One of the most common retirement investing debates involves stocks and bonds.

    Stocks offer long-term growth potential and inflation protection. Bonds generally provide greater stability and predictable income.

    Most retirees need both.

    Too many stocks may increase portfolio volatility, while too many bonds may reduce long-term growth.

    A deeper comparison will be available in:
    Stocks vs Bonds in Retirement: What Works Best?

    How Much Cash Should Retirees Keep?

    Cash reserves play an important role during retirement.

    Many experts suggest maintaining enough cash to cover one to three years of essential expenses. This can help retirees avoid selling investments during market downturns.

    Additional guidance can be found in:
    Retirement Cash Reserve Guide

    Retirement Portfolio Comparison

    Portfolio TypeStocksBondsCashRisk Level
    Conservative40%50%10%Low
    Balanced60%35%5%Moderate
    Growth Focused75%20%5%Higher

    Why Rebalancing Matters

    Market movements can gradually change portfolio allocations.

    For example, strong stock performance may increase portfolio risk by pushing stock allocations above intended targets.

    Periodic rebalancing helps maintain the desired level of risk.

    More advanced strategies will be covered in:
    Retirement Portfolio Rebalancing Guide

    Low-Risk Investments for Conservative Retirees

    Many retirees prioritize capital preservation.

    Lower-risk investments may include high-quality bonds, Treasury securities, certificates of deposit, money market funds, and dividend-focused investments.

    Future readers can learn more through:
    Low-Risk Investments for Conservative Retirees

    A strong Retirement Planning Guide emphasizes diversification rather than prediction. The goal is not finding the perfect investment but building a portfolio capable of generating income, managing risk, and supporting long-term financial security throughout retirement.

    Protecting Retirement Wealth From Inflation and Market Uncertainty

    One of the biggest threats to retirement success is inflation. Even moderate inflation can significantly reduce purchasing power over time. A dollar today may not buy the same amount of goods and services ten or twenty years from now.

    That is why every successful Retirement Planning Guide should include strategies for protecting retirement wealth from rising costs and unexpected market events.

    Many retirees focus exclusively on preserving capital. While safety is important, maintaining some growth exposure is often necessary to help retirement assets keep pace with inflation.

    Why Inflation Matters in Retirement

    Retirement can last 20 to 30 years or longer. During that period, inflation affects nearly every expense category including housing, food, healthcare, insurance, and transportation.

    For example, a retiree spending $50,000 annually today may need significantly more income in the future simply to maintain the same lifestyle.

    Without proper planning, inflation can gradually erode retirement purchasing power.

    Dividend Investing as an Inflation Strategy

    Dividend-paying investments have historically been popular among retirees because they can provide both income and growth.

    Many established companies increase dividend payments over time, helping investors keep pace with rising living costs.

    Investors interested in building an income-focused portfolio should review our

    How to Build a Dividend Portfolio

    guide.

    You can also explore our

    Top Dividend Stocks USA 2026

    resource for additional ideas.

    Using SIP Investing for Long-Term Growth

    Even investors approaching retirement can benefit from disciplined investing habits.

    Regular investing through systematic contributions may help reduce the impact of market volatility while building long-term wealth.

    Readers can learn more in our

    SIP Investing Guide 2026
    .

    Preparing for Market Downturns

    Market corrections and recessions are inevitable.

    Retirees who rely heavily on investment portfolios should have strategies in place before market volatility occurs.

    Maintaining cash reserves, diversifying investments, and avoiding emotional decisions during downturns can help preserve retirement wealth.

    Additional strategies are covered in:


    Recession-Proof Investing 2026

    How AI Is Changing Retirement Investing

    Technology is becoming an increasingly important part of retirement planning.

    AI-powered investment tools can help investors monitor portfolios, evaluate risk levels, and identify opportunities for long-term growth.

    Readers interested in this growing trend should also explore our

    AI Investing Guide 2026
    .

    📘 Recommended Finance Book


    The Psychology of Money by Morgan Housel

    This bestselling finance book explains why behavior often matters more than investment selection. Understanding financial psychology can help retirees avoid costly mistakes during periods of market uncertainty.

    A successful Retirement Planning Guide balances income, growth, and risk management. By combining dividend investing, disciplined contributions, inflation protection, and thoughtful portfolio management, retirees can improve their chances of maintaining financial security throughout retirement.

    Real-World Retirement Case Study: How a Middle-Class Couple Prepared for Retirement

    Retirement planning concepts become easier to understand when applied to real-life situations. This case study demonstrates how a typical American couple used the principles discussed throughout this Retirement Planning Guide to build a sustainable retirement strategy.

    While every financial situation is different, the example below illustrates how disciplined saving, investing, and planning can create long-term financial security.

    Meet David and Susan

    David is 62 years old and Susan is 60.

    They live in Arizona and plan to retire within the next five years.

    Combined annual household income: $120,000

    Current retirement savings:

    • 401(k) Accounts: $750,000
    • Roth IRA Accounts: $180,000
    • Taxable Investment Account: $120,000
    • Emergency Fund: $40,000
    • Home Equity: $350,000

    Their primary goal is generating reliable retirement income while protecting their portfolio from inflation and market volatility.


    Retirement Income Strategy

    After reviewing their financial situation, David and Susan developed a diversified retirement income plan.

    • Social Security Benefits
    • 401(k) Withdrawals
    • Roth IRA Tax-Free Income
    • Dividend Income
    • Cash Reserves for Emergencies

    Instead of relying on one income source, they created multiple streams of retirement income.

    Portfolio Allocation Example

    Their retirement portfolio was structured as follows:

    • 55% Stocks
    • 30% Bonds
    • 10% Dividend Investments
    • 5% Cash Reserves

    This allocation balances growth potential with stability and income generation.

    Retirement Income Calculator Example

    David and Susan estimate they will need approximately $75,000 per year during retirement.

    Expected annual income sources:

    • Social Security: $32,000
    • Portfolio Withdrawals: $28,000
    • Dividend Income: $10,000
    • Interest Income: $5,000

    Total Estimated Retirement Income:
    $75,000 Per Year

    Because their retirement spending target aligns closely with projected income, they feel confident about maintaining their lifestyle.

    Tax Planning Approach

    The couple also implemented a tax-efficient withdrawal strategy.

    Instead of withdrawing only from traditional retirement accounts, they plan to combine taxable withdrawals, Roth IRA distributions, and Social Security benefits.Tax-Efficient Withdrawal Strategies in Retirement

    This approach may help reduce lifetime taxes and improve retirement cash flow flexibility.

    Lessons From This Case Study

    Several important retirement planning principles emerge from this example:

    • Start planning before retirement arrives.
    • Create multiple income streams.
    • Maintain diversified investments.
    • Keep emergency reserves available.
    • Consider taxes when developing withdrawal strategies.
    • Protect purchasing power from inflation.

    A successful Retirement Planning Guide is not about predicting markets perfectly. It is about creating a flexible plan capable of supporting long-term financial goals through different economic conditions.

    David and Susan’s example demonstrates that retirement success often comes from consistency, diversification, and thoughtful preparation rather than chasing high-risk investment returns.

    Common Retirement Mistakes Americans Make and How to Avoid Them

    Even investors who save consistently can make costly retirement planning mistakes. In fact, many retirement problems are not caused by poor investment performance but by avoidable financial decisions.

    That is why every effective Retirement Planning Guide should include a discussion of common mistakes and practical ways to avoid them.

    The good news is that most retirement mistakes can be corrected when identified early.

    Mistake #1: Waiting Too Long to Start Retirement Planning

    One of the most expensive mistakes Americans make is delaying retirement planning.

    Many people assume they have plenty of time and postpone saving until later in life.

    Unfortunately, delaying retirement contributions reduces the power of compound growth.

    An investor who starts saving at age 25 often needs to contribute significantly less money than someone who begins at age 45 to reach the same retirement goal.

    Mistake #2: Underestimating Healthcare Costs

    Healthcare remains one of the largest expenses during retirement.

    Many retirees focus on housing, food, and travel expenses while overlooking medical costs, insurance premiums, prescription medications, and long-term care expenses.

    Failing to plan for healthcare expenses can place significant pressure on retirement savings.

    Mistake #3: Depending Too Much on Social Security

    Social Security is an important retirement income source, but it should not be the entire retirement strategy.

    Most retirees need additional income from investments, retirement accounts, savings, and other assets.

    A diversified retirement income plan provides greater financial flexibility and security.

    Mistake #4: Poor Portfolio Diversification

    Some investors concentrate too much money in a single stock, sector, or asset class.

    While concentration can increase returns during favorable periods, it can also create significant risk.

    Diversification helps reduce portfolio volatility and improves long-term stability.

    Mistake #5: Ignoring Unexpected Retirement Expenses

    Many retirees carefully plan for regular monthly expenses but forget about irregular costs.

    Unexpected home repairs, family support, healthcare emergencies, vehicle replacements, and inflation can disrupt retirement budgets.

    Readers interested in this topic can explore our upcoming guide:

    Unexpected Retirement Expenses Most Americans Ignore

    Mistake #6: Letting Emotions Drive Investment Decisions

    Market volatility often causes investors to panic during downturns or become overly optimistic during bull markets.

    Emotional investing can lead to poor timing decisions and reduced long-term returns.

    Successful retirees typically follow disciplined investment plans rather than reacting to short-term market movements.

    📘 Recommended Finance Book


    The Simple Path to Wealth by JL Collins

    This highly respected investing book emphasizes simplicity, consistency, and long-term thinking. These principles remain valuable throughout retirement planning and wealth-building journeys.

    A successful Retirement Planning Guide is not about avoiding every mistake. It is about recognizing potential risks early and creating strategies that help protect retirement income, preserve wealth, and maintain financial confidence throughout retirement.

    The Future of Retirement Planning in America (2026–2035)

    Retirement planning continues to evolve. The strategies that worked twenty years ago may not be enough for future retirees. Rising healthcare costs, longer life expectancy, inflation concerns, and changing investment markets are reshaping retirement planning across the United States.

    The next decade will likely bring even greater changes. Investors who adapt early and remain flexible may be better positioned to build sustainable retirement income and long-term financial security.

    How Artificial Intelligence Is Changing Retirement Planning

    Artificial intelligence is becoming an increasingly important retirement planning tool.

    Modern AI platforms can analyze spending habits, monitor investment portfolios, identify risk exposures, estimate retirement income needs, and provide personalized financial recommendations.

    Investors interested in this growing trend should also review our

    AI Investing Guide 2026
    .

    As AI technology improves, retirement planning may become more personalized, efficient, and accessible for millions of Americans.

    Advanced Retirement Strategies

    Retirees and pre-retirees are increasingly exploring advanced planning techniques.

    Bond Ladder vs Dividend Income for Retirees


    Cost of Retirement by State: Complete 2026 Guide


    Best States to Retire in America

    These strategies can help retirees improve cash flow, manage taxes, reduce expenses, and strengthen long-term financial stability.

    Frequently Asked Questions

    1. How much money do I need to retire comfortably?

    The answer depends on lifestyle, location, healthcare costs, and retirement goals. Many financial planners recommend targeting 10–12 times annual salary by retirement age.

    2. Is Social Security enough for retirement?

    For most Americans, Social Security provides only part of retirement income. Additional savings and investments are usually necessary.

    3. What is the best retirement account?

    Many investors use a combination of 401(k) plans, Traditional IRAs, and Roth IRAs to maximize tax advantages and retirement flexibility.

    4. Should retirees own stocks?

    Most retirees benefit from maintaining some stock exposure to support growth and combat inflation, although allocations vary based on risk tolerance.

    5. What is the biggest retirement planning mistake?

    Waiting too long to start saving is often the most costly retirement mistake because it reduces the benefits of compound growth.

    6. Can AI help with retirement planning?

    Yes. AI tools can help monitor investments, estimate retirement needs, improve budgeting, and support financial decision-making.

    Conclusion

    A successful Retirement Planning Guide is not about predicting markets or finding perfect investments. It is about creating a reliable system that supports financial independence throughout retirement.

    By combining retirement accounts, diversified investments, Social Security planning, tax-efficient strategies, and disciplined saving habits, Americans can build stronger retirement foundations.

    The earlier retirement planning begins, the more opportunities investors typically have to grow wealth and reduce financial stress later in life.

    Whether retirement is five years away or thirty years away, taking action today can significantly improve tomorrow’s financial security.

    Trusted Retirement Resources

    📘 Recommended Finance Book


    Rich Dad Poor Dad by Robert Kiyosaki

    📩 Join Our Retirement Wealth Newsletter

    Get retirement planning tips, income strategies, Social Security updates, investing ideas, and wealth-building insights delivered directly to your inbox.

    Stay informed. Stay prepared. Build a stronger retirement future.


    👨‍💼 About the Author

    Subhash Rukade

    Subhash Rukade is the founder and author of FinanceInvestment.site. He writes about retirement planning, dividend investing, personal finance, passive income, AI investing, wealth building, and long-term financial freedom.

    His mission is simple: help everyday Americans make smarter money decisions through practical, easy-to-understand financial education. Through detailed guides, research-backed strategies, and real-world examples, he helps readers build wealth, generate retirement income, and achieve long-term financial security.

    Helping investors build a stronger financial future—one smart decision at a time.

  • AI Financial Assistants: The Next Big Money Trend in 2026

    AI Financial Assistants: The Next Big Money Trend in 2026


    AI Financial Assistants: The Next Big Money Trend in 2026

    Author: Subhash Rukade

    Published: June 18, 2026

    AI Financial Assistants

    Why AI Financial Assistants Are Becoming So Popular

    AI Financial Assistants are quickly becoming one of the biggest trends in personal finance. Across the United States, investors, savers, and families are using artificial intelligence to simplify money management and make smarter financial decisions.

    Just a few years ago, managing finances often meant tracking expenses manually, reviewing spreadsheets, and spending hours researching investment opportunities. In 2026, AI-powered financial tools can perform many of these tasks automatically.

    Modern AI Financial Assistants can analyze spending patterns, monitor savings goals, track investments, identify unusual transactions, and provide personalized recommendations. As a result, users can spend less time managing money and more time focusing on their financial goals.

    One of the biggest reasons for the rapid growth of AI Financial Assistants is accessibility. Professional financial advice is often expensive. Many Americans cannot justify paying large advisory fees, especially when starting their wealth-building journey.

    Artificial intelligence is changing that situation.

    AI-powered platforms now provide financial insights that were once available only to wealthy investors. Whether someone wants to build an emergency fund, improve budgeting habits, invest for retirement, or generate passive income, AI tools can offer guidance based on individual financial situations.

    The rise of AI Financial Assistants is closely connected to the broader transformation happening across the investing industry. Investors who want a complete understanding of this shift should explore our
    AI Investing Guide 2026.

    Another major advantage is personalization. Traditional financial advice often follows general rules. AI systems can analyze user behavior and generate recommendations based on specific goals, income levels, spending habits, and investment preferences.

    As artificial intelligence continues improving, these tools are becoming more accurate, more useful, and more capable of helping Americans make informed financial decisions.

    For many investors, AI Financial Assistants are no longer futuristic technology. They are becoming practical everyday tools that support budgeting, investing, saving, and long-term wealth building.

    How AI Financial Assistants Work

    Understanding how AI Financial Assistants work can help investors take full advantage of this growing financial technology trend.

    At their core, AI Financial Assistants use artificial intelligence, machine learning, and data analysis to review financial information and generate personalized recommendations. These systems continuously learn from user behavior, helping them deliver more accurate insights over time.

    Unlike traditional budgeting apps that simply track transactions, AI Financial Assistants actively analyze financial habits and suggest actions that may improve financial outcomes.

    AI Budgeting and Expense Tracking

    One of the most popular features is automated budgeting.

    AI Financial Assistants can connect to bank accounts, categorize transactions, and identify spending patterns automatically. Users no longer need to manually sort expenses or build complex spreadsheets.

    The system can detect areas where spending is increasing and provide recommendations to reduce unnecessary expenses.

    Investors interested in AI-powered budgeting tools can also read our
    AI Personal Finance 2026
    guide.

    Smart Savings Recommendations

    Saving money consistently is often difficult.

    AI Financial Assistants help solve this problem by analyzing cash flow and recommending realistic savings targets. Some platforms can even automate transfers into savings accounts based on spending habits and income patterns.

    This creates a more disciplined approach to wealth building.

    Credit Monitoring and Alerts

    Many AI systems also monitor credit health.

    Users receive notifications about credit score changes, unusual account activity, and opportunities to improve their financial profiles.

    Choosing the right financial products can also support long-term financial success. Readers can compare options in our
    Best Credit Cards 2026
    guide.

    Goal-Based Financial Planning

    Modern AI Financial Assistants are increasingly focused on financial goals.

    Whether someone wants to retire early, pay off debt, purchase a home, or build passive income, AI systems can track progress and suggest adjustments when needed.

    📊 Comparison Table: AI Financial Assistants vs Traditional Financial Planning

    FeatureAI Financial AssistantsTraditional Planning
    Budget TrackingAutomatedManual
    Spending AnalysisReal-TimePeriodic Reviews
    Savings RecommendationsPersonalizedGeneral Advice
    Credit MonitoringContinuous AlertsLimited Monitoring
    Financial Planning24/7 SupportScheduled Meetings

    As technology continues advancing, AI Financial Assistants are expected to become even more intelligent and personalized. For many Americans, they are quickly becoming an essential tool for managing money more effectively.

    AI Financial Assistants and Investing: A New Era of Wealth Building

    One of the most exciting benefits of AI Financial Assistants is their growing role in investing and wealth building. While many people initially use AI tools for budgeting and savings, investors are increasingly relying on artificial intelligence to help manage portfolios, monitor risk, and identify opportunities for long-term growth.

    The investing world generates enormous amounts of data every day. Market movements, earnings reports, interest rates, economic indicators, and company news can be difficult for individual investors to track consistently.

    AI Financial Assistants help solve this problem by processing large amounts of information quickly and providing insights that may help investors make better decisions.

    AI Portfolio Monitoring

    Modern AI systems can monitor investment portfolios around the clock.

    Instead of manually reviewing holdings every day, investors can receive alerts when portfolios become unbalanced, risk levels increase, or significant market changes occur.

    This helps investors stay informed without constantly watching financial markets.

    Risk Analysis and Diversification

    Managing risk is one of the most important parts of successful investing.

    AI Financial Assistants can evaluate portfolio diversification, identify concentration risks, and recommend adjustments that align with an investor’s goals and risk tolerance.

    By helping investors avoid emotional decisions, AI can support a more disciplined investment strategy.

    AI and Dividend Investing

    Dividend investing remains one of the most popular wealth-building strategies in America.

    AI-powered tools can help investors identify quality dividend stocks, monitor payout growth, and track income performance over time.

    Readers interested in creating long-term passive income can explore our
    How to Build a Dividend Portfolio
    guide.

    Investors looking for potential opportunities can also review our
    Top Dividend Stocks USA 2026
    resource.

    Building Wealth Through Automation

    One of the biggest advantages of AI Financial Assistants is consistency.

    Many investors struggle because they invest emotionally or abandon long-term plans during market volatility. AI systems can automate investing decisions, portfolio reviews, and contribution schedules based on predefined goals.

    This helps investors remain focused on long-term wealth building rather than short-term market noise.

    📘 Recommended Finance Book


    The Psychology of Money by Morgan Housel

    This bestselling finance book explains how behavior and decision-making influence investment success. Even with advanced AI tools, understanding human psychology remains one of the most important parts of building wealth.

    As AI technology continues evolving, AI Financial Assistants may become powerful partners for investors seeking smarter portfolio management, stronger risk control, and more efficient wealth-building strategies.

    Real-World Example: How AI Financial Assistants Help Americans Build Wealth

    The growing popularity of AI Financial Assistants is not just about technology. It is about helping real people make better financial decisions every day.

    Many Americans struggle to balance budgeting, saving, investing, debt repayment, and retirement planning. Managing all these responsibilities simultaneously can feel overwhelming.

    This is where AI-powered financial tools can provide meaningful support.

    📊 Real-World Case Study

    Consider Sarah, a 35-year-old marketing professional living in Texas.

    Sarah earns $75,000 annually and wants to achieve three goals:

    • Build a larger emergency fund
    • Increase retirement savings
    • Create passive income through investing

    Before using AI Financial Assistants, Sarah managed her finances manually. She often missed savings targets and struggled to track spending patterns.

    After connecting her accounts to an AI-powered financial platform, the system began analyzing her spending habits.

    Within a few weeks, the AI identified recurring expenses, unnecessary subscriptions, and spending categories where savings opportunities existed.

    The assistant recommended automatic transfers to savings accounts and increased retirement contributions without significantly impacting monthly cash flow.

    Over time, Sarah became more consistent with her financial plan.

    AI Financial Assistants Example

    💰 Investment Growth Calculator Example

    Suppose Sarah invests $300 per month into a diversified portfolio earning an average annual return of 8%.

    Years InvestedEstimated Portfolio Value
    10 Years~$55,000
    20 Years~$177,000
    30 Years~$447,000

    This example demonstrates how consistent investing combined with smart financial management can create meaningful wealth over time.

    AI Financial Assistants and Retirement Planning

    Many modern AI Financial Assistants can also help users prepare for retirement.

    These systems can estimate future savings needs, monitor retirement accounts, and recommend adjustments based on changing financial goals.

    Rather than replacing financial advisors, AI tools often act as intelligent assistants that help users stay organized and focused.

    For investors, the greatest value may come from improved consistency. Small improvements in budgeting, saving, and investing can compound into significant financial results over decades.

    Common Mistakes and Risks of Using AI Financial Assistants

    While AI Financial Assistants offer many benefits, investors should also understand their limitations. Like any financial tool, artificial intelligence works best when used responsibly.

    Many people assume AI can solve every financial problem automatically. In reality, successful money management still requires human judgment, financial education, and long-term planning.

    Understanding the risks can help investors use AI Financial Assistants more effectively.

    Mistake #1: Blindly Trusting AI Recommendations

    One of the biggest mistakes users make is assuming every AI recommendation is correct.

    Artificial intelligence analyzes available data and generates suggestions based on patterns. However, it cannot predict the future with complete accuracy.

    Investors should always review recommendations carefully and ensure they align with personal financial goals.

    Mistake #2: Ignoring Data Privacy

    Most AI Financial Assistants require access to financial information such as bank accounts, spending data, investment portfolios, and credit reports.

    Users should carefully review privacy policies and security measures before connecting sensitive financial accounts.

    Choosing reputable platforms with strong security practices is essential.

    Mistake #3: Depending Entirely on Automation

    Automation can improve consistency, but relying completely on AI can create problems.

    Financial goals, family situations, and market conditions change over time. Investors should regularly review their financial plans rather than assuming automation will handle every situation perfectly.

    Market Risks Still Exist

    Even the best AI Financial Assistants cannot eliminate investment risk.

    Markets remain unpredictable. Economic recessions, geopolitical events, and unexpected market downturns can impact investment performance.

    Investors who want to strengthen their portfolios during uncertain times should also read our
    Recession-Proof Investing 2026
    guide.

    Trusted Financial Resources

    📘 Recommended Finance Book


    The Simple Path to Wealth by JL Collins

    This popular investing book emphasizes diversification, long-term investing, and financial discipline. These principles remain important regardless of how advanced AI Financial Assistants become.

    The smartest investors view AI as a powerful tool rather than a replacement for financial knowledge. Combining technology with sound decision-making often produces the best long-term results.

    Practical Strategies for Using AI Financial Assistants Successfully

    The most successful users of AI Financial Assistants understand an important principle: artificial intelligence works best when combined with human judgment.

    AI can analyze data, identify patterns, and automate financial tasks. However, investors still need to define goals, manage risk, and make final decisions.

    Instead of replacing financial planning, AI Financial Assistants should be viewed as powerful tools that support smarter money management.

    Use the AI + Human Strategy

    One of the best approaches is combining AI recommendations with personal financial knowledge.

    For example, an AI assistant may recommend increasing investment contributions or adjusting spending habits. Investors should review these recommendations and ensure they align with personal goals before taking action.

    This balanced approach helps maximize the benefits of AI while maintaining control over financial decisions.

    Build a Strong Emergency Fund

    Many AI Financial Assistants can help users identify opportunities to save more money.

    Building an emergency fund should remain a priority before taking significant investment risks.

    A strong emergency fund provides financial stability during unexpected situations such as job loss, medical expenses, or economic downturns.

    Stay Consistent With Long-Term Investing

    Consistency is often more important than trying to predict short-term market movements.

    AI Financial Assistants can automate recurring investments and help investors stay committed to long-term wealth-building plans.

    Readers interested in disciplined investing strategies should also explore our
    SIP Investing Guide 2026.

    📊 Comparison Table: Smart AI User vs Poor AI User

    Smart AI UserPoor AI User
    Uses AI as a guideFollows AI blindly
    Reviews recommendationsNever verifies suggestions
    Diversifies investmentsConcentrates risk
    Focuses on long-term goalsChases short-term trends
    Maintains emergency savingsIgnores financial safety nets

    📘 Recommended Finance Book


    Rich Dad Poor Dad by Robert Kiyosaki

    This classic personal finance book teaches important lessons about assets, cash flow, investing, and wealth creation. These concepts remain valuable even in an AI-driven financial world.

    The future belongs to investors who combine technology, discipline, diversification, and long-term thinking. AI Financial Assistants can make financial management easier, but consistent action remains the foundation of lasting wealth.

    The Future of AI Financial Assistants: What Investors Can Expect by 2030

    The future of AI Financial Assistants looks incredibly promising. As artificial intelligence continues evolving, these tools are expected to become more intelligent, more personalized, and more integrated into everyday financial life.

    Today, AI Financial Assistants help users budget, save, and monitor investments. By 2030, many experts believe these systems could function as complete financial management platforms capable of supporting nearly every aspect of personal finance.

    AI Wealth Management Will Become More Personalized

    Future AI Financial Assistants may analyze income, spending habits, investment performance, retirement goals, and risk tolerance simultaneously.

    Instead of providing generic recommendations, they may create highly customized financial plans tailored to each individual’s unique circumstances.

    AI Retirement Planning Will Improve

    Retirement planning remains one of the biggest financial challenges facing Americans.

    Future AI systems may automatically adjust retirement contributions, estimate future healthcare costs, optimize withdrawal strategies, and monitor retirement readiness in real time.

    This could make retirement planning more accessible and effective for millions of households.

    Smarter Banking and Money Management

    Banks are investing heavily in artificial intelligence.

    Future AI Financial Assistants may provide predictive cash-flow management, advanced fraud protection, automated bill optimization, and personalized savings strategies directly within banking platforms.

    As a result, managing money could become significantly easier and more efficient.

    Frequently Asked Questions

    1. What are AI Financial Assistants?

    AI Financial Assistants are software tools that use artificial intelligence to help users manage budgeting, saving, investing, debt repayment, and financial planning.

    2. Are AI Financial Assistants safe?

    Most reputable platforms use strong security measures. However, users should always review privacy policies and security practices before connecting financial accounts.

    3. Can AI Financial Assistants help with investing?

    Yes. Many platforms offer portfolio monitoring, investment analysis, diversification recommendations, and risk management insights.

    4. Can AI replace financial advisors?

    AI can automate many financial tasks, but human advisors still provide emotional support, complex planning, and personalized guidance for unique situations.

    5. Do AI Financial Assistants help with retirement planning?

    Yes. Many tools already support retirement savings tracking, goal monitoring, and investment planning.

    6. Are AI Financial Assistants worth using in 2026?

    For many investors, they provide valuable insights, automation, and convenience that can improve financial decision-making.

    Conclusion

    AI Financial Assistants are becoming one of the most important trends in modern personal finance. They help users automate budgeting, improve saving habits, monitor investments, and make smarter financial decisions.

    As artificial intelligence becomes more advanced, these tools are expected to play an even larger role in wealth building, retirement planning, and everyday money management.

    Investors who want to stay ahead of these trends should also read our
    AI Investing Guide 2026.

    Additional trusted resources:

    📩 Join Our Free Financial Newsletter

    Get AI investing insights, personal finance tips, retirement strategies, passive income ideas, and wealth-building guides delivered directly to your inbox.


    Subscribe today and stay ahead of the future of money management.


    👨‍💼 About the Author

    Subhash Rukade writes about AI investing, personal finance, retirement planning, passive income, and wealth-building strategies. His mission is to help readers make smarter financial decisions through practical and easy-to-understand financial education.