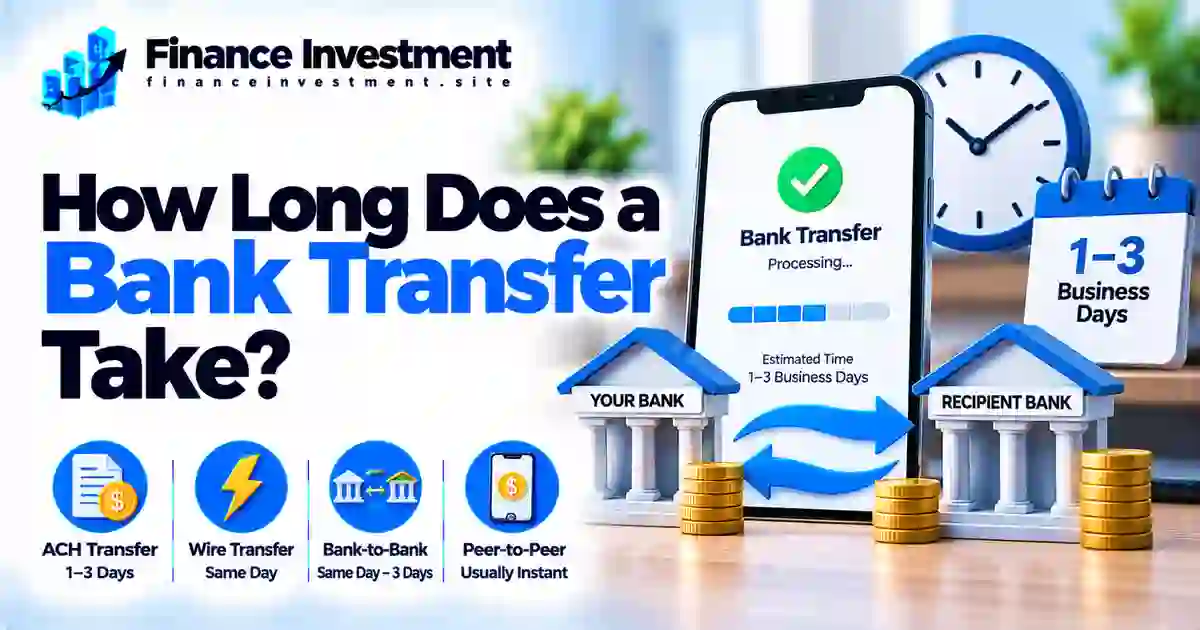
How Long Does a Bank Transfer Take?
Updated: October 28, 2026
Reading time: 8 minutes
How Long Does a Bank Transfer Take? What to Expect
If you’re wondering how long does a bank transfer take, the answer depends on the payment method, the banks involved, and when you send the money. Some eligible instant payments arrive within seconds, while standard ACH transfers commonly take one to three business days. Domestic wire transfers may arrive the same business day when sent before the bank’s cutoff time, but timing and availability vary by institution.
The transfer type makes a real difference. ACH is commonly used for direct deposits, recurring bills, and transfers between accounts. Wire transfers are often used when speed matters, while instant-payment services can move eligible payments much faster. Weekends, federal holidays, bank processing schedules, security reviews, and incorrect account details can all affect when money arrives or becomes available.
Knowing the typical timelines can help you plan a bill payment, move savings, or send money without unnecessary stress. For a broader look at available methods, read our complete guide to bank transfers and payments.
What You’ll Learn
- How long ACH, wire, internal bank, and instant transfers typically take.
- How bank cutoff times, weekends, and holidays affect processing.
- Why a transfer may be pending, delayed, or unavailable to the recipient.
- How to choose a transfer method based on urgency, fees, and availability.
Quick Answer: How Long Does a Bank Transfer Take?
A US bank transfer can take seconds, one or more business days, or longer, depending on the payment method. Eligible instant payments may arrive within seconds. Standard ACH transfers commonly take one to three business days, while domestic wire transfers may arrive the same business day if sent before the applicable cutoff. International transfers can take several business days or longer, depending on the countries, banks, and intermediary institutions involved.
Key Takeaways
- ACH transfers commonly take one to three business days, although some payments may arrive sooner.
- Domestic wire transfers may arrive the same business day, depending on bank cutoffs and processing.
- Weekends, federal holidays, security reviews, and incorrect recipient details can cause delays.
- A transfer marked as sent or completed does not necessarily mean the recipient’s funds are immediately available to spend.
The Bottom Line
Before sending money, check your bank’s estimated delivery time, cutoff rules, and any applicable fees. If the payment is urgent, confirm that the chosen method supports the required timing and that the recipient can receive it. Do not assume every transfer is instant, even when both accounts are held at the same bank.
Bank Transfer Times at a Glance
How long a bank transfer takes depends on the payment network, the banks involved, submission time, and when the recipient’s funds become available. These are general estimates for common US payment methods, not guaranteed delivery times.
| Transfer method | Typical timing |
|---|---|
| Transfer between accounts at the same bank | Often immediate or same day; some transfers take longer |
| ACH transfer between banks | Commonly 1–3 business days; some eligible payments are faster |
| Domestic wire transfer | Often the same business day if accepted and processed before the applicable cutoff |
| Eligible instant payment | Usually seconds, if the sending and receiving institutions support the same service |
| International bank transfer | Often several business days; the route, currency, and intermediary banks affect timing |
QUICK TAKE: Business days generally exclude weekends and bank holidays. A payment marked as sent or completed may not mean the recipient can spend the money immediately. Check your bank’s estimated delivery date and the receiving bank’s funds-availability rules.
Timing varies by institution, payment service, cutoff time, and any security or compliance review.
A Beginner’s Guide to Bank Transfers
A bank transfer moves money electronically from one account to another. You might use one to move savings between your own accounts, pay a bill, send money to another person, or pay a business. The transfer method affects processing time, fees, limits, and when the recipient can access the funds.
Common Types of Bank Transfers
- Internal bank transfers: Move money between accounts at the same bank. They often post quickly, although timing depends on the bank, account type, and transaction.
- ACH transfers: Use the Automated Clearing House network for direct deposits, bill payments, and transfers between banks. Standard ACH transfers commonly take one to three business days, although some payments may arrive sooner.
- Wire transfers: Send money through wire networks. Domestic wires may arrive the same business day if accepted before the bank’s cutoff, while international wires can take several business days or longer.
- Instant payments and person-to-person services: Eligible payments through supported instant-payment networks may arrive within seconds. Services such as Zelle have their own eligibility, enrollment, and processing rules, so delivery times can vary.
Before sending money, confirm the recipient’s details, estimated delivery time, transfer limits, and applicable fees. Learn more in our guides to how wire transfers work and bank transfers and payment methods.
Beginner tip: A payment being sent or processed does not necessarily mean the recipient can spend the money immediately. Check the expected arrival time and funds-availability rules before relying on a transfer for an urgent bill.
How Bank Transfer Processing Works
When you send money, your bank must process the payment through the relevant system before the recipient can use the funds. The exact steps and timing depend on whether you use an internal transfer, ACH, a wire, or an instant-payment service.
1. You Initiate the Payment
You provide the amount and recipient details through your bank or payment service. The provider may check your identity, available balance, transfer limits, and payment instructions.
2. The Payment Enters the Relevant System
Your bank processes the instruction using the applicable system. ACH payments follow ACH processing schedules, wires use wire networks, and eligible instant payments use supported real-time payment services.
3. The Payment Is Routed to the Recipient
The receiving bank or payment provider handles the incoming payment according to the relevant network rules and its own procedures. Incorrect details, compliance checks, or other exceptions may delay or prevent delivery.
4. The Recipient Gets Access to the Funds
The money may be available immediately or later, depending on the payment method and the receiving institution’s rules. A displayed transaction status does not always confirm that the recipient can spend the funds.
Why this matters: “Pending,” “processing,” and “completed” can mean different things across banks and payment services. Check the transaction details and estimated arrival date in your bank’s app. If the expected date passes, contact your bank using its official contact information.
Benefits and Drawbacks of Different Transfer Methods
The right transfer method depends on how quickly the money must arrive, what it costs, and whether the recipient can receive it. A faster payment is not automatically the most economical or appropriate option.
Benefits
- ACH: Useful for payroll, recurring bills, and routine account-to-account payments; fees may be low or nonexistent, depending on the provider.
- Wire transfers: Can be suitable for time-sensitive or high-value payments when the recipient’s details are verified.
- Instant payments: Eligible transactions can reach recipients within seconds when the required service is supported.
Drawbacks
- ACH: Standard transfers may take multiple business days, and processing schedules can affect arrival.
- Wire transfers: Fees may apply, and completed wires can be difficult to recover if sent to the wrong recipient.
- Instant payments: Availability and limits vary; authorized payments may be difficult to recover if sent to a scammer.
Before sending money, verify the recipient’s information and check your bank’s fees, limits, and delivery estimate. Compare the options in our guide to ACH transfers vs. wire transfers.
Bank Transfer Processing Time: Compare Your Options
In the US, transfer timing depends on the payment network, the banks involved, and when the transaction is submitted. The estimates below are general guidelines, not guaranteed arrival times.
| Transfer method | Typical timing | Common use |
|---|---|---|
| Transfer between accounts at the same bank | Often immediate or same day; some transactions take longer | Moving money between eligible accounts at one institution |
| ACH transfer between banks | Commonly 1–3 business days; eligible payments may be faster | Direct deposits, bills, and routine bank transfers |
| Domestic wire transfer | Often the same business day when accepted before the applicable cutoff | Time-sensitive or high-value payments |
| Eligible instant payment | Usually seconds when the service is supported and available | Payments between participating institutions |
| International bank transfer | Often several business days; some transfers take longer | Sending money across countries or currencies |
Expert note: Cutoff times, weekends, bank holidays, currency conversion, intermediary institutions, and additional reviews can affect delivery. Also distinguish the time a payment reaches the recipient’s bank from the time the funds become available to spend.
Choosing between common bank payment methods? Read our guide to ACH transfers vs. wire transfers before sending money.
How Cutoff Times, Weekends, and Holidays Affect Bank Transfers
Submitting a transfer online does not always mean processing begins immediately. Banks set cutoff times for certain payment methods. If you miss the applicable deadline, your payment may be processed on the next business day, depending on the bank and transfer type.
What Can Change Your Transfer Timeline?
- Weekends: Standard ACH transfers generally follow business-day processing schedules. A transfer submitted late on Friday may not begin processing until the next business day.
- Bank holidays: Federal holidays can affect ACH and wire processing. A holiday may push the expected delivery date back, depending on the payment method.
- Cutoff times: Deadlines vary by bank, account, and payment type. Online banking may be available around the clock even when a particular transfer is not processed immediately.
- Instant-payment services: Eligible payments through supported real-time networks may operate outside traditional banking hours, but availability and service rules still apply.
Expert Tips to Avoid Delays
- Submit time-sensitive transfers early on a business day when possible.
- Confirm the cutoff time and estimated arrival date with your bank.
- Double-check the recipient’s routing number, account number, and other required details.
- Allow extra time for international payments, which may involve currency conversion and intermediary banks.
If a payment must arrive by a deadline, ask your bank which available method is suitable, what it costs, and when the recipient should receive the funds. Do not assume that every transfer submitted after hours will arrive the same day.
Why Do Bank Transfers Get Delayed?
If a transfer takes longer than expected, one or more of these factors may be responsible:
- Missed cutoff time: The bank may process the payment on the next eligible business day.
- Weekends or bank holidays: Standard ACH and wire processing schedules can extend the wait.
- Incorrect recipient details: An incorrect account or routing number may lead to rejection, a delay, or a payment being sent to an unintended account.
- Security or compliance review: A bank may need additional information or verification before processing a transaction.
- International processing: Currency conversion, intermediary institutions, and checks by participating banks can add time.
Real-Life Example: An ACH Transfer Sent on Friday
Imagine Alex schedules an ACH transfer between two US banks late Friday afternoon, after the sending bank’s cutoff. The bank may treat it as received for processing on the next business day. The money could arrive later, depending on the ACH schedule, the banks’ processing times, and any applicable holiday. The exact arrival date should be confirmed with the bank.
If your transfer is late, check its status and estimated arrival date. If that date has passed, contact your bank using the official app or phone number and keep the transaction confirmation handy. If you suspect incorrect recipient details or fraud, notify the bank promptly. Avoid sending a duplicate payment until you confirm what happened to the original transaction.
Which Bank Transfer Method Should You Choose?
Choose a transfer method based on your deadline, total cost, payment limits, and the recipient’s ability to receive the funds.
- For routine payments: ACH may suit payroll, bills, and eligible transfers between different banks.
- For urgent domestic payments: Check whether both institutions support an eligible instant-payment service. A domestic wire may also work if it can be processed before the applicable cutoff.
- For your own accounts at the same bank: An internal transfer may be convenient, subject to the bank’s account rules and processing schedule.
- For international payments: Compare estimated delivery times, exchange rates, transfer fees, and any intermediary or receiving-bank charges.
Before you send: Verify the recipient’s details, confirm the estimated arrival time, and review applicable fees and cancellation or recall options. Once a payment has been processed, recovering it may be difficult, especially if the recipient is incorrect or fraudulent.
Frequently Asked Questions About Bank Transfer Times
1. How long does a bank transfer usually take?
It can take seconds to several business days. Eligible instant payments may arrive within seconds, standard ACH transfers commonly take one to three business days, and international transfers may take longer.
2. Can a bank transfer take 24 hours?
Yes. Some transfers arrive within 24 hours, but this is not guaranteed. Standard ACH transfers may take multiple business days, especially when weekends, holidays, or cutoff times affect processing.
3. Do bank transfers go through on weekends?
Some eligible instant-payment services operate on weekends. Standard ACH and many wire transfers follow business-day schedules, so a weekend submission may be processed later.
4. Why is my bank transfer still pending?
A transfer may be pending because of processing schedules, a missed cutoff, verification checks, or incomplete payment details. Check the transaction status and estimated arrival date with your bank.
5. Are wire transfers faster than ACH transfers?
Often, yes. Domestic wires may arrive the same business day when processed before the applicable cutoff, while standard ACH transfers commonly take one to three business days.
6. How long does an international bank transfer take?
Many international bank transfers take several business days, but some take longer. The destination, currency conversion, intermediary banks, and required checks can affect delivery.
7. Can a bank transfer arrive on the same day?
Yes. Eligible internal transfers, instant payments, and some domestic wires may arrive the same day. The actual timing depends on the payment method, bank processing, and recipient eligibility.
8. What should I do if my bank transfer has not arrived?
Check the estimated arrival date and transaction status. If the expected date has passed, contact your bank through its official app or phone number and provide the transaction reference. If you suspect fraud or incorrect recipient details, notify the bank promptly.
Final Verdict: How Long Does a Bank Transfer Take?
A bank transfer can arrive within seconds or take several business days. The timeline depends on the payment method, bank processing schedules, and the recipient’s ability to receive the payment. Standard ACH transfers commonly take one to three business days, eligible instant payments may arrive within seconds, and domestic wires may arrive the same business day when processed before the applicable cutoff.
Before sending money, verify the recipient’s details and compare the estimated arrival time, fees, transfer limits, and funds-availability rules. If the payment is urgent, confirm directly with your bank that the chosen method can meet your deadline.
Your next step: Explore our complete guide to bank transfers and payments to compare common payment methods and choose one that fits your timing and budget.
Make Your Next Money Move with Confidence
Choosing the right transfer method can help you manage timing, fees, and payment risks. Explore our banking guides for more practical tips on handling your money safely.
Have feedback or a question about this guide? Email FinanceInvestment.
Leave a Reply