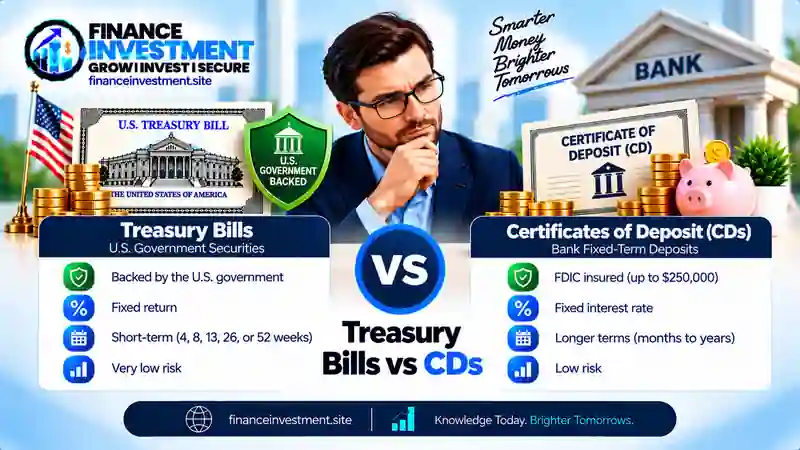
Tag: Treasury Bills vs CDs

  • Who Should Not Buy Treasury Bills? A 2026 Guide

    Who Should Not Buy Treasury Bills? A 2026 Guide

    Who Should Not Buy Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 28, 2026


    Updated: Sep 28, 2026


    Reading Time: 10–12 min


    Who Should Not Buy Treasury Bills?

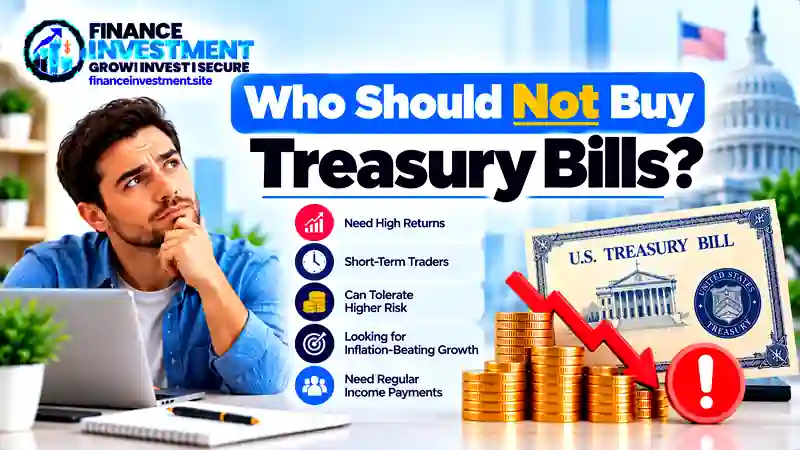
    Who Should Not Buy Treasury Bills?Who should not buy Treasury bills? In many cases, it is the person who needs immediate access to cash, cannot match the investment to a fixed timeline, or is using short-term money for a long-term goal. T-bills can be useful, but the maturity date matters.

    A family building an emergency fund may need more flexibility. A retiree may need cash available for an unexpected bill. A long-term investor may also have little reason to put growth-focused money into a short-term Treasury security. The issue is not simply whether T-bills are safe. It is whether they fit the job your money needs to perform.

    If you are new to Treasury securities, our Treasury Bills Explained guide covers the basics. This article takes the next step by showing when buying T-bills may create an unnecessary limitation or mismatch.

    What You’ll Learn

    • When a Treasury bill maturity may not match your cash needs.
    • Why emergency savings and everyday spending money need flexibility.
    • How early selling, reinvestment, inflation, and tax considerations can affect T-bill decisions.
    • When savings accounts, money market accounts, or CDs may be worth comparing.
    • Common mistakes people make when choosing short-term Treasury investments.

    Quick Answer: When Should You Avoid Treasury Bills?

    Treasury bills may not fit investors who need their money on demand, cannot comfortably wait until a chosen maturity date, or are using the funds for a long-term objective. They can also be a poor match when an upcoming expense has an uncertain date.

    KEY TAKEAWAYS

    • Money needed for emergencies may require easier access than a T-bill provides.
    • A maturity date can become inconvenient when your spending timeline changes.
    • Selling before maturity can result in a market price different from your purchase price.
    • Short-term Treasury securities are not a substitute for a diversified long-term portfolio.
    • After maturity, reinvestment may involve different rates and terms.
    • Taxes, liquidity, and opportunity cost should be considered before buying.

    Bottom line: A T-bill can be useful for the right purpose, but the wrong maturity can make even a conservative investment inconvenient. Start with the job of the money, then decide whether a Treasury bill fits.

    Who Should Not Buy Treasury Bills? at a Glance

    Treasury bills can be useful for certain short-term goals, but they may not suit every cash need. The clearest warning sign is a mismatch between your financial timeline and the fixed maturity of the bill.

    Investor SituationWhy a T-Bill May Not FitWhat to Check
    Needs immediate accessThe money may be needed before the bill reaches maturity.Keep emergency and everyday cash readily accessible.
    Has an uncertain expense dateA fixed maturity may not line up with when the expense actually occurs.Consider whether a flexible account would work better.
    Needs long-term growthA short-term Treasury security may not serve a long investment horizon.Review whether the portfolio needs growth-oriented assets.
    May need to sell earlyThe market price before maturity can differ from the original purchase price.Consider whether you can reasonably hold until maturity.
    QUICK TAKE

    A Treasury bill may be the wrong tool when flexibility matters more than a defined maturity. Start with the purpose of the money, then decide whether a T-bill fits that timeline.

    Complete Beginner Guide: When Treasury Bills May Not Fit
    Who Should Not Buy Treasury Bills?For a beginner, the first step is not choosing a Treasury bill. It is deciding whether the money can reasonably stay invested for a set period. Start with the purpose of the cash, the date you may need it, and how much flexibility you want.

    Treasury bills have specific maturity dates. That can be helpful for planned expenses, but it can also become inconvenient if your plans change. If you need the money earlier, selling before maturity may involve a different market price than the amount you originally paid.

    Three Questions to Ask Before Buying

    1. When might I need the money? Choose a maturity only after considering the likely spending date.
    2. Can I leave the money invested? Cash that may be needed unexpectedly may require a more accessible option.
    3. What will I do at maturity? Decide whether you will spend the proceeds, keep them available, or evaluate another investment.
    BEGINNER CHECK

    Do not select a T-bill based only on its quoted return. Make sure the maturity, access to the money, and purpose of the investment fit your situation first.

    How Treasury Bills Work — And Where the Mismatch Happens

    Treasury bills are short-term U.S. Treasury securities. They are generally sold at a discount, so the purchase price is below the bill’s face value. At maturity, the investor receives the face value. The difference between the purchase price and face value generally represents the investment’s interest.

    The potential problem appears when your plans change. If you need the money before maturity, you may choose to sell the bill in the secondary market. The price at that time can be above or below what you paid, depending on market conditions. That makes an early sale different from simply holding the bill until maturity.

    Where the Fit Can Break Down

    • Cash-flow mismatch: You need the proceeds before the scheduled maturity date.
    • Access mismatch: Your money needs to remain available for unpredictable expenses.
    • Goal mismatch: The funds are intended for a much longer investment objective.
    • Reinvestment mismatch: You plan to reinvest after maturity, but future rates may be different.
    KEY IDEA

    The mechanics of a T-bill are simple. The real question is whether the investment timeline still works if your financial plans change.

    Benefits & Drawbacks of Treasury Bills

    Treasury bills can have useful features, but those features do not make them suitable for every investor. The same fixed maturity that helps with planning can become inconvenient when the timing or purpose of your money changes.

    ✓ Potential Benefits

    • Short maturities can work for certain defined cash goals.
    • T-bills are direct obligations of the U.S. Treasury.
    • Interest is generally exempt from state and local income taxes.
    • Different maturities can help investors organize future cash needs.
    ✕ Potential Drawbacks

    • The money is linked to a defined maturity date.
    • An early sale can expose you to changes in market price.
    • Future reinvestment rates can be different from today’s rates.
    • T-bills may not match a portfolio’s long-term growth objectives.
    EXPERT TIP

    Look beyond the purchase yield. Before choosing a T-bill, consider when the money is needed, how much access you require, the tax treatment, and whether the investment matches the purpose of the cash.

    T-Bills vs. Other Cash Options

    If Treasury bills do not match your cash needs, compare them with options built for different purposes. A high-yield savings account, money market account, or CD may offer a different balance of access, timing, and account features.

    OptionMay Fit WhenMain Point to Check
    Treasury BillsYou have a defined short-term timeline and can plan around maturity.Maturity date, early-sale price, taxes, and reinvestment.
    High-Yield Savings AccountYou want savings with relatively easy access to your money.Rate changes, fees, withdrawal terms, and FDIC coverage.
    Money Market AccountYou want a bank deposit account with savings features and potential transaction access.Rate, fees, transaction rules, minimum balance, and FDIC coverage.
    CDYou can leave the money deposited for a stated term.Early-withdrawal penalty, maturity date, rate, and FDIC coverage.

    For a closer look at the differences, see our guides on Treasury bills vs. CDs and Treasury bills vs. money market accounts.

    QUICK COMPARISON

    Treasury bills are U.S. government securities, while savings accounts, money market accounts, and CDs are bank deposits. Compare access, maturity, taxes, fees, and applicable FDIC coverage before choosing where to keep the money.

    Costs, Risks & Expert Tips

    Buying a Treasury bill does not automatically mean paying a traditional account fee. However, your overall result can still be affected by the purchase method, an early sale, taxes, inflation, and what happens when the bill matures.

    Costs and Risks to Watch

    • Transaction costs: Check whether your brokerage charges any applicable fee or markup for buying or selling Treasury securities.
    • Early-sale risk: A T-bill sold before maturity can have a market price above or below your original purchase price.
    • Reinvestment risk: When the bill matures, a new T-bill may carry a different rate.
    • Inflation risk: Inflation can reduce the purchasing power of the money you receive at maturity.
    • Tax consideration: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    EXPERT TIP

    Before buying, write down the amount you can invest, the earliest date you may need the money, and your plan if that date changes. If the timeline is uncertain, compare a more flexible cash option first.

    Common Mistakes + Real-Life Example

    The biggest T-bill mistakes often happen before the order is placed. Investors may focus on the advertised return while overlooking how soon the money could be needed or what happens if their plans change.

    Common Mistakes to Avoid

    • Putting emergency cash into a T-bill: Emergency money may need to remain readily accessible.
    • Choosing a maturity without a purpose: The term should connect to an actual financial timeline.
    • Looking only at the yield: A competitive return does not solve a liquidity or timing problem.
    • Ignoring the maturity plan: Decide in advance whether the proceeds will be spent, held, or considered for reinvestment.

    A Simple Family Example

    Suppose a family has $12,000 reserved for a home repair, but the contractor has not confirmed the project date. They choose a T-bill without leaving enough flexible cash. Two months later, the repair needs to start sooner than expected. The family now has to consider selling the T-bill instead of simply using available savings.

    LESSON

    When the spending date is uncertain, flexibility can matter more than locking money into a defined maturity. Match the investment to the certainty of the goal.

    Who Should Choose Something Else?

    Treasury bills are only one way to handle short-term money. If your priority is immediate access, a bank deposit with specific account features, or a much longer investment horizon, it may make sense to compare other choices before committing the cash.

    Situations Worth Comparing

    • Emergency savings: Money that may be needed without warning generally calls for easy access. Compare the differences in our Treasury bills vs. savings accounts guide.
    • Flexible cash needs: A money market account may be worth reviewing when deposit-account access and transaction features are important.
    • Fixed bank deposit: A CD uses a stated deposit term and may be considered when you can leave the money deposited for that period. See our Treasury bills vs. CDs guide.
    • Long-term goals: Money intended for a longer horizon may need to be evaluated within a broader investment strategy rather than treated as short-term cash.
    CHOICE CHECK

    Before choosing an alternative, identify how quickly you may need the money, how long you can leave it untouched, and what account or investment features matter to you.

    Frequently Asked Questions About Who Should Not Buy Treasury Bills

    Who should not buy Treasury bills?

    Treasury bills may not fit people who need immediate access to their money, cannot comfortably wait until maturity, or are using the funds for a long-term investment objective.

    Should beginners avoid Treasury bills?

    Beginners do not automatically need to avoid them. They should first understand the maturity date, purchase price, early-sale considerations, tax treatment, and reinvestment before investing.

    Should I use Treasury bills for my emergency fund?

    Emergency savings may need quick access. Consider whether a T-bill’s maturity structure fits that need or whether a more accessible savings option is appropriate for your emergency cash.

    Can you lose money by selling a Treasury bill early?

    Yes. If you sell before maturity, the market price may be above or below your original purchase price. The result depends on market conditions when you sell.

    Are Treasury bills bad for long-term investors?

    Not necessarily. T-bills can have a role in short-term cash management, but money intended primarily for long-term growth may need to be evaluated within a broader investment strategy.

    Are Treasury bills less flexible than savings accounts?

    They work differently. A T-bill has a maturity date, while a savings account is a bank deposit account designed to provide access to deposited funds according to its account terms.

    Do Treasury bills have tax advantages?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Individual tax circumstances can vary.

    What should I consider before buying a Treasury bill?

    Consider when you need the money, whether you can hold until maturity, the possibility of an early-sale price change, applicable taxes, your reinvestment plan, and whether another cash option fits your needs.

    Final Verdict: When Treasury Bills May Not Fit

    Treasury bills can serve a useful role in short-term financial planning, but the same maturity structure that works for one goal may be inconvenient for another. The key question is whether you can leave the money invested for the period you selected.

    If your cash is needed for emergencies, an expense date may change, or the money is intended primarily for long-term growth, compare other options before buying. Savings accounts, money market accounts, CDs, and other investments each have different features to evaluate.

    If you want to understand the broader role and mechanics of T-bills, continue with our Treasury Bills Explained guide before making a decision.

    THE BOTTOM LINE

    Start with the purpose of the money, then consider the timeline and access you need. A Treasury bill should fit those conditions rather than forcing your financial plan to fit the investment.

    Related Resources

    If you want to explore the topic further, these resources cover emergency savings, T-bill comparisons, buying, maturity planning, pricing, and official tax information.

    FinanceInvestment Guides

    Official & Educational Sources

    • TreasuryDirect — Official U.S. Treasury information about Treasury securities, auctions, purchases, and account management.
    • IRS Publication 550 — Federal tax information covering Treasury securities and investment income.
    • NerdWallet Treasury Bills Guide — Additional educational information about T-bills, purchasing, and common considerations.

    Have a Money Question? Keep Exploring.

    Money decisions become easier when you understand how each option fits your timeline and goals. Keep exploring FinanceInvestment for practical guides on saving, investing, Treasury bills, CDs, and other personal finance topics.

    📬 Stay Connected With FinanceInvestment
    Follow new money guides and practical investing topics as they are published.
    📧 Email FinanceInvestment
  • Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 25, 2026
    Updated: Sep 25, 2026
    Reading Time: 10–12 min


    Treasury Bills vs CDs: What Should You Know?

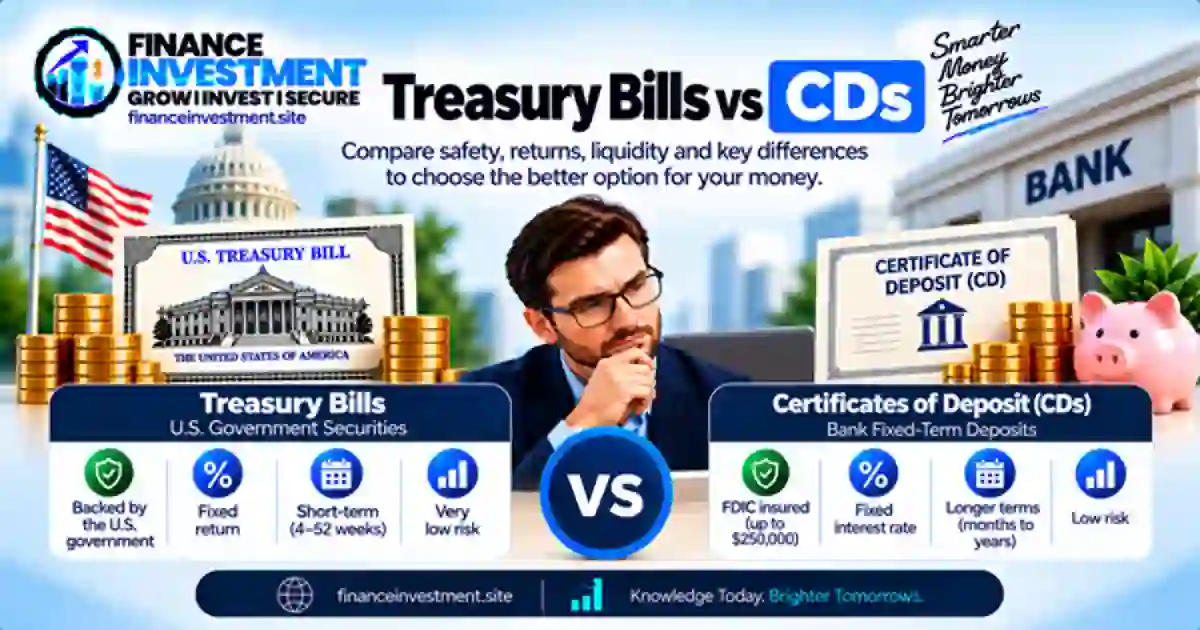
    Treasury Bills vs CDsTreasury Bills vs CDs is a useful comparison when you have cash to put aside and want to earn a return without taking on the volatility of stocks. Both can serve short-term savings goals, but they work differently. A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union.

    The real difference shows up when you look past the advertised rate. The maturity date, access to your money, taxes, insurance, and what happens if your plans change can all affect the outcome. T-bills have maturities of one year or less, while CDs can come with a much wider range of terms.

    What You’ll Learn

    • How Treasury bills and CDs work from purchase to maturity.
    • How U.S. government backing differs from FDIC or NCUA insurance.
    • What can happen when you need your money before maturity.
    • How federal and state taxes can affect your actual return.
    • Which rates, fees, terms, and access rules deserve attention.
    • How to match each option with a short-term financial goal.

    If T-bills are new to you, start with our Treasury Bills Explained guide. It covers the basics before we get into the practical differences between T-bills and CDs.

    Quick Answer: Treasury Bills vs CDs

    Treasury bills and CDs can both fit short-term savings goals, but they are built differently. A T-bill is a short-term U.S. Treasury security with a maturity of one year or less. A CD is a time deposit from a bank or credit union with a specific term and account rules.

    Key Takeaways

    • Different products: T-bills are Treasury securities; CDs are deposit products.
    • Protection differs: T-bills are backed by the U.S. government, while eligible CDs at FDIC-insured banks can receive FDIC insurance within applicable limits.
    • Maturity differs: T-bills mature within one year, while CDs can have terms ranging from short periods to several years.
    • Early access differs: A CD may impose an early-withdrawal penalty. A marketable T-bill can generally be sold before maturity, but its market price may be higher or lower than the purchase price.
    • Taxes matter: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Yield is only one factor: Compare the return with taxes, maturity, insurance, fees, access rules, and your cash timeline.

    BOTTOM LINE: Start with when you expect to need the money. Then compare the current T-bill yield or CD APY, applicable protection, tax treatment, fees, and the consequences of accessing the money early.

    Table of Contents

    Treasury Bills vs CDs at a Glance

    T-bills and CDs can both be used for money you expect to keep relatively stable, but they are structured differently. A T-bill is a marketable U.S. Treasury security with a maturity of one year or less. A CD is a time deposit with a specific term and institution-specific rules.

    BEST FOR

    T-bills may fit a defined cash timeline. CDs may fit savers who are comfortable committing money for a selected term.

    KEY NUMBERS

    T-bills mature in 1 year or less. Standard FDIC coverage is $250,000 per depositor, per insured bank, for each ownership category.

    FeatureTreasury BillsCDs
    ProductU.S. Treasury securityTime deposit at a bank or credit union
    MaturityOne year or lessSpecific term selected when opened
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible credit-union CDs may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the available market priceEarly withdrawal may involve a penalty or other product-specific restrictions
    ReturnFor a bill held to maturity, generally based on purchase price and maturity valueInterest is earned according to the CD’s stated terms

    QUICK TAKE: Don’t stop at the advertised return. Check the maturity, applicable insurance or government backing, taxes, access rules, and what happens if you need the money earlier than planned.

    Treasury Bills vs CDs: A Complete Beginner Guide

    Treasury Bills vs CDsIf you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.

    Treasury Bills in Simple Terms

    T-bills have maturities of one year or less. They are generally issued at a discount to face value, although an auction can result in a price at par. When a discounted bill reaches maturity, you receive its face value, with the difference between your purchase price and the amount received representing the interest earned.

    CDs in Simple Terms

    A certificate of deposit is a time deposit with a selected term. Traditional CDs commonly offer a fixed rate for that term, although the exact terms depend on the institution and CD type. Taking money out before maturity may trigger an early-withdrawal penalty, so the account’s disclosure matters before you open one.

    A SIMPLE WAY TO THINK ABOUT IT: A T-bill is a short-term Treasury security with a maturity date. A CD is a time deposit with a selected term. Once you understand that difference, compare the return, taxes, protection, and access rules.

    How Treasury Bills and CDs Work

    The practical difference becomes clearer when you follow the money from purchase to maturity. A T-bill is issued through a Treasury auction and has a defined maturity. A CD is opened with a bank or credit union for a selected term, with the institution’s terms controlling interest, maturity, and early access.

    How a Treasury Bill Works

    The Treasury sells bills through auctions. T-bills are issued at a discount and redeemed at their face value when they mature. For a discounted bill, the difference between the purchase price and the amount received at maturity is the interest earned. A marketable T-bill can generally be sold before maturity, but the sale price is determined by the market at that time.

    How a CD Works

    With a CD, you deposit money for a stated term and earn interest according to the CD’s terms. When the term ends, the deposit becomes available according to the institution’s maturity rules. If you need the money earlier, the CD agreement determines whether early withdrawal is permitted and what penalty or other restriction may apply.

    THE PRACTICAL DIFFERENCE: With a T-bill, getting out before maturity generally means selling a security at its current market price. With a CD, early access is governed by the deposit agreement and may involve a penalty.

    Treasury Bills vs CDs: Benefits and Drawbacks

    Neither product is automatically the right fit for every cash goal. The useful question is what you value most: a Treasury security with a defined maturity, or a time deposit with institution-specific terms.

    Treasury Bills: Pros and Cons

    PROS
    • Backed by the full faith and credit of the U.S. government.
    • Maturities of one year or less can fit short-term cash planning.
    • Interest is generally exempt from state and local income taxes.
    • Marketable T-bills can generally be sold before maturity.
    CONS
    • An early sale exposes you to the market price at that time.
    • Buying and managing Treasury securities may require more steps than opening a bank CD.
    • T-bills are securities, not FDIC-insured deposits.

    CDs: Pros and Cons

    PROS
    • Traditional CDs commonly provide a fixed rate for a defined term.
    • Different terms can accommodate different savings timelines.
    • Eligible bank CDs can receive FDIC insurance within applicable limits.
    • Eligible CDs at federally insured credit unions can receive NCUA share insurance.
    CONS
    • Early withdrawal may result in a penalty under the CD’s terms.
    • Your money may be less accessible during the selected term.
    • CD interest is generally subject to federal income tax and may also be subject to applicable state or local taxes.

    WHAT MATTERS MOST: A T-bill can be sold before maturity, but its market price can change. A traditional CD can keep its stated rate through the term, but early access may cost you through an early-withdrawal penalty. Your cash timeline should come first.

    Treasury Bills vs CDs: Detailed Comparison

    The headline return is only one piece of the puzzle. When comparing Treasury bills and CDs, look at how each product handles maturity, access, taxes, protection and what happens if your plans change.

    FeatureTreasury BillsCDs
    What you ownA short-term U.S. Treasury securityA time deposit with a bank or credit union
    MaturityOne year or lessThe term selected when the CD is opened
    ReturnFor a discounted bill held to maturity, the purchase price and maturity value determine the returnInterest is earned according to the CD’s stated terms
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible share certificates at federally insured credit unions may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the market price available thenEarly withdrawal depends on the CD agreement and may involve a penalty
    Federal taxInterest is generally subject to federal income taxInterest is generally taxable income
    State & local taxGenerally exempt from state and local income taxesMay be subject to applicable state and local income taxes
    Main trade-offDefined maturity with the ability to sell before maturity at the prevailing market priceDefined deposit term with early-access rules set by the CD

    HOW TO USE THIS TABLE: Start with your expected cash date. Then compare the current return, applicable protection, tax treatment and early-access rules. That gives you a more useful comparison than looking at the advertised rate alone.

    Costs, Risks and Expert Tips

    A good comparison goes beyond the advertised return. Before choosing a T-bill or CD, look at the cost of buying or exiting, the tax treatment, and what could happen if you need the money sooner than expected.

    Costs and Risks to Watch

    • T-bills: TreasuryDirect charges no purchase fee or commission. A broker may have its own charges or terms. Selling before maturity also means accepting the market price available at that time.
    • CDs: Check the specific CD agreement for early-withdrawal provisions, minimum deposit requirements, renewal terms, and any other conditions.
    • Taxes: Compare after-tax returns. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Protection: Confirm whether a CD is held at an FDIC-insured bank or through a federally insured credit union, and check the applicable insurance rules and limits.

    Expert Tips Before You Buy

    1. Start with the date you expect to need the money.
    2. Compare the current T-bill yield with the CD’s APY after considering taxes and applicable costs.
    3. Read the CD disclosure, especially the early-withdrawal and maturity sections.
    4. If buying a T-bill, decide whether you can hold it to maturity or accept the possibility of a different market price if you sell early.

    EXPERT TIP: Don’t compare the rate alone. A slightly higher return may not matter if the product’s maturity, taxes, fees, or early-access rules don’t fit your plans.

    Common Mistakes and a Real-Life Example

    The rate may grab your attention first, but the details can matter more. A few common mistakes can make a T-bill or CD less convenient than expected.

    Common Mistakes to Avoid

    • Looking only at the highest rate: Taxes, fees, maturity and access rules can change the practical value of a return.
    • Ignoring the maturity date: Make sure the T-bill maturity or CD term fits your expected cash date.
    • Confusing selling with withdrawing: A marketable T-bill can generally be sold before maturity at its market price, while a CD follows the withdrawal terms in its agreement.
    • Forgetting tax differences: T-bill interest is generally exempt from state and local income taxes, while CD interest may be subject to applicable state and local taxes.
    • Assuming every CD has identical protection: Check whether the deposit is at an FDIC-insured bank or whether the share certificate is at a federally insured credit union.

    Real-Life Example

    Suppose a couple has $25,000 set aside for a home improvement project they expect to fund in about six months. They could compare a T-bill with a maturity close to that date against a CD whose term fits their timeline.

    They would then compare the current return, taxes, applicable insurance, and early-access rules. If the project date moves, the consequences also matter: selling a T-bill before maturity means accepting its market price, while accessing a CD early depends on the CD’s terms and any applicable penalty.

    KEY LESSON: Choose the time frame first, then compare the return. Matching the product to your cash date can prevent an avoidable early-access problem.

    Who Should Choose Treasury Bills or CDs?

    Your plans for the money can help narrow the choice. Consider how long you can leave it untouched, whether you prefer a Treasury security or a deposit account, and how each product’s terms affect your return.

    Treasury Bills May Fit If:

    • Your spending date matches an available short-term T-bill maturity.
    • You want to hold a security backed by the U.S. government.
    • The state and local income tax treatment matters to you.
    • You can hold until maturity or accept market-price risk if you sell early.

    CDs May Fit If:

    • You want a deposit product with a term suited to your savings goal.
    • You prefer the predictable rate offered by a traditional fixed-rate CD.
    • You can meet the minimum deposit and early-withdrawal conditions.
    • You have confirmed applicable FDIC coverage for an eligible bank CD or NCUA coverage for an eligible credit-union share certificate.

    ONE MORE THING: If you might need this money without warning, neither product should be treated like an everyday spending account. Keep your immediate cash needs in mind before committing to a maturity date or deposit term.

    Frequently Asked Questions About Treasury Bills vs CDs

    1. How do Treasury bills and CDs differ?

    A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union. Their maturity, access, tax treatment and protection work differently.

    2. Are Treasury bills FDIC-insured?

    No. Treasury bills are not FDIC-insured deposits. They are U.S. Treasury securities backed by the full faith and credit of the U.S. government.

    3. Are CDs FDIC-insured?

    An eligible CD at an FDIC-insured bank can receive FDIC coverage within applicable limits. A share certificate at a federally insured credit union may receive NCUA share insurance instead.

    4. Can you sell a Treasury bill before maturity?

    Yes. A marketable T-bill can generally be sold before maturity, but the amount received depends on its market price at the time of sale.

    5. Can you withdraw money from a CD early?

    That depends on the CD’s terms. A traditional CD may allow early withdrawal with a penalty, while certain CD types can have different access rules.

    6. Are Treasury bill earnings exempt from state taxes?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. Do CDs and Treasury bills have the same tax treatment?

    No. T-bill interest generally receives state and local tax exemption. CD interest is generally taxable income and may also be subject to applicable state and local taxes.

    8. Which should you compare for short-term cash?

    Compare the specific T-bill and CD based on your cash date, current return, taxes, fees, access rules and applicable protection. There is no single comparison that fits every situation.

    REMEMBER: A T-bill is a Treasury security, while a CD is a deposit product. Their insurance, tax and early-access rules should be evaluated separately.


    Treasury Bills vs CDs: Final Comparison

    Treasury bills and CDs can both be used for short-term cash planning, but they work in different ways. A T-bill is a short-term U.S. Treasury security with a defined maturity. A CD is a time deposit with a term and conditions set by the financial institution.

    Before comparing them, look at when you need the money, the current return, applicable taxes, protection, and early-access rules. With a T-bill, consider the maturity date and the market price if you sell before maturity. With a CD, review the term, rate, maturity instructions, and early-withdrawal provisions.

    FINAL CHECK: A useful comparison goes beyond the headline rate. Review the cash timeline, access rules, tax treatment, applicable insurance or government backing, and any costs before making a decision.

    For a broader introduction to Treasury securities, read our Treasury Bills Explained guide. You can also compare another short-term cash option in our CD vs Money Market Account guide.

    Have a Money Question? Keep Exploring.

    Understanding the details can make short-term money decisions easier to compare. Keep exploring FinanceInvestment for practical guides on Treasury bills, CDs, and other personal finance topics.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover?

    Email FinanceInvestment

    Continue Your Research