Tag: Savings Goals

  • Treasury Bills for Short-Term Savings Goals: 2026 Guide

    Treasury Bills for Short-Term Savings Goals: 2026 Guide

    Treasury Bills for Short-Term Savings Goals

    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 26, 2026


    Updated: Sep 26, 2026


    Reading Time: 12–14 min


    Treasury Bills for Short-Term Savings Goals: Matching Your Money to the Date You Need It
    Treasury Bills for Short-Term Savings Goals Treasury Bills for Short-Term Savings Goals can make sense when you are setting money aside for something you expect to pay for within the next several months or year. Maybe you are building a down payment, planning a family vacation, replacing a vehicle, paying a large insurance bill, or preparing for a tuition payment. Unlike a general savings balance, this money already has a purpose.

    That makes the timing especially important. Treasury bills are short-term U.S. government securities with specific maturity dates. So instead of looking at the yield first, it can be more useful to start with the date you expect to need the money. The closer the investment timeline matches the goal, the easier it becomes to plan around the maturity.

    If Treasury bills are new to you, our Treasury Bills Explained guide covers the basics, including what T-bills are and how they work.

    What You’ll Learn

    • How Treasury bills can fit different short-term savings goals.
    • How to think about maturity dates when a future expense has a known deadline.
    • Why access to your money still matters even when you have a planned goal.
    • How T-bills compare with savings accounts, money market accounts and CDs.
    • How taxes, early sales and changing rates can affect the amount available for your goal.
    • Which common mistakes can make a short-term savings strategy harder to manage.

    The idea is straightforward: give your short-term savings a clear purpose and choose an option that fits the date and access you need. A T-bill can be part of that plan, but the maturity should work with your goal rather than the other way around.

    Quick Answer: Can Treasury Bills Work for Short-Term Savings Goals?

    Yes, Treasury bills can fit certain short-term savings goals when the maturity date works with the date you expect to need the money. They can provide a defined timeline for money set aside for a planned expense. But a T-bill is a security, not a bank-account balance. If you need the funds before maturity, a marketable T-bill can generally be sold, but its market price may differ from what you originally paid.

    Key Takeaways

    • Begin with the goal date: Know roughly when the money will be needed before choosing a T-bill term.
    • Match the maturity: The bill’s maturity should fit comfortably within your planned savings timeline.
    • Leave room for changes: A planned expense can move earlier, later, or change in size.
    • Know what you are buying: T-bills are Treasury securities, not FDIC-insured bank deposits.
    • Understand early-sale risk: Selling before maturity can expose you to changes in the T-bill’s market price.
    • Watch the next rate: Reinvesting after maturity does not guarantee the same yield as the original bill.
    • Remember the tax difference: Treasury interest is generally subject to federal income tax and generally exempt from state and local income taxes.

    BOTTOM LINE: Treasury bills can be one option for money with a defined short-term purpose. The important part is to make the maturity work around your savings goal, while keeping enough accessible money for expenses that may arrive sooner than expected.

    Table of Contents

    Treasury Bills for Short-Term Savings Goals at a Glance

    Treasury bills can fit a short-term savings plan when you have a defined goal and a reasonably clear spending timeline. Because a T-bill has a set maturity date, the calendar matters almost as much as the return. A useful starting point is to decide when the money will be needed and how much flexibility you have around that date.

    Quick FactWhat It Means for Your Savings Goal
    Best ForPlanned expenses where the money can remain invested for a defined short period.
    Key NumberTreasury bills have maturities of one year or less.
    Planning WindowChoose a maturity that gives you enough time to reach the goal without creating an awkward cash gap.
    Before MaturityA marketable T-bill can generally be sold before maturity, but its market price can change.
    Tax TreatmentTreasury interest is generally subject to federal income tax and exempt from state and local income taxes.
    Main Planning CheckAsk whether you can leave the money invested until the selected maturity date.

    Examples of Short-Term Savings Goals

    A planned vehicle purchase, vacation, home repair, insurance premium, tuition payment, or estimated tax bill could have a defined spending date. For these goals, the important comparison is not simply which option offers a higher return. You also need to consider access, timing, taxes, and what happens if the expense moves earlier than expected.

    Complete Beginner Guide to Using Treasury Bills for Short-Term Savings Goals
    Treasury Bills for Short-Term Savings GoalsIf Treasury bills are new to you, begin with the goal rather than the security. Write down what you are saving for, the amount you expect to need, and roughly when you expect to spend it. Once those three pieces are clear, you can decide whether a T-bill fits the timeline.

    1. Define the Goal and Target Amount

    Start with a realistic estimate. For example, if you are building a $12,000 fund for a vehicle purchase, consider whether the final cost could change before you buy. Also decide whether the entire amount needs to be available on one date or whether you may spend it in stages.

    2. Mark the Expected Spending Date

    Put the expected payment date on your calendar. If the deadline is firm, leave some room between the T-bill maturity and the actual payment date. That cushion can help if the purchase date changes or the funds take time to become available through your chosen account.

    3. Choose a Term That Fits the Timeline

    Treasury bills are short-term securities with defined maturities. Compare the available term with your goal date and ask how long you can comfortably leave the money invested. A maturity that looks convenient on paper may be less useful if your spending date is uncertain.

    4. Decide Where to Buy and Hold the T-Bill

    Treasury bills can be purchased through TreasuryDirect or through a brokerage that offers Treasury securities. Before buying, check how the account handles maturity proceeds and what you would need to do if your plans change. Our How to Buy Treasury Bills guide covers the basic purchase process.

    5. Recheck the Goal Before Maturity

    As maturity approaches, look at the original goal again. If the expense is coming up, the proceeds may need to remain accessible. If the goal has been delayed, you can reassess the money instead of automatically rolling it into another T-bill.

    BEGINNER TIP: Put the goal date on your calendar before you buy the T-bill. The investment should fit your timeline, including a reasonable cushion, rather than making the timeline fit the investment.

    How Treasury Bills Work for Short-Term Savings Goals

    A Treasury bill is a short-term debt security issued by the U.S. Department of the Treasury. T-bills mature in one year or less, so the maturity date becomes an important part of any plan built around a future expense.

    1. You Buy the Bill at a Discount

    T-bills are generally issued at a price below their face value. You pay the purchase price when you buy the bill. If you hold it until maturity, the Treasury pays the face value according to the security’s terms. The difference between the purchase price and face value represents the bill’s discount.

    2. The Auction Establishes the Price

    Treasury bills are sold through auctions. A noncompetitive bidder does not choose a specific discount rate. Instead, the investor agrees to accept the rate determined by the auction and receives the requested amount, subject to the Treasury’s auction rules.

    That auction process is why the amount paid for a T-bill can be below its face value. Treasury bills do not send regular interest payments during the term like many coupon-paying bonds. The return is reflected in the difference between the purchase price and the amount paid at maturity.

    3. Maturity Creates a Planned Cash Point

    When the T-bill reaches maturity, it becomes due and the face value is paid according to its terms. For a short-term savings goal, this creates a specific point when the invested money can be directed toward the planned expense.

    4. Selling Before Maturity Changes the Calculation

    A marketable T-bill can generally be sold before maturity through the secondary market. However, the price at that time can be different from what you originally paid. Changes in market interest rates can affect the security’s market value, so an early sale may produce a different result from simply holding the bill to maturity.

    5. The Goal Date Still Comes First

    For goal-based saving, the mechanics are useful only when they fit the plan. If you expect to spend the money around a particular date, consider the maturity date, the time needed to access the proceeds, and what you would do if the expense arrives earlier than expected.

    PRACTICAL POINT: A T-bill has a purchase date, a maturity date and a market value between those dates. For a short-term savings goal, keeping track of all three helps you understand what your money is doing before the planned expense arrives.

    Benefits and Drawbacks of Using Treasury Bills for Short-Term Savings Goals

    Treasury bills can work well with some planned savings goals, but they come with a different set of trade-offs than an ordinary savings account. Their defined maturity can help organize money for a future expense, while the security’s market value and access process matter if your plans change.

    Potential Benefits

    • Defined maturity: A known maturity date can help you organize savings around a planned expense.
    • Short-term terms: T-bills have maturities of one year or less, which can fit certain near-term goals.
    • U.S. Treasury security: T-bills are securities issued by the U.S. Department of the Treasury.
    • State and local tax treatment: Treasury interest is generally exempt from state and local income taxes.

    Potential Drawbacks

    • Less convenient than cash: A T-bill follows a security and maturity process rather than working like an ordinary bank-account balance.
    • Early-sale market risk: If you sell before maturity, the market price may differ from your original purchase price.
    • Changing goal dates: An expense may arise earlier than expected, creating a need for funds before maturity.
    • Reinvestment uncertainty: A new T-bill purchased after maturity may have a different yield.

    WATCH THE TIMING: Even a carefully planned savings goal can move. Before buying a T-bill, consider whether you have another accessible source of money if the expense arrives sooner than expected.

    Treasury Bills vs. Other Short-Term Savings Options

    When you are saving for a near-term expense, the product should match the way you expect to use the money. Treasury bills have a defined maturity, while savings accounts and money market deposit accounts generally do not. CDs also have a set term, but their withdrawal rules are different from those of Treasury securities.

    OptionAccessTime StructureFDIC InsurancePotential Use
    Treasury BillsHold to maturity or sell a marketable bill before maturityDefined maturity of one year or lessNoA planned goal that can accommodate a defined maturity
    Savings AccountGenerally convenient access, subject to account termsNo fixed maturityGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsGoals where flexibility and access matter
    Money Market Deposit AccountGenerally convenient access, subject to account termsNo fixed maturityGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsSavings that may need accessible cash features
    Certificate of DepositAccess before maturity depends on the CD’s terms and may involve an early-withdrawal penaltyFixed termGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsMoney that can remain committed for a specified period

    QUICK COMPARISON: Treasury bills and CDs both have defined terms, while savings accounts and money market deposit accounts generally do not. T-bills are Treasury securities rather than FDIC-insured deposits. The useful choice depends on your goal date, access needs, and the rules attached to the account or security.

    Costs, Risks and Expert Tips for Short-Term Savings Goals

    Before putting money into a Treasury bill, look beyond the advertised yield. Your decision can involve account costs, tax treatment, access rules, market prices and the timing of the expense you are saving for.

    Costs and Financial Considerations

    • TreasuryDirect purchases: The U.S. Treasury states that it does not charge a purchase fee or commission when you buy Treasury securities through TreasuryDirect.
    • Brokerage charges: Costs and trading policies can vary by brokerage, so check the firm’s current terms before placing an order.
    • Taxes: Treasury interest is generally subject to federal income tax but generally exempt from state and local income taxes.

    Risks to Keep in Mind

    • Timing risk: The savings goal could arrive before the T-bill reaches maturity.
    • Market-price risk: If you sell a marketable T-bill before maturity, the amount received can differ from the original purchase price.
    • Reinvestment risk: If you use the proceeds to buy another T-bill, the new security may have a different yield.
    • Access risk: The steps for getting money before maturity can depend on whether the T-bill is held through TreasuryDirect or a brokerage.

    EXPERT TIP: If a savings goal has a firm payment date, give yourself a cushion. A T-bill that matures shortly before the expense can provide more breathing room than one scheduled to mature on the exact day you need the money.

    Common Mistakes and a Real-Life Short-Term Savings Example

    A short-term savings plan can become complicated when the investment gets more attention than the goal itself. With Treasury bills, the most common mistakes involve timing, access and what happens after the bill matures.

    Common Mistakes to Avoid

    • Choosing the maturity first: Picking a T-bill term before identifying the date you expect to spend the money can put the investment schedule ahead of the actual goal.
    • Putting the entire goal amount into one bill: If the spending date changes, having no other accessible funds can make the plan less flexible.
    • Using the exact payment date as the maturity date: A little time between maturity and the planned expense can give you more breathing room.
    • Assuming early sale works like a withdrawal: Selling a marketable T-bill before maturity is a market transaction, and the price can differ from the original purchase price.
    • Reinvesting without checking the goal: Once a T-bill matures, first ask whether the money is still needed for the original purpose before buying another one.

    Illustrative Example: A $15,000 Home Project

    Imagine a family expects to spend $15,000 on a home renovation several months from now. Instead of starting with a T-bill maturity, they first estimate when the contractor will need the money. They can then compare that date with available T-bill terms and decide whether the timing gives them enough room.

    If the renovation is delayed, the family can reassess the money when the T-bill matures rather than automatically reinvesting it. If the project moves forward earlier, an accessible cash reserve can reduce the need to sell the T-bill before maturity.

    IMPORTANT: The $15,000 figure is only an illustration. It is not a recommended amount or allocation. A short-term savings plan should reflect the actual goal, payment date, available cash and personal circumstances.

    Who Should Consider Treasury Bills for Short-Term Savings Goals?

    Treasury bills may fit savers who have a defined goal, a reasonably clear timeline and enough flexibility to leave the money invested until maturity. The main question is not simply how much a T-bill may earn. It is whether its maturity and access characteristics fit the way the money will be used.

    This Approach May Fit

    • People saving for a planned expense within one year who can work with a defined maturity date.
    • Families setting aside money for expenses such as tuition, insurance payments, travel or a planned purchase.
    • Savers who want to keep money for a specific goal separate from their everyday spending funds.
    • Investors who understand that selling a marketable T-bill before maturity can result in a market price different from the original purchase price.

    When Another Option May Fit Better

    A savings account or money market deposit account may fit better when the spending date is uncertain and convenient access to cash is a priority. A CD may also be worth comparing when you are comfortable with a fixed term and want to consider bank-deposit features. The useful comparison depends on the goal, timeline, access needs and account or security terms.

    QUICK CHECK: Before choosing a T-bill, ask three questions: When will I need the money? Can I leave it invested until maturity? What other accessible funds would I have if the goal arrives earlier?

    Frequently Asked Questions About Treasury Bills for Short-Term Savings Goals

    Are Treasury bills suitable for short-term savings goals?

    Treasury bills can fit a short-term savings goal when the maturity date lines up with the expected spending timeline. They may be less convenient when the money could be needed unexpectedly before maturity.

    What is the shortest Treasury bill term?

    Treasury bills are available in several short-term maturities, including 4-week, 6-week, 8-week, 13-week, 17-week, 26-week and 52-week bills. Availability can depend on the Treasury’s current offerings.

    Can I sell a Treasury bill before maturity?

    Yes, a marketable Treasury bill can generally be sold before maturity. If the bill is held in TreasuryDirect, however, it must first be transferred to a bank, broker or dealer because TreasuryDirect does not directly sell marketable securities for you. A TreasuryDirect purchase also has a 45-day holding period before a newly issued marketable security can generally be transferred or sold.

    Are Treasury bills taxable?

    Interest income from Treasury bills is subject to federal income tax but is exempt from state and local income taxes. Treasury bill interest is reported as Treasury interest on Form 1099-INT.

    Are Treasury bills FDIC insured?

    No. Treasury bills are securities issued by the U.S. Treasury, not deposits at an FDIC-insured bank. They therefore do not receive FDIC deposit insurance.

    What happens when a Treasury bill matures?

    At maturity, the Treasury pays the bill’s face value according to its terms. If you hold the bill through TreasuryDirect, you can generally receive the proceeds or arrange for the money to be reinvested in another Treasury security. The appropriate choice depends on whether the original savings goal still requires the money.

    FAQ TIP: For a short-term savings goal, check the maturity date, access rules, tax treatment and planned spending date together. Looking at only the quoted yield can leave out details that matter to the goal.


    Final Verdict: Evaluating Treasury Bills for a Short-Term Savings Goal

    Treasury bills can be considered for a short-term savings goal when the amount has a defined purpose and the selected maturity fits the expected spending timeline. The fixed maturity provides a specific date for planning, while the security’s access and market-price characteristics need to be considered if plans change.

    They are different from an ordinary savings balance. If the goal date is uncertain or the money may be needed before maturity, a savings account or money market deposit account offers a different access structure. A CD can also be compared when a fixed bank-deposit term fits the planned use of the money.

    THE KEY IDEA: Start with the purpose and expected date for the money. Then consider the T-bill’s maturity, access options, tax treatment and potential risks before deciding how it fits into the savings plan.

    The goal is to keep the investment timeline aligned with the planned use of the money. If the timeline, access needs or purpose changes, reassess the savings arrangement rather than assuming the original plan still fits.

    Have a Money Question? Keep Exploring.

    A short-term savings goal becomes easier to plan when you know when the money is needed, how much access you may require and when your investment matures. Keep those details in view as you compare your options.

    📩 Get in Touch With FinanceInvestment

    Email FinanceInvestment

    Continue Your Research

    Treasury Bills Explained
    •
    How to Buy Treasury Bills

  • How to Use CDs for Short-Term Financial Goals in 2026

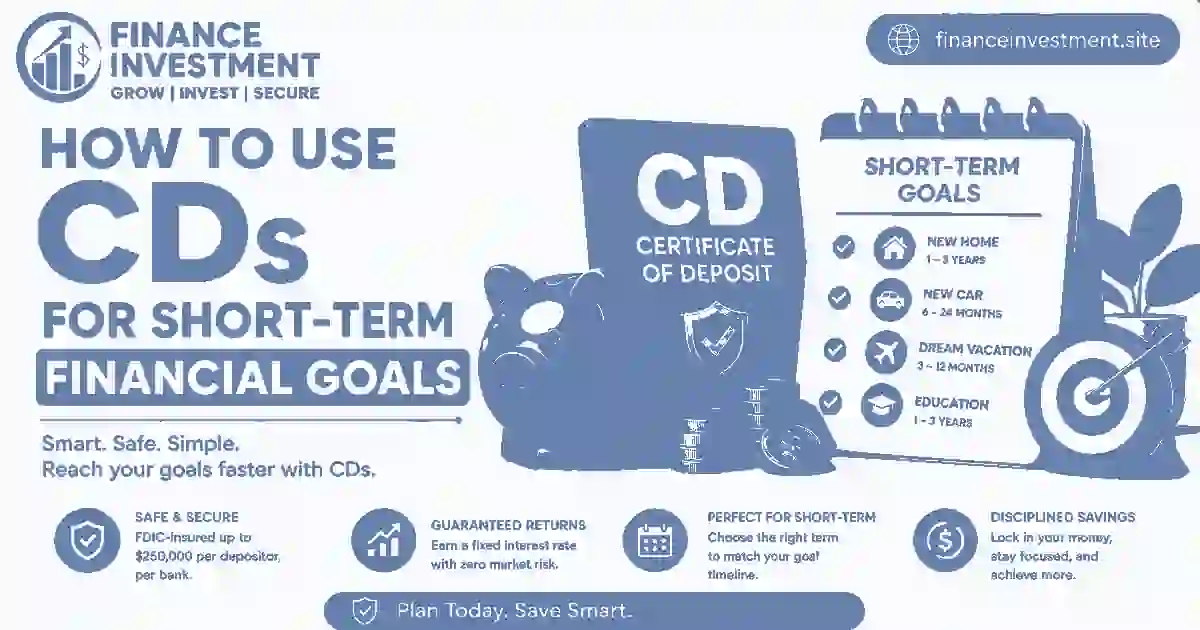
    How to Use CDs for Short-Term Financial Goals in 2026

    FINANCEINVESTMENT • CD GUIDE 2026

    How to Use CDs for Short-Term Financial Goals

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August,24, 2026.
    About 10–12 min read

    A practical guide to using certificates of deposit for money you expect to need within a defined short-term time frame.

    How to Use CDs for Short-Term Financial Goals in 2026
    Learn how to use CDs for short-term financial goals, choose the right CD term, protect your cash needs, and avoid locking up money too early.
    how-to-use-cds-for-short-term-financial-goals
    How to Use CDs for Short-Term Financial Goals
    short-term CD strategy,
    CDs for short-term goals,
    short-term savings with CDs,
    CD for a financial goal,
    short-term savings goals,
    CD maturity planning,
    choosing a CD term,
    short-term certificate of deposit
    https://financeinvestment.site/how-to-use-cds-for-short-term-financial-goals/
    Subhash Rukade
    August 23, 2026
    About 10–12 minutes

    Use the Deadline to Choose the CD, Not Just the Rate

    How to Use CDs for Short-Term Financial GoalsHow to Use CDs for Short-Term Financial Goals starts with a simple question: When will I actually need this money? If you know the answer, choosing a CD term becomes much easier. A certificate that matures after your goal arrives may offer a good APY, but it may be a poor fit if your cash is needed sooner.

    Think about a planned expense such as a car purchase, tuition bill, home repair, annual insurance payment, or a family trip. These goals have something in common: the money has a job and a deadline. A CD can give that cash a defined timeline while potentially earning more than leaving it completely idle.

    The key is to work backward from the date. If you need the money in six months, a five-year CD is obviously out of step. Even a one-year certificate may create a problem if the expense cannot wait. Early withdrawal can also reduce the benefit of using a CD in the first place.

    Before choosing a term, it helps to understand how CDs fit into a broader savings plan. Our CD Guide 2026 provides that bigger picture.

    What You’ll Learn

    • How to match a CD term with a financial deadline
    • When a short-term CD can make sense
    • Why the highest APY may not be the best choice
    • How to plan around maturity dates
    • When a flexible savings account may be better

    Quick Answer: Are CDs Good for Short-Term Financial Goals?

    Yes, a CD can work well for a short-term financial goal when you know roughly when the money will be needed and choose a maturity date that fits. The goal is to earn interest without creating a cash-access problem.

    6 Key Takeaways

    1. Start with the deadline: Know when the money must be available before choosing a CD term.
    2. Match maturity to the goal: A CD that matures too late can be inconvenient, even with a strong APY.
    3. Compare flexibility: A high-yield savings account may be better when the spending date could change.
    4. Don’t chase APY alone: Consider the term, withdrawal rules, and actual dollar earnings together.
    5. Keep emergency cash separate: A CD should not replace money you may need immediately.
    6. Plan the next step: Know where the money will go when the CD matures instead of making the decision at the last minute.

    Bottom line: A short-term CD works best when the maturity date fits the purpose of the money. The best rate is useful only if the timing works, too.

    Short-Term CD Planning at a Glance

    A useful way to think about a short-term CD is to start with the calendar. The closer your financial goal is, the more important access and timing become. The table below gives a simple starting framework rather than a one-size-fits-all rule.

    Financial GoalPossible CD TermMain Consideration
    3–6 months
    Planned bill or near-term purchase
    3–6 month CD, where availableKeep the maturity date comfortably before the money is needed.
    6–12 months
    Tuition, insurance or planned purchase
    6-month or 1-year CDLeave enough time after maturity to move or spend the funds.
    12–18 months
    Longer planned expense
    1-year or 18-month CDConsider whether the goal date could move before locking in.

    Key number: Give yourself a timing cushion. If a goal requires $10,000 on June 1, a certificate maturing close to that date may leave little room for delays. A flexible account can be more appropriate when the spending date is uncertain.

    Complete Beginner Guide to Using CDs for Short-Term Goals

    A CD becomes useful for a short-term goal when three things line up: you know approximately how much the goal will cost, you have a reasonable spending date, and you can leave the deposited money alone until the certificate matures.

    Define the Amount Before Shopping for a CD

    Start with the expense rather than the bank’s advertised rate. If you expect a home project to cost $6,000 next spring, decide how much of that $6,000 is already saved and how much can safely be committed. This keeps the CD tied to a real purpose instead of turning rate shopping into the goal itself.

    Work Backward From the Spending Date

    Give the maturity date some breathing room. Money needed on a specific day generally should not be locked in a certificate that matures that same morning. Allow time to receive maturity instructions, move the funds, and handle any unexpected delay.

    Use Different Maturities for Different Goals

    If several expenses are coming at different times, you do not have to put everything into one CD. A simple ladder can split the cash among certificates with different maturity dates. For example, money needed in six months can sit separately from money earmarked for next year. Each portion then has its own timeline.

    Consider a No-Penalty CD When Timing Is Less Certain

    A no-penalty CD may provide more flexibility because qualifying withdrawals can be made without the traditional early-withdrawal penalty, subject to the institution’s rules. Compare its APY and withdrawal conditions with standard CDs and liquid savings options before choosing it.

    Keep Emergency Savings Outside the Plan

    Your short-term goal fund and emergency fund serve different purposes. A vacation, vehicle purchase, or planned renovation can often wait or change. An urgent medical bill or home repair may not. Keeping emergency cash readily accessible helps prevent an unexpected expense from forcing you to break a CD early.

    How a Short-Term CD Strategy Works

    A short-term CD strategy works best when the certificate is treated as part of a timeline, not as a permanent home for your cash. You decide what the money is for, when you need it, and then build the CD around those facts.

    Step 1: Set the Goal Amount

    Write down the amount you expect to need. If the target is $8,000, decide whether the full amount is ready now or whether you are still saving toward it. This also helps you avoid committing money that belongs to another priority.

    Step 2: Mark the Date on Your Calendar

    Choose the date when the money should be available. Then work backward to find a suitable CD term. A small cushion between maturity and the actual expense can make the plan easier to manage.

    Step 3: Fund the Certificate

    After comparing APY, term, withdrawal rules, and other conditions, open the CD and transfer the amount you have decided to commit. Save the account confirmation and maturity date so you can review the plan later.

    Step 4: Track Maturity

    Don’t wait until maturity morning to think about the next move. Check the institution’s maturity and renewal rules in advance. Some CDs automatically renew if you do nothing during the applicable grace period.

    Illustrative Example

    Maya expects to spend $5,000 on a home improvement project in about eight months. She keeps her emergency reserve separate and places the goal money into a suitable shorter-term CD. Rather than choosing a certificate that matures after the project date, she selects one that gives her time to access the funds before the contractor needs payment. When the CD matures, she reviews the proceeds and moves the money toward the project instead of automatically renewing it.

    The final step is simple but important: match the maturity decision to the goal. If the expense has arrived, use the money. If the date has changed, reassess. A CD strategy should adapt to the goal rather than lock you into a decision you no longer need.

    Benefits & Drawbacks of Using CDs for Short-Term Goals

    A CD can bring structure to money that already has a purpose. But that structure comes with trade-offs. The biggest question is whether the benefit of a defined return outweighs the loss of easy access.

    ✓ Pros

    • Predictable return: A fixed-rate CD can make the expected interest easier to estimate.
    • Defined timeline: The maturity date gives the savings a clear finish line.
    • Goal separation: Moving goal money into a separate certificate can reduce the temptation to spend it elsewhere.
    • Potentially stronger yield: Depending on current rates, a CD may offer more interest than leaving the same cash in a low-yield account.

    △ Cons

    • Early-withdrawal risk: Taking money out before maturity may trigger a penalty on a standard CD.
    • Timing mismatch: A goal can move, but the original maturity date does not necessarily move with it.
    • Inflation risk: Rising prices can reduce the purchasing power of the money while it is locked in.
    • Reinvestment risk: When the CD matures, comparable rates may be lower if you still need to save the money.

    The strongest case for a CD is money with a reasonably predictable purpose and timeline. If either one is uncertain, flexibility may deserve more weight than a slightly higher rate.

    Short-Term Savings Comparison: CD vs Other Options

    A CD is only one way to park money for a near-term goal. The better choice depends on how certain your spending date is and how quickly you might need access to the cash.

    OptionBest FitLiquidityReturn Characteristics
    CDKnown goal dateLimited before maturityOften fixed for the selected term
    High-yield savingsUncertain timingGenerally highVariable rate
    Treasury billsShort government-backed investment horizonDepends on whether held to maturity or soldYield set by market conditions
    Money market deposit accountSavings with easier accessGenerally highVariable rate

    If your goal date is firm, a CD can provide a useful fixed timeline. If the date could move, a high-yield savings account may give you more room to adjust. For short government securities, Treasury bills offer another route, but their market and tax characteristics differ from bank CDs.

    Before committing cash, also consider how FDIC insurance applies to CDs. Protection, access, maturity, and return should be considered together rather than comparing APYs alone.

    Costs, Risks & Expert Tips for Short-Term CD Planning

    The biggest risk with a short-term CD is not usually the rate itself. It is choosing a certificate that does not fit what happens around the goal. A little planning can prevent a good savings idea from becoming inconvenient later.

    Know the Cost of Changing Your Mind

    A standard CD may charge an early-withdrawal penalty if you need the money before maturity. That matters when the spending date is only an estimate. Review the penalty before opening the certificate, especially if the goal could move forward unexpectedly.

    Consider What the Cash Could Do Elsewhere

    Locking money into a CD has an opportunity cost. You may give up access to a savings account or another option that could become more attractive while your CD is running. Inflation also matters because a fixed return does not guarantee the same purchasing power when prices rise.

    Plan for the Rate After Maturity

    Rates may be different when your CD matures. If you still need the money for a later goal, the next available CD could offer a lower yield. A short CD ladder can spread maturity dates and reduce the chance that every dollar reaches maturity at the same time.

    Don’t Forget Taxes

    Interest from a taxable CD is generally subject to federal income tax, and state or local taxes may also apply. Factor the after-tax return into your planning rather than treating the advertised APY as the entire gain.

    Give the Money a Job After Maturity

    Before the CD matures, decide whether the money will be spent, transferred to savings, or placed into another investment. This prevents an automatic renewal from making the decision for you.

    Premium Expert Tip

    Build the exit plan when you open the CD. Put the maturity date on your calendar, note the renewal rules, and decide where the proceeds should go. A CD works best when the ending date is part of the strategy from day one.

    Common Mistakes When Using CDs for Short-Term Goals

    A short-term CD can be simple to manage, but small planning errors can make the money harder to use when the goal arrives. The most common problems happen when the certificate is chosen around the rate instead of the purpose.

    Mistakes Worth Avoiding

    • Ignoring the exact goal date: A CD that matures after the money is needed can create unnecessary pressure.
    • Locking up flexible cash: If an expense could happen earlier than expected, consider whether a standard CD gives you enough access.
    • Skipping the withdrawal rules: Understand the early-withdrawal penalty before committing the money.
    • Letting the CD renew automatically: Check maturity instructions before the certificate reaches its end date.
    • Ignoring taxes and inflation: The advertised APY does not tell the whole story about what the money will be worth after taxes and rising prices.
    • Putting every goal on one maturity date: Separate maturity dates can make several upcoming expenses easier to manage.

    Real-Life Example: Jordan’s Wedding Fund

    Jordan has $7,500 saved for a wedding planned about nine months from now. He finds a longer CD with a slightly higher rate and considers using it because the APY looks attractive.

    Illustrative calculation only: If the longer CD produced an extra $60 of interest compared with a suitable shorter certificate, that additional return would still need to be weighed against the risk of needing the money before maturity.

    Jordan chooses a maturity date that fits his planned spending window instead. The decision gives the goal a clearer path without making a small rate difference the main priority.

    Practical lesson: A CD should make a short-term goal easier to fund, not harder to access. Choose the certificate around the date and purpose of the money first, then use the APY to refine the choice.

    Who Should Use CDs for Short-Term Goals?

    CDs tend to fit best when the purpose of the money is clear and the spending date is reasonably predictable. They are less useful when you may need the cash at any moment.

    Good Candidates for a Short-Term CD

    Goal-based savers can use CDs for planned expenses such as tuition, a vehicle purchase, a home project, or an annual bill. Families may also find them useful when several known expenses are coming at different times.

    Conservative investors who value a defined return may appreciate having a specific maturity date. The strategy is especially comfortable for people who already have a separate emergency reserve and can leave the CD untouched until maturity.

    Who May Prefer Flexible Savings?

    If your income is unpredictable, your emergency fund is incomplete, or the spending date could change suddenly, a liquid savings account may be a better fit. Flexibility can be more valuable than squeezing out a little extra interest.

    Quick Decision Guide

    Firm date + separate emergency fund + money can stay untouched? A CD may fit. Uncertain date or frequent access needed? Keep the money flexible. Several future expenses? Consider different maturity dates.

    Frequently Asked Questions About CDs for Short-Term Goals

    Are CDs good for short-term goals?

    They can be useful when you know when the money will be needed and can leave it untouched until maturity. A CD is less suitable when the spending date is uncertain.

    What CD term is best for short-term savings?

    There is no single best term. Choose one that matures before you need the money, while leaving enough time to access the proceeds and complete the planned expense.

    Can I use a 6-month CD for a financial goal?

    Yes. A 6-month CD can fit a goal that is several months away, provided the maturity date works with your actual spending schedule.

    Is a 1-year CD considered short term?

    For many savers, a one-year CD can serve a short-term or near-term goal. The important point is whether the one-year maturity matches when you expect to need the funds.

    What if I need the money before maturity?

    A standard CD may impose an early-withdrawal penalty. Review the certificate’s rules before opening it. A liquid savings account or no-penalty CD may provide more flexibility.

    Are no-penalty CDs useful?

    They can be useful when your goal date is not completely certain. However, compare the APY, withdrawal conditions, and other account terms before choosing one.

    Should emergency funds go into CDs?

    Usually, emergency money is better kept readily accessible. A CD can restrict access, which may be inconvenient when an unexpected expense requires immediate cash.

    Can I create a CD ladder for short-term goals?

    Yes. You can divide money among CDs with different maturity dates. This can help coordinate several upcoming expenses without putting the entire balance behind one maturity date.

    What happens when a CD matures?

    The principal and applicable interest become available according to the institution’s maturity rules. Some CDs automatically renew if you do not provide different instructions during the applicable grace period.

    Illustrative: How much can a short-term CD earn?

    Illustrative calculation only: A $5,000 CD earning a hypothetical 4% APY for six months would produce roughly $99 of interest before taxes, assuming simple half-year proportional earnings. Actual results depend on the CD’s APY, compounding, and terms.

    Final Verdict: Use the CD to Serve the Goal

    Short-term CDs can be a useful choice when you have a defined financial goal, a reasonably firm spending date, and enough separate cash to handle unexpected expenses. The certificate should fit the timeline of the goal rather than forcing the goal to fit the certificate.

    Start with the date you expect to need the money. Then compare CD terms that mature early enough to give you a practical window for accessing the proceeds. After that, look at APY, minimum deposits, withdrawal rules, and other account terms.

    A higher APY is not automatically the better deal. If it comes with a maturity date that is too late or makes your money harder to access, the extra interest may not be worth the trade-off. When the spending date is uncertain, a flexible savings option can make more sense.

    For a broader look at CD terms, rates, safety, and strategy, explore our CD Guide 2026.

    Practical takeaway: Choose the CD that reaches the finish line when your financial goal does. Once the timing works, use the rate to make the final choice.

    FINANCEINVESTMENT

    Make Your Next Savings Goal Easier

    If you enjoy practical guidance on CDs, savings, and investing, you can join the FinanceInvestment newsletter for simple ideas you can use when planning your next financial goal.

    📧 subhashr325@gmail.com

    A good short-term savings plan gives every dollar a purpose while leaving enough room for real life to change.

  • Common Savings Account Mistakes to Avoid in 2026

    Common Savings Account Mistakes to Avoid in 2026


    ✓ Updated for July 30,2026

    Finance Investment Editorial Team

    Every guide is researched using trusted financial sources and reviewed to help U.S. readers make informed money decisions with confidence.

    📅 Updated: July 30,2026

    ⏱️ 12–15 Min Read

    🇺🇸 USA Edition

    💰

    Finance Investment

    Trusted Personal Finance Guides. Author, Subhash Rukade.


    2026 Savings Guide

    Common Savings Account Mistakes to Avoid in 2026

    Common Savings Account Mistakes to AvoidA savings account should help your money grow, but small mistakes can quietly reduce your earnings. Many people keep cash in low-interest accounts, overlook fees, ignore APY changes, or leave their savings sitting without a clear plan.Common Savings Account Mistakes to Avoid These habits may seem harmless, yet they can cost hundreds of dollars over time.

    This guide explains the common savings account mistakes to avoid and shows practical ways to make smarter banking decisions.”Common Savings Account Mistakes to Avoid” Whether you’re opening your first account or reviewing an existing one, you’ll find simple tips that can help you keep more of your money working for you.

    If you’re still looking for the right account, start with our complete guide to

    High-Yield Savings Accounts USA

    to learn how to compare options and choose an account that fits your financial goals.

    What You’ll Learn

    • Why many Americans earn less interest than they could.
    • The most common savings account mistakes and how to avoid them.
    • Simple habits that can help your savings grow faster.
    • When it makes sense to switch to a better savings account.
    • Tips to protect your savings while planning for future financial goals.


    Quick Answer & Key Takeaways

    Quick Answer

    The common savings account mistakes to avoid include keeping money in a low-interest account, ignoring APY changes, paying avoidable fees, withdrawing savings too often, and never reviewing your account.”Common Savings Account Mistakes to Avoid” Fixing these habits can help you earn more interest, protect your savings, and make better use of every dollar you set aside.

    Key Takeaways

    • Choose a savings account that offers a competitive APY instead of settling for a very low rate.
    • Review your account regularly because banks can change interest rates over time.
    • Avoid unnecessary fees that reduce the money you’ve worked hard to save.
    • Build a habit of adding to your savings consistently, even if the amount is small.
    • Compare banks every year to make sure your account still meets your needs.
    • Understand your account rules before making frequent withdrawals or transfers.

    Bottom Line

    Avoiding a few simple mistakes can make a real difference to your savings.”Common Savings Account Mistakes to Avoid” Paying attention to interest rates, fees, and your saving habits gives your money a better chance to grow while helping you stay prepared for future financial goals.


    Table of Contents


    At a Glance

    Most savings account mistakes are easy to avoid once you know what to watch for. Many people lose potential interest by leaving money in low-paying accounts, overlooking fees, or forgetting to compare better options.”Common Savings Account Mistakes to Avoid” A quick review of your account once or twice a year can help you keep more of your money and avoid unnecessary costs.

    CategorySummary
    Best ForAnyone who wants to protect savings and earn more interest.
    Common MistakeKeeping money in a low-interest savings account for years.
    Potential BenefitHigher interest earnings with better savings habits.
    Time NeededAbout 15–30 minutes to review or switch accounts.
    DifficultyBeginner Friendly
    Main GoalAvoid costly mistakes and help your savings grow more efficiently.


    Complete Beginner Guide

    Common Savings Account Mistakes to AvoidAvoiding common savings account mistakes to avoid isn’t about becoming a banking expert. It’s about paying attention to a few details that can have a lasting impact on your money. Many Americans open a savings account, deposit money, and rarely look at it again. While that approach feels simple, it may leave you earning less interest than you could.
    One of the biggest mistakes is choosing an account based only on convenience. Your local bank may be familiar, but that doesn’t always mean it offers the best return on your savings. Before opening an account, compare interest rates, account fees, minimum balance requirements, and online banking features. A few minutes of research today could help your savings earn more in the future.

    If you’re unsure how interest works, our guide on

    APY vs. Interest Rate Explained

    breaks down the differences in simple terms and shows why APY is often the better number to compare.

    Build a Simple Savings Plan

    A savings account works best when it supports a clear purpose. “Common Savings Account Mistakes to Avoid”Instead of keeping every dollar in one place, consider separating your money into goals such as an emergency fund, vacation savings, home repairs, or holiday spending. This approach makes it easier to stay organized and avoid dipping into money meant for other priorities.

    You can learn more about this strategy in our guide to

    Savings Buckets Explained
    .

    Review Your Account Regularly

    Savings accounts aren’t something you should forget after opening.”Common Savings Account Mistakes to Avoid” Banks may adjust interest rates, introduce new products, or change account terms. Reviewing your account once or twice a year helps you confirm that you’re still getting a competitive return and that you’re not paying unnecessary fees.

    If your current account no longer meets your needs, switching can be easier than many people expect. Our step-by-step guide on

    How to Switch Savings Accounts

    explains the process from start to finish.

    Think Beyond Today’s Interest Rate

    A higher APY is valuable, but it isn’t the only factor to consider. Reliable customer service, easy access to your money, strong security, and helpful digital tools also play an important role. Choosing a well-rounded account can save time and reduce frustration while helping your savings continue to grow.


    Why People Make Savings Account Mistakes

    Most savings account mistakes don’t happen because people make poor financial decisions on purpose. In many cases, they simply don’t realize there are better options available. Once an account is opened, it’s easy to assume everything is working as it should. Months turn into years, and the account is rarely reviewed.

    Banks regularly update interest rates, introduce new products, and change account features. If you never check your account, you could miss opportunities to earn more without taking on additional risk.

    Convenience Often Wins Over Better Returns

    Many people keep their savings at the same bank where they receive their paycheck.”Common Savings Account Mistakes to Avoid” While this is convenient, convenience doesn’t always lead to the best results. Some traditional savings accounts pay much lower interest than competitive high-yield accounts, which means your money may grow more slowly.

    If you’re comparing different banking options, our guide on

    Online Banks vs. Traditional Banks

    explains the advantages and trade-offs of each choice.

    Small Habits Can Have a Big Impact

    A missed monthly deposit or an occasional withdrawal may not seem important. Over time, however, these habits can reduce your account balance and limit the interest you earn. Consistency usually matters more than making one large deposit once in a while.

    Understanding how interest builds can also encourage better saving habits. Our guide to

    Compound Interest Explained for Savers

    shows why regular contributions can make a meaningful difference over the years.

    Inflation Is Easy to Ignore

    Another common mistake is focusing only on your account balance without considering inflation. Even when your savings are growing, rising prices can reduce your purchasing power if your interest rate isn’t keeping pace.

    To understand this better, read our guide on

    How Inflation Affects Your Savings
    .

    Simple Reviews Can Prevent Costly Mistakes

    Checking your savings account once or twice a year doesn’t take much time, but it can help you spot lower interest rates, unnecessary fees, or better alternatives.”Common Savings Account Mistakes to Avoid” A quick review gives you the chance to make small adjustments before they become expensive habits. Staying informed is one of the easiest ways to protect your savings and keep your financial goals moving in the right direction.


    Benefits & Drawbacks

    Learning the common savings account mistakes to avoid can help you make better financial decisions. Even a few small changes can improve your interest earnings and make it easier to reach your savings goals.”Common Savings Account Mistakes to Avoid” At the same time, it’s important to understand that reviewing or changing your savings account may require a little time and research.

    ✅ Benefits of Avoiding These Mistakes

    • Earn more interest by choosing a competitive savings account.
    • Reduce unnecessary monthly fees and avoid preventable charges.
    • Keep your emergency fund growing with better saving habits.
    • Stay informed about changing APYs and new banking options.
    • Feel more confident when making future financial decisions.

    ❌ Drawbacks to Keep in Mind

    • Comparing banks and account features takes a little time.
    • Switching accounts may require updating automatic transfers or direct deposits.
    • Higher APY shouldn’t be the only factor when choosing a savings account.
    • Interest rates can change, so regular account reviews are still important.

    The goal isn’t to find a perfect savings account. It’s to choose one that fits your needs today while continuing to support your financial goals in the future.


    Comparison Table

    Many people don’t notice the difference between good and poor savings habits because the impact builds gradually.”Common Savings Account Mistakes to Avoid” The table below shows how a few simple choices can affect your savings experience over time.

    Savings HabitBetter ChoiceWhy It Matters
    Keeping the same account for yearsReview rates once or twice a yearHelps you avoid missing better APYs.
    Choosing an account based only on convenienceCompare features, fees, and APYCan increase long-term interest earnings.
    Ignoring account feesSelect a low-fee or no-fee accountKeeps more of your money in savings.
    Saving only when money is left overSet up automatic monthly depositsBuilds a consistent saving habit.
    Never checking account performanceMonitor your account regularlyHelps you respond to changing rates and account terms.


    Costs, Risks & Expert Tips

    Most savings accounts are inexpensive to maintain, but choosing the wrong one can still cost you money.”Common Savings Account Mistakes to Avoid” Low interest rates, avoidable fees, and poor saving habits may reduce your earnings without you noticing. Understanding these risks makes it easier to choose an account that supports your financial goals.

    Possible Costs & Risks

    • Monthly maintenance fees can reduce your savings balance.
    • A low APY may cause your money to grow much more slowly than expected.
    • Frequent withdrawals or failing to meet account requirements could result in extra charges at some financial institutions.
    • Keeping all your savings in one account may make it harder to manage different financial goals.

    💡 Expert Tip

    Review your savings account at least once a year. Compare the APY, check for new fees, and make sure your account still fits your needs.”Common Savings Account Mistakes to Avoid” If another bank offers better value without adding unnecessary complexity, switching could help your savings earn more over time.

    ⚠️ Keep in Mind

    A higher interest rate is important, but it shouldn’t be your only consideration. Look at customer service, account security, digital banking tools, FDIC or NCUA insurance, and overall account features before making a decision.


    Common Savings Account Mistakes to Avoid

    Even people who save regularly can make decisions that reduce their earnings over time. The good news is that most of these mistakes are easy to fix.”Common Savings Account Mistakes to Avoid” Paying attention to a few key details can help your savings grow faster while keeping unnecessary costs to a minimum.

    1. Leaving Money in a Low-Interest Account

    Many people opened a savings account years ago and never checked the interest rate again. If your account pays much less than current market rates, your money may not be growing as efficiently as it could. Comparing accounts once or twice a year can help you decide whether it’s worth making a change.

    2. Ignoring Account Fees

    Some savings accounts charge monthly maintenance fees or require a minimum balance. These charges may seem small, but they can slowly reduce your savings. Always read the account terms and make sure you understand any fees before opening or keeping an account.

    3. Not Saving Consistently

    Saving only when extra money is available often leads to slow progress. Setting up automatic transfers after each paycheck makes saving a regular habit and removes the need to remember each month.

    4. Using Savings for Everyday Spending

    A savings account works best when it’s reserved for planned goals or emergencies. Frequent withdrawals for everyday purchases can make it harder to build a financial cushion and may delay long-term goals.

    5. Never Reviewing the Account

    Banks can change interest rates, update account features, or introduce better products.”Common Savings Account Mistakes to Avoid” A quick review every six to twelve months helps confirm that your account still matches your needs and remains competitive.

    Real-Life Example

    Emily opened a savings account shortly after starting her first full-time job. She deposited part of every paycheck but rarely looked at the account again because it seemed to be working fine.

    Several years later, she compared her account with other banks and discovered that her interest rate was much lower than many available options. She also noticed a small monthly maintenance fee that she had overlooked.

    Emily switched to a no-fee savings account with a more competitive APY and scheduled automatic transfers every payday. She didn’t increase the amount she saved each month, but her money began earning more interest simply because she chose an account that better matched her needs.

    The lesson is simple: reviewing your savings account from time to time can uncover opportunities to earn more without changing your overall savings plan.


    Who Should Pay Attention to These Savings Account Mistakes?

    Almost anyone with a savings account can benefit from reviewing these common mistakes. “Common Savings Account Mistakes to Avoid Whether you’re building your first emergency fund or saving for a major life goal, avoiding small errors can help your money work harder over time.

    • First-time savers who want to build good financial habits from the beginning.
    • Students and young professionals looking to grow their savings while avoiding unnecessary bank fees.
    • Families saving for emergencies, vacations, education, or large purchases.
    • Retirees who want to protect their cash savings and earn competitive interest without taking investment risk.
    • Anyone with an older savings account who hasn’t reviewed interest rates or account features in the past year.

    No matter how much money you have saved, reviewing your account regularly and making informed decisions can help you keep more of your earnings. A few simple improvements today may lead to stronger savings growth in the years ahead.


    Frequently Asked Questions

    1. What is the most common savings account mistake?

    One of the most common mistakes is leaving money in a low-interest savings account for years without comparing better options.”Common Savings Account Mistakes to Avoid Even a small difference in APY can increase your interest earnings over time.

    2. How often should I review my savings account?

    A good rule is to review your account at least once or twice a year. Check the interest rate, look for new fees, and compare your account with other available options to make sure it still meets your needs.

    3. Is it worth switching to a different savings account?

    It can be. If another account offers a higher APY, lower fees, or features that better match your goals, switching may help your savings grow faster. Before making a change, compare the complete account terms instead of focusing only on the advertised interest rate.

    4. Can bank fees reduce my savings?

    Yes. Monthly maintenance fees, minimum balance charges, and other account fees can slowly reduce your savings balance. Choosing a low-fee or no-fee account helps you keep more of the money you earn.

    5. Should I have more than one savings account?

    For many people, the answer is yes. Having separate accounts for goals such as an emergency fund, travel, or home repairs can make budgeting easier and reduce the temptation to spend money meant for another purpose.

    6. Are online savings accounts safe?

    Many online banks are just as safe as traditional banks when they are insured by the FDIC, while credit unions may be insured by the NCUA. Before opening an account, confirm the institution’s insurance coverage and review its security features.

    7.”Common Savings Account Mistakes to Avoid” Can avoiding these mistakes really make a difference?

    Absolutely. Small improvements, such as earning a better interest rate, avoiding unnecessary fees, and saving consistently, can have a meaningful impact over the long term. Regularly reviewing your account helps ensure your savings continue to support your financial goals.


    Final Verdict

    Avoiding common savings account mistakes doesn’t require complicated financial knowledge. In most cases, a few simple habits can make a noticeable difference over time. Reviewing your account regularly, comparing interest rates, watching for unnecessary fees, and saving consistently can help your money grow more efficiently.

    The best savings account isn’t always the one you’ve had the longest. Banking products change, interest rates move, and your financial goals evolve.”Common Savings Account Mistakes to Avoid” Taking a little time each year to review your options can help ensure your savings continue working for you instead of sitting in an account that no longer meets your needs.

    If you’re looking for more ways to maximize your savings, don’t miss our complete guide:
    High-Yield Savings Accounts USA: Complete Beginner Guide.
    It explains how high-yield savings accounts work, what features to compare, and how to choose the right account for your financial goals.

    Stay Ahead of Your Money

    Want practical money tips, banking guides, and investing insights designed for Americans? Join our community and get new articles that help you make smarter financial decisions.


    Visit FinanceInvestment.site


    References

    The information in this guide is based on official resources and trusted financial organizations. These sources provide up-to-date information on savings accounts, deposit insurance, banking regulations, and consumer financial education.


    Disclaimer

    This article is provided for educational and informational purposes only. It should not be considered financial, investment, tax, or legal advice. Every person’s financial situation is different, and the right savings account depends on your individual goals, income, risk tolerance, and banking needs.

    Interest rates, account features, fees, and promotional offers may change over time. Before opening, closing, or switching a savings account, review the latest terms and conditions provided by the financial institution.

    While we make every effort to keep our content accurate and up to date, we cannot guarantee that all information will remain current after publication. If you need advice tailored to your personal circumstances, consider speaking with a qualified financial professional.