How FDIC Insurance Works When You Have Accounts at Different Banks
Updated: November 6, 2026
Reading time: 10 min
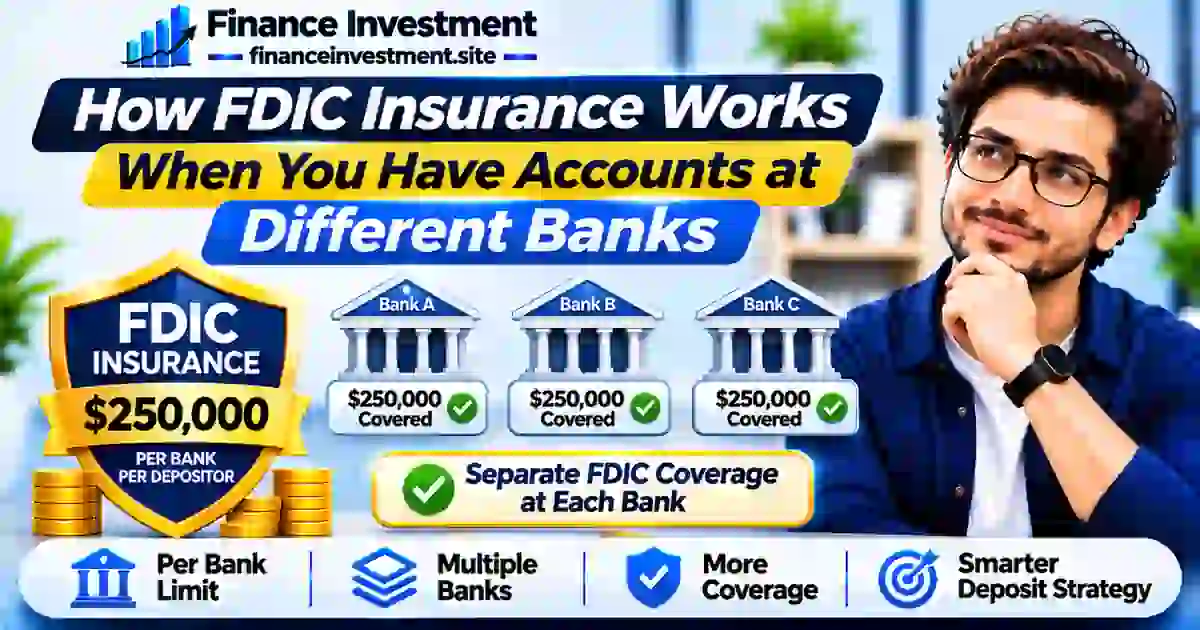
Does FDIC Insurance Cover Accounts at Different Banks Separately?
Keeping money at more than one bank can help you organize checking, savings, and emergency funds. But if you have deposits at several financial institutions, an important question is whether each bank gives your money a separate layer of FDIC protection.
FDIC insurance at different banks generally follows this rule: eligible deposits are insured up to $250,000 per depositor, per FDIC-insured bank, per ownership category. Deposits at separately insured banks may qualify for separate coverage. However, accounts at different branches of the same insured bank generally share the same coverage limit, and different brand names do not necessarily mean different insured banks.
Your coverage can also depend on how an account is owned, so simply counting your accounts may not tell you how much protection you have. This guide walks through the rules, examples, and common mistakes to help you review your balances. For the fundamentals, start with our FDIC and NCUA insurance guide.
What You’ll Learn
- How the $250,000 FDIC limit applies at separately insured banks
- Why different branches of one bank generally share coverage
- How account ownership categories can affect deposit insurance
- How to review your deposits and estimate your coverage
- Mistakes to avoid when keeping money across multiple banks
Quick Answer: How FDIC Insurance Works at Different Banks
FDIC insurance generally protects eligible deposits up to $250,000 per depositor, per FDIC-insured bank, per ownership category. Deposits held at two separately FDIC-insured banks may qualify for separate coverage. However, accounts at different branches of the same insured bank generally share the same limit within an ownership category. Coverage also depends on how the deposits are owned and whether they meet FDIC requirements.
Key Takeaways
- Separate insured banks: Eligible deposits may receive separate coverage at each separately FDIC-insured bank.
- Different branches: Branch locations of the same insured bank generally do not increase your coverage.
- Ownership categories matter: Individual, joint, and other qualifying ownership categories follow different coverage rules.
- Balances are combined: Deposits in the same ownership category at one insured bank are generally added together when calculating coverage.
- Review your situation: Use the FDIC’s EDIE deposit insurance estimator to help evaluate your coverage.
FDIC Insurance at a Glance
FDIC insurance protects eligible deposits if an FDIC-insured bank fails. The standard coverage limit is $250,000 per depositor, per insured bank, per ownership category. Deposits at separately insured banks may qualify for separate coverage, while eligible deposits in the same ownership category at one bank are generally combined. Source: FDIC Deposit Insurance at a Glance
| Quick Fact | What It Means |
|---|---|
| Separate insured banks | Eligible deposits may receive separate coverage at each separately FDIC-insured bank. |
| Same bank, multiple branches | Branches of the same insured bank generally share coverage limits. |
| Same ownership category | Eligible deposits are generally added together at the same insured bank. |
| Covered deposit products | Checking, savings, money market deposit accounts, and CDs. |
| Not FDIC-insured | Stocks, bonds, mutual funds, annuities, and Treasury securities. Treasury securities are backed by the U.S. government, but are not FDIC-insured deposits. |
To review your specific situation, use the FDIC’s EDIE deposit insurance estimator and verify that your bank is FDIC-insured. The estimator can help assess coverage; account ownership and eligibility requirements still matter.
FDIC Insurance Explained for Beginners
The Federal Deposit Insurance Corporation (FDIC) is a U.S. government agency that protects eligible bank deposits if an FDIC-insured bank fails. You do not purchase this protection separately. Eligible deposits are automatically covered when held at an FDIC-insured bank, subject to the agency’s coverage rules.
The standard limit is $250,000 per depositor, per insured bank, per ownership category. Coverage depends on the depositor, the actual insured bank, and how the money is owned—not simply the number of accounts you open.
What Counts as an FDIC-Insured Deposit?
Common insured deposit products include checking accounts, savings accounts, money market deposit accounts, and certificates of deposit (CDs). Stocks, mutual funds, annuities, and U.S. Treasury securities are not FDIC-insured deposits, even when purchased through a bank. Treasury securities have separate U.S. government backing.
Why Different Banks Can Matter
Suppose you have $180,000 in eligible savings at Bank A and $160,000 at Bank B. If both are separately FDIC-insured banks and the deposits qualify in the same ownership category, each balance is below the standard $250,000 limit at its respective bank. But if both accounts are held by the same insured bank—even under different brand names—the deposits may need to be combined for coverage purposes.
Beginner tip: Verify the actual insured institution—not just the bank’s app, website, or brand name—using the FDIC’s BankFind tool. Then review your deposits and ownership categories with the FDIC EDIE estimator.
For official coverage details, visit the FDIC deposit insurance resource.
How FDIC Coverage Works Across Different Banks
FDIC insurance depends on three main factors: who owns the deposits, which insured bank holds them, and the ownership category. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Eligible deposits in the same category at one bank are combined—even when they are held in checking, savings, and CDs. See the FDIC’s coverage rules.
1. Separate FDIC-Insured Banks
Suppose you have $180,000 in eligible deposits at Bank A and $160,000 at Bank B. If both are separately FDIC-insured banks and the deposits qualify in the same ownership category, each balance is below the standard $250,000 limit at its respective bank. The banks may even share a parent company; separately insured institutions are evaluated separately.
2. Different Branches or Brand Names
Opening accounts at two branches of the same insured bank does not create two insurance limits. An online bank brand or partner app may also use the same underlying insured institution as another account you hold. Verify the actual bank holding the deposits before assuming coverage is separate.
3. Different Ownership Categories
Qualifying ownership categories—such as single and joint accounts—may receive separate coverage at the same bank. However, accounts must meet FDIC requirements. Opening another account or choosing a different deposit product does not automatically create a new ownership category.
Remember: Review deposits by insured bank and ownership category—not by account count. Use the FDIC EDIE estimator to help evaluate your coverage.
Benefits and Drawbacks of Using Different Banks
Keeping eligible deposits at more than one separately FDIC-insured bank can help you manage coverage limits and organize your money. However, additional accounts also bring more responsibilities, and opening another account does not automatically increase your insurance protection.
Benefits
- Separate coverage calculations: Eligible deposits may receive separate coverage at each separately FDIC-insured bank, subject to ownership-category rules.
- Organized finances: Different accounts can help you separate emergency savings, bills, and short-term goals.
- More account choices: You can compare banks for features, access, and account terms that fit your needs.
Drawbacks
- More account management: Multiple logins, statements, and transfer schedules can be harder to track.
- Account requirements: Some banks may have monthly fees, minimum balances, or activity requirements; check each account’s terms.
- Coverage confusion: Different brands may use the same insured bank, so opening another account may not increase FDIC protection.
The practical approach is to balance convenience, account features, and coverage needs. Before moving money, verify each bank’s FDIC status, identify the institution holding your deposits, and review eligible balances by ownership category. Read the FDIC deposit insurance guidance to understand how coverage is calculated.
FDIC Insurance at Different Banks: Comparison
The key question is whether your deposits are held at separate FDIC-insured banks or at the same bank. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Eligible deposits in the same ownership category at one bank are combined when calculating coverage.
| Banking Setup | How Coverage Works | What to Check |
|---|---|---|
| Two separately chartered FDIC-insured banks | Coverage is calculated separately at each insured bank for each ownership category. | Confirm both institutions are FDIC-insured. |
| Two branches of one bank | Eligible deposits in the same ownership category are combined across branches. | Check the insured bank’s legal identity. |
| Different brands, same insured bank | Deposits generally share the same bank-level limit within the same ownership category. | Identify the institution holding each deposit. |
| Different ownership categories at one bank | Separate coverage may apply when each category’s requirements are satisfied. | Review ownership, account title, and category eligibility. |
Example: Suppose you have $180,000 in eligible deposits at Bank A and $160,000 at Bank B. If both are separately chartered FDIC-insured banks and the deposits fall within the same ownership category, each balance is below the standard $250,000 limit. If both balances are instead held at the same insured bank in that category, the combined $340,000 may exceed the standard limit.
Use the FDIC’s BankFind tool to verify an institution and EDIE to estimate your coverage.
Costs, Risks & Expert Tips for Managing FDIC Coverage
Using different banks may help you manage eligible deposits, but multiple accounts can also create extra work. Before moving money, review account costs and confirm how your deposits are insured.
Costs and Risks to Watch
- Account fees: Some accounts charge monthly fees or require minimum balances or qualifying activity. Check each account’s terms.
- Coverage mistakes: Different brands may use the same insured bank, so eligible deposits could be combined.
- More administration: Multiple accounts mean more statements, logins, transfers, and balances to monitor.
Expert Tips
- Verify each institution using FDIC BankFind.
- Track eligible deposits in each ownership category at each bank, including accrued interest when estimating coverage.
- Use the FDIC EDIE estimator to review your coverage. Enter account ownership and deposit details carefully; the estimate depends on the information provided.
FDIC insurance protects eligible deposits if an insured bank fails. It does not cover investment losses, theft, or fraud; those issues may involve separate legal protections and bank procedures. Review the official FDIC deposit insurance guidance before making coverage decisions.
Common FDIC Insurance Mistakes and Real-Life Examples
Opening accounts at different banks can help you manage eligible deposits, but misunderstandings about bank identity and account ownership may leave part of your money uninsured.
Mistakes to Avoid
- Assuming every account gets $250,000: Eligible checking, savings, and CD deposits in the same ownership category at one insured bank are generally combined.
- Confusing brands with banks: Different brands may use the same insured institution, meaning deposits can share one coverage limit.
- Assuming account type creates separate coverage: Opening checking, savings, or CD accounts does not by itself create different ownership categories.
Real-Life Examples
Example 1: You have $180,000 in checking and $100,000 in savings at the same insured bank. If both accounts are eligible and individually owned in the same ownership category, the $280,000 combined balance exceeds the standard $250,000 limit. The amount above the limit may be uninsured.
Example 2: You hold $180,000 at Bank A and $160,000 at Bank B. If both are separately chartered FDIC-insured banks and the deposits qualify in the same ownership category, each balance is below the standard $250,000 limit at its respective bank.
The lesson is simple: verify the insured institution, combine eligible deposits by ownership category, and review your balances regularly. Use the FDIC EDIE estimator to help review your coverage.
Who Should Review Their FDIC Coverage?
Reviewing your FDIC coverage can be especially useful when your savings grow, your account ownership changes, or you receive a large deposit. Consider checking your coverage if you:
- Have more than $250,000 in eligible deposits at one insured bank and want to understand how your ownership category affects coverage.
- Hold accounts under different brands that may use the same insured institution.
- Recently received an inheritance, property-sale proceeds, or another large deposit.
- Have joint, trust, retirement, or business accounts and need to confirm the applicable ownership-category requirements.
Start by identifying the insured bank holding each deposit and reviewing eligible balances by ownership category. The FDIC’s EDIE estimator can help estimate coverage for supported account types based on the details you enter. For more background, read our FDIC and NCUA insurance guide.
Frequently Asked Questions About FDIC Insurance at Different Banks
1. Does FDIC insurance cover accounts at different banks separately?
Generally, yes. Eligible deposits are insured separately at each separately chartered FDIC-insured bank, subject to the $250,000 limit per depositor, per bank, per ownership category.
2. Is FDIC insurance limited to $250,000 per account?
No. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Eligible accounts in the same category at one bank are combined.
3. Do different branches of the same bank have separate FDIC coverage?
No. Branches of the same insured bank share the same coverage calculation for deposits held in the same ownership category.
4. Do different bank brands always mean separate FDIC coverage?
No. Different brands may use the same insured institution. Verify the actual bank holding your deposits before assuming separate coverage.
5. Are checking, savings, and CD accounts insured separately?
Not automatically. Eligible checking, savings, and CD deposits in the same ownership category at the same insured bank are generally combined toward one $250,000 limit.
6. Can I receive more than $250,000 in FDIC coverage at one bank?
Yes, potentially. Different ownership categories may qualify for separate coverage when FDIC requirements are met. Account type alone does not create a separate category.
7. Are money market accounts and CDs covered by FDIC insurance?
Money market deposit accounts and certificates of deposit at FDIC-insured banks are covered deposit products. Money market mutual funds are investments and are not FDIC-insured.
8. How can I check my FDIC insurance coverage?
Verify your bank through FDIC BankFind and use the EDIE estimator to review coverage based on your account details.
For official details, review the FDIC Deposit Insurance FAQs. Coverage depends on eligible deposits, the insured bank, and account ownership requirements.
Final Verdict: How to Manage FDIC Insurance at Different Banks
FDIC insurance at different banks can help protect eligible deposits when your money is held at separately insured institutions. The standard limit is $250,000 per depositor, per insured bank, per ownership category—not per account. Eligible deposits in the same ownership category at one bank are generally combined.
Before moving money, verify each bank, review your eligible balances, and confirm how your accounts are owned. The FDIC EDIE estimator can help you estimate coverage based on the details you enter.
Bottom line: Focus on the insured bank, ownership category, and combined eligible deposits—not simply the number of accounts. For a broader explanation, read our FDIC and NCUA Insurance Explained guide.
Make Smarter Decisions About Your Bank Deposits
Understanding FDIC insurance at different banks can help you make informed decisions about where to keep your savings. Review your balances, verify your bank’s insurance status, and understand how account ownership affects your coverage.
Have a question about FDIC insurance or personal finance? Get in touch with FinanceInvestment.
Explore more: FDIC and NCUA Insurance Explained | High-Yield Savings Accounts USA
FinanceInvestment provides educational information for general financial awareness. Verify your specific deposit insurance coverage with the FDIC or your insured bank before making financial decisions.