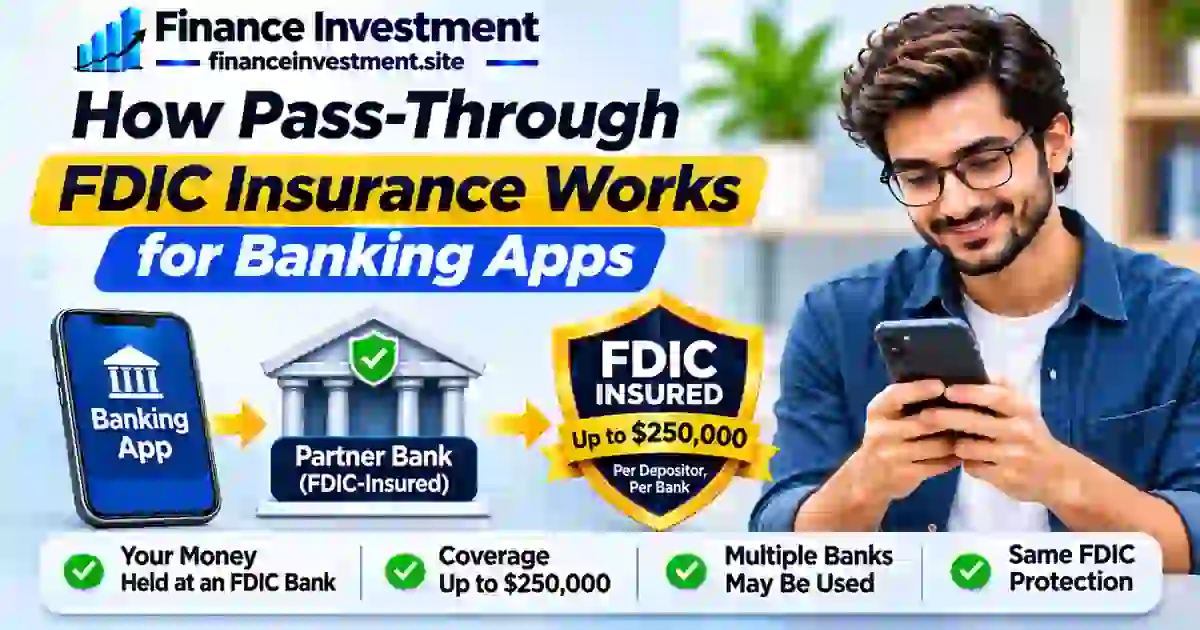
How Pass-Through FDIC Insurance Works for Banking Apps
 Introduction: Where Does Your Banking App Keep Your Money?
Understanding how pass-through FDIC insurance works matters when your savings sit inside a banking app rather than an account opened directly with a bank. The app may handle your transactions, but another institution could actually hold the deposit.
Some fintech companies place customer funds at FDIC-insured partner banks through custodial accounts. Eligible deposits may qualify for pass-through coverage when ownership and recordkeeping requirements are satisfied. However, using an insured bank does not automatically make every app balance insured.
We’ll explain how these arrangements operate, what can interrupt access to your money and how to check the details before depositing substantial savings. For the wider coverage rules, visit our FDIC and NCUA insurance guide.
What You’ll Learn
- How banking apps and partner banks handle deposits.
- Which conditions determine pass-through coverage.
- Why ownership records and intermediaries matter.
- How to investigate coverage before moving money.
Quick Answer: How Does Pass-Through FDIC Insurance Work?
Quick Answer: Pass-through FDIC insurance may cover eligible deposits held at an FDIC-insured bank through a banking app or intermediary. The arrangement must satisfy applicable ownership, account-disclosure and recordkeeping requirements. When it qualifies, coverage is based on the actual deposit owner, insured bank and ownership category—not the app’s branding.
6 Key Takeaways
- Insured bank: Eligible funds must be deposited at an FDIC-insured institution.
- Ownership records: Required records must establish the customers’ interests in the deposits.
- Insurance limit: The standard limit is $250,000 per depositor, per insured bank, per ownership category.
- Combined balances: Deposits in the same ownership category at one insured bank generally count together.
- Failure protection: FDIC insurance covers insured bank failures, not the standalone failure of a fintech provider.
- Product distinction: Stocks, cryptocurrency and other nondeposit products do not receive FDIC deposit insurance.
Bottom Line: Don’t rely on an app’s FDIC-related marketing alone. Identify the partner bank, review how your ownership is recorded and check your combined deposits at that institution before assuming your balance is fully covered.
Table of Contents
Pass-Through FDIC Insurance at a Glance
A banking app may display your balance while an insured bank holds the actual deposit. These quick facts show which details matter when evaluating pass-through protection.
Quick Coverage Summary
| Coverage Check | Why It Matters |
|---|---|
| Insured bank | The deposit must be held at an FDIC-insured institution. |
| Ownership records | Applicable account-disclosure and beneficial ownership requirements must be met. |
| Other deposits | Eligible balances at the same bank in the same ownership category are generally combined. |
| Provider failure | A fintech company’s failure alone does not trigger FDIC deposit insurance. |
Quick Take: An insured partner bank is necessary, but it does not guarantee that every app balance qualifies for FDIC coverage.
Beginner Guide: Banking Apps, Partner Banks and Custodial Accounts
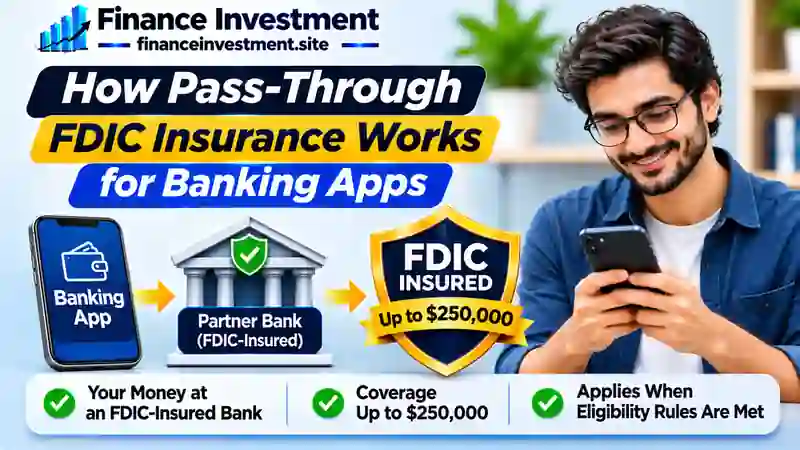
You open a banking app, transfer $2,000 and see the money appear on your screen. Simple enough. But the company displaying your balance may not be the institution holding your deposit.
The App and the Bank Play Different Roles
A fintech company may manage the app, customer service and payment features. An FDIC-insured partner bank may hold the deposited money. Some arrangements also involve a separate technology provider responsible for transaction processing or customer records.
What Is a Custodial or FBO Account?
FBO means “For Benefit Of.” In a pooled custodial arrangement, an intermediary holds funds on behalf of multiple customers, while underlying records identify each customer’s ownership interest.
For example, a single bank account might hold money belonging to 500 app users. The records must establish each person’s share and satisfy applicable deposit insurance requirements. Simply labeling an account “FBO” does not guarantee pass-through coverage.
Not Every Banking App Uses the Same Setup
Some apps facilitate accounts opened directly in customers’ names at partner banks. Others use pooled custodial structures. The difference matters because ownership documentation, access arrangements and insurance eligibility can vary. Before depositing significant savings, check which structure your provider actually uses.
How Pass-Through FDIC Insurance Actually Works
When money moves through a banking app, several companies may handle the transaction. Pass-through insurance depends on the legal deposit arrangement and whether the required records establish who owns the funds.
Step 1: Money Is Deposited at an Insured Bank
Customer funds must actually be held as eligible deposits at an FDIC-insured bank. A balance displayed in an app does not, by itself, establish that the money has reached an insured deposit account.
Step 2: The Bank’s Records Disclose the Relationship
The bank’s deposit account records generally must show that the named account holder acts for others, such as an agent or custodian. This disclosure helps distinguish customer-owned funds from money belonging to the intermediary.
Step 3: Ownership Interests Must Be Verifiable
Records maintained in accordance with FDIC requirements must establish the actual owners and their respective interests. Where several intermediaries are involved, the records must support tracing those interests through the arrangement. The customers must also genuinely own the deposits under applicable law.
Step 4: Coverage Is Calculated if the Bank Fails
If the insured bank fails, the FDIC determines coverage using the applicable ownership categories and limits. Qualifying pass-through deposits are generally added to the same customer’s other deposits at that bank within the same ownership category.
Important: A fintech or intermediary failure does not itself trigger FDIC insurance while the partner bank remains open. Incomplete or conflicting records can also complicate ownership verification and delay access to funds.
Benefits and Drawbacks of Pass-Through FDIC Coverage
A banking app can make everyday money management easier without requiring you to open an account directly through a bank’s website. Still, the way customer deposits are held deserves attention.
Benefits
- Eligible deposit coverage: Qualifying customer funds may receive FDIC protection through the insured bank.
- Convenient features: Apps may simplify payments, transfers and balance monitoring.
- Flexible access: Customers can explore bank deposit services through different digital platforms.
Drawbacks
- Additional intermediaries: More companies may handle transactions, records or customer support.
- Access delays: Recordkeeping disputes or service interruptions can make funds temporarily unavailable.
- Different failure risks: FDIC deposit insurance does not cover the standalone failure of a fintech company.
Practical Take: Choose an app for its useful features, but evaluate deposit protection separately from convenience and marketing claims.
Direct Bank Deposits vs. Banking Apps vs. Nondeposit Balances
A familiar app interface does not tell you how the money behind it is held. Some apps facilitate direct bank accounts; others use custodial arrangements or offer products that are not bank deposits.
| Feature | Direct Bank Deposit | Custodial App Deposit | Nondeposit Product |
|---|---|---|---|
| Account structure | Customer holds an account at the bank | Intermediary holds funds for customers | Investment or other nondeposit arrangement |
| FDIC insurance | Eligible deposits covered within limits | Possible when pass-through requirements are satisfied | Not covered by FDIC deposit insurance |
| Customer records | Bank generally maintains ownership records | Bank and intermediaries may maintain required records | Depends on the product |
| What to verify | Bank identity and coverage category | Partner bank, ownership and recordkeeping | Product terms and applicable risks |
Quick Take: Check whether your balance is a direct bank deposit, a qualifying custodial deposit or a nondeposit product. The distinction determines which protections may apply.
Costs, Recordkeeping Risks and Expert Tips
A banking app can offer convenient features and low advertised fees. Yet the real cost of using it may include service charges, transfer restrictions and unexpected interruptions to your access to money.
Check Fees Beyond the Monthly Charge
Depending on the provider, instant transfers, out-of-network ATM withdrawals or replacement cards may carry fees. Review the current fee schedule, withdrawal limits and transfer timelines before relying on the account for everyday expenses.
Understand Recordkeeping and Access Risks
Your app balance may depend on records maintained across several companies. Missing transactions, inconsistent ledgers or interrupted data sharing can make it harder to reconcile balances and establish ownership.
An intermediary’s financial or operational failure may also delay withdrawals even if the partner bank remains open. FDIC insurance does not guarantee uninterrupted access during such disruptions.
Expert Tip: Verify the Details Before Depositing
Use FDIC BankFind to verify the partner bank’s insured status. Then read the app’s deposit disclosures, identify who maintains customer records and keep copies of statements.
Remember: Finding an insured bank in BankFind does not independently confirm that your particular app balance qualifies for pass-through coverage.
Common Mistakes and a $300,000 Practical Example
Using two financial apps does not necessarily provide two separate FDIC insurance limits. The insured bank, legal ownership and deposit category matter more than the number of accounts shown on your phone.
Four Mistakes to Avoid
- Confusing fintech with bank insurance: An app’s FDIC-related claim does not make the fintech itself an insured bank.
- Missing shared partner banks: Different apps may deposit money at the same institution.
- Counting separate app limits: Deposits at one bank in the same ownership category are generally aggregated.
- Ignoring ownership records: An FBO label alone does not establish pass-through eligibility.
Example: $300,000 at One Insured Bank
Maya has $180,000 in an individual savings account at Bank A and $120,000 through an app that places her funds at Bank A.
Assume the app deposit qualifies for pass-through coverage, both balances are in the same ownership category and Maya has no other deposits at Bank A.
$180,000 + $120,000 = $300,000
Result: If Bank A fails, the standard $250,000 limit would cover $250,000, leaving $50,000 uninsured. Separate apps would not increase that limit.
Who Should Use Banking Apps With Pass-Through Coverage?
A banking app may work well when its features match your daily needs and you understand where your deposits are held. For essential savings, account transparency deserves equal attention.
Banking Apps May Suit
- Digital-first customers who frequently transfer or manage money online.
- People who can identify the partner bank and review deposit disclosures.
- Users who keep an alternative account available for unexpected expenses.
A Direct Bank Account May Suit
- Savers who prefer dealing directly with the institution holding their deposits.
- Households seeking a simpler arrangement for essential emergency funds.
- Customers unable to verify an app’s partner bank or deposit structure.
Bottom Line: Choose based on transparency, accessibility and your savings priorities—not promotional rates alone.
Frequently Asked Questions About Pass-Through FDIC Insurance
1. Are all banking apps FDIC insured?
No. A fintech app is not automatically an insured bank. Eligible deposits at an FDIC-insured partner bank may qualify for coverage.
2. Does an FBO account guarantee FDIC coverage?
No. Pass-through coverage requires qualifying deposits, genuine ownership interests and compliance with applicable disclosure and recordkeeping rules.
3. What is the standard FDIC insurance limit?
Generally, $250,000 per depositor, per insured bank, per ownership category, including applicable same-bank deposits.
4. Can two banking apps share one insurance limit?
Yes. Eligible deposits at the same insured bank in the same ownership category are generally added together.
5. What happens if the fintech company fails?
Fintech failure alone does not trigger FDIC deposit insurance. Customers may experience delays accessing their funds.
6. Are funds in transit automatically insured?
No. Insurance depends on where the funds are actually held and whether they qualify as deposits at an insured bank.
7. How can I verify a partner bank?
Use FDIC BankFind to verify the bank’s insured status. This alone does not confirm coverage for your app balance.
8. Does FDIC insurance cover investment balances?
No. Stocks, mutual funds and other nondeposit investments are not covered by FDIC deposit insurance.
Final Verdict: Know What Protects Your Banking App Balance
Pass-through FDIC insurance can protect eligible deposits if the insured bank fails, provided applicable ownership and recordkeeping requirements are satisfied. A fintech’s insurance claim alone cannot establish coverage.
Before depositing substantial savings, identify the partner bank, review account disclosures and check whether other deposits at that bank affect your insurance limit.
For more guidance, explore our FDIC and NCUA Insurance Explained guide.
Have a Money Question? Keep Exploring.
Knowing how your money is held can help you make more informed banking decisions. Explore our guides on deposit protection, or send us a question about the topics covered here.
📩 Get in Touch With FinanceInvestment
Disclaimer: This content is for general educational purposes, not personalized financial or legal advice. FDIC insurance depends on the actual deposit arrangement, applicable coverage rules and account records. Confirm important details with the bank and the FDIC.