From Your Deposit to the Maturity Date
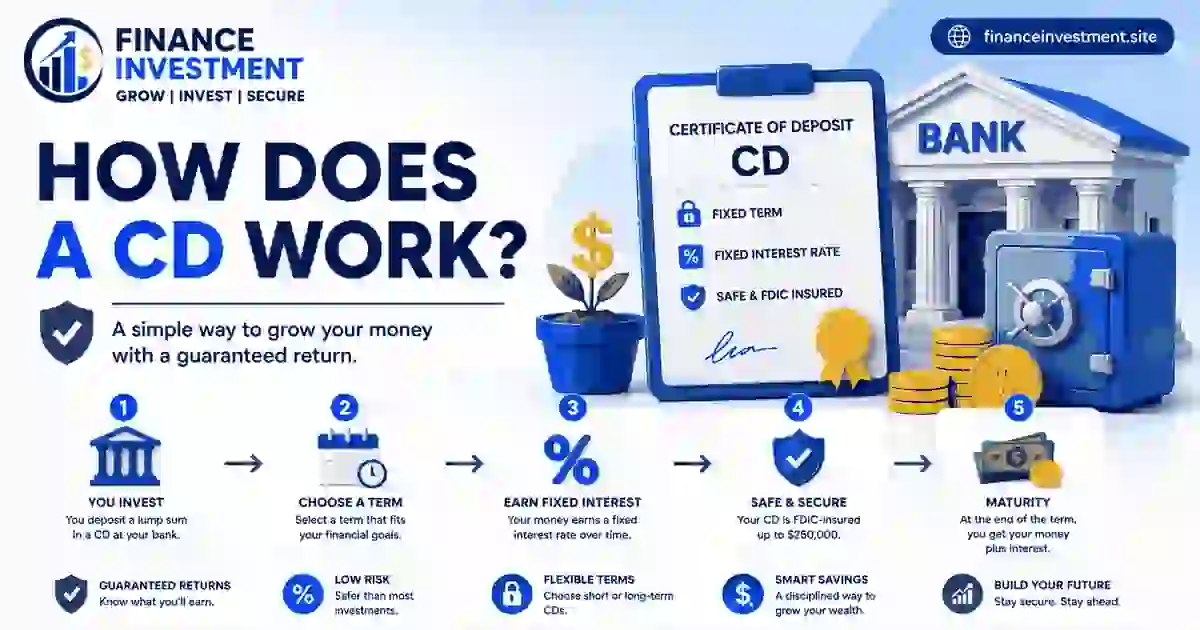 How Does a CD Work when you put actual dollars into one? Picture Lisa receiving a $7,500 work bonus in 2026. She does not expect to spend it for 18 months, so she compares CD terms, checks the APY and withdrawal penalty, and places the money into an 18-month account. Her bank holds the deposit for that agreed term while interest builds under the account’s rules.
The important part is the trade-off. Lisa gets a defined term and interest rate, but she gives up some access to her cash. Taking the money out before maturity may cost her a penalty.
For the bigger picture, see our
complete CD guide for 2026
.
What You’ll Learn
You’ll see how a CD is opened, how interest accumulates, what happens at maturity, why early withdrawals can cost money, and how to decide whether a fixed-term deposit fits your plans.
Quick Answer: How a CD Works
How Does a CD Work? You deposit money for a fixed period, and the bank pays interest according to the account terms. When the term ends, you reach the maturity date and can usually withdraw, move, or renew the money.
- You choose the deposit amount and CD term.
- The APY shows the annualized earning rate.
- Your money generally stays in the account until maturity.
- Early withdrawal may reduce your earnings through a penalty.
- The maturity date tells you when the original term ends.
- Renewal terms can differ from your original CD.
Bottom line:
A CD works best when the term matches the date you expect to need the money.
Table of Contents
At a Glance: How CDs Work
How Does a CD Work in everyday terms? You place money into a time-based deposit, choose a term, and earn interest under the account’s rules. Your maturity date determines when the original term ends.
Quick Fact
A CD has a fixed term and maturity date.
Best For
Money you can leave untouched for a planned period.
Key Numbers
Compare APY, term, deposit, penalty, and maturity date.
| CD Part | What It Means |
|---|---|
| Deposit | Money placed into the account |
| Term | Agreed period for keeping the money deposited |
| Maturity | Date when the CD’s original term ends |
Complete Beginner Guide to Understanding a CD
 How Does a CD Work when you open one for the first time? The basic idea is straightforward. You choose how much money to deposit, select a term, and agree to leave the funds in the account under the bank’s stated conditions. In return, the bank pays interest according to the CD agreement.
Consider Aaron, who has $12,000 set aside for a new car. He expects to buy it in about a year but does not need the money today. Rather than placing the entire amount somewhere he might spend it, he compares one-year CDs and checks the APY, minimum deposit, and early withdrawal penalty. He chooses an account whose maturity date is close to his expected purchase date.
Four Parts You Need to Understand
- Deposit: The amount you put into the CD. Some institutions set minimum opening amounts.
- Term: The agreed period, such as six months, one year, or several years.
- APY: The annualized yield used to compare what the account can earn under its stated terms.
- Maturity: The date when the original CD term ends and your next choices become available.
Before choosing a CD, it helps to understand
APY versus the stated interest rate
.
Also compare your CD with
high-yield savings options
if you may need easier access to the money.
One useful rule:
Never put emergency cash into a CD simply because its APY looks attractive. The term should fit your actual plans.
How a CD Works Step by Step
How Does a CD Work from the day you open it to the day you get your money back? Think of the process as a simple agreement with a clear starting point, a fixed period, and an ending date. For example, Nina has $9,000 from a completed home project. She expects to leave it untouched for 12 months.
Nina compares the APY, term, minimum deposit, and early withdrawal rules before choosing the account.
She deposits the $9,000 and the CD begins according to the institution’s stated terms.
Interest accrues according to the account agreement. Taking the money out early may trigger a penalty.
At the maturity date, Nina can review her options, which may include withdrawing the funds or renewing the CD.
If you are comparing different CD choices, review our
complete CD guide for 2026
.
It is also worth checking how
compound interest works
when comparing potential earnings.
Benefits & Drawbacks of Using a CD
How Does a CD Work financially? You trade some access to your cash for a defined term and interest arrangement. That can be helpful for money with a clear purpose, but it can become frustrating if your plans change before the maturity date.
✓ Pros
- Predictable earnings: The account terms tell you how the money is expected to earn interest.
- Clear deadline: A maturity date can line up neatly with a planned expense.
- Less market uncertainty: A traditional CD does not depend on daily stock-market movements.
- Useful for disciplined saving: Limited access can make it harder to spend money set aside for a specific goal.
− Cons
- Less flexibility: Accessing the money before maturity may be costly.
- Early withdrawal penalty: The fee can reduce some or all of your expected interest.
- Rates may move: After maturity, a replacement CD could offer a different rate.
- Inflation can matter: Rising prices may reduce the purchasing power of your return.
CD vs. Other Ways to Hold Your Money
Understanding How Does a CD Work also means seeing where it fits beside other cash options. A CD may offer a defined term, while savings accounts usually give you easier access. The right choice depends on when you expect to use the money.
| Option | Access | Rate Type | Good For |
|---|---|---|---|
| CD | Limited before maturity | Usually fixed | Planned future expenses |
| High-yield savings | Generally easier | Usually variable | Accessible savings |
| Money market account | Generally flexible | Usually variable | Cash reserves |
| Treasury bill | Can be sold before maturity | Market-based yield | Short-term government debt |
Smart comparison:
Don’t pick an account by rate alone. Check access, term, penalties, and the date you expect to need the money.
Costs, Risks & Expert Tips Before Opening a CD
How Does a CD Work financially? The rate is only one part of the deal. Before depositing your money, check the minimum opening amount, early withdrawal penalty, interest payment schedule, maturity date, and automatic renewal rules. A slightly lower rate with better terms may be more useful than a higher rate that does not fit your plans.
💡 Expert Tip
Match the CD term to a date you can realistically plan around. If you expect a tuition payment in 14 months, don’t automatically choose a two-year CD just because its advertised APY is higher. Keep your emergency fund separate.
⚠ Warning
Don’t assume every CD has identical withdrawal or renewal rules. Read the account agreement and confirm whether the institution is FDIC-insured or, for an eligible credit union, federally insured by the NCUA. Large balances also deserve a careful look at applicable coverage limits.
Common CD Mistakes + A Real-Life Example
How Does a CD Work is easy to explain, but choosing one without checking the details can create trouble. Common mistakes include using emergency savings, picking a term that is too long, overlooking the early withdrawal penalty, and forgetting to review the account before maturity.
Real-Life Example: A Family Emergency Changes the Plan
Mark puts $25,000 into a 24-month CD after receiving a bonus. Six months later, his basement floods and he needs $14,000 for repairs. He has no other cash reserve large enough to cover the bill. Closing the CD early means paying the penalty and giving up part of the interest he expected to earn.
Before You Open One
- Keep emergency money somewhere accessible.
- Choose a term that matches your expected cash need.
- Read the early withdrawal penalty carefully.
- Check the maturity and renewal dates.
- Compare the full terms, not just the advertised APY.
Who Should Choose a CD?
How Does a CD Work is especially relevant when you have money with a clear purpose and a date when you expect to use it. A CD can make sense if you are comfortable leaving the funds untouched and want a defined interest arrangement.
✓ Premium Best Fit
- Goal-based savers: You have a known expense months or years away.
- Cash planners: You already have accessible money for unexpected bills.
- Rate-conscious savers: You compare APY, penalties, deposits, and terms.
- People seeking stability: You prefer a deposit account for this portion of your cash rather than market-based risk.
Frequently Asked Questions About How CDs Work
How Does a CD Work for everyday savings? These answers cover the questions beginners often have before choosing a fixed-term deposit.
1. How does a CD work?
You deposit money for a stated term and earn interest according to the account agreement. At maturity, you can generally access or renew the funds.
2. How long does a CD last?
CD terms vary. Banks and credit unions may offer terms ranging from a few months to several years.
3. Can I take money out before maturity?
Many traditional CDs allow early withdrawal, but the account may charge a penalty that reduces your earnings.
4. What is the maturity date?
It is the date when the original CD term ends. The institution then follows the withdrawal or renewal rules stated in the account agreement.
5. Does a CD earn interest every month?
Interest may accrue daily or according to the institution’s method, while payment timing depends on the specific CD terms.
6. Is the CD interest rate fixed?
Many standard CDs have a fixed rate for the selected term, although special CD products can have different rate structures.
7. Are CDs FDIC insured?
Eligible CDs held at an FDIC-insured bank are generally covered within applicable federal insurance limits and ownership categories.
8. What should I compare before opening a CD?
Compare APY, term length, minimum deposit, early withdrawal penalty, maturity rules, and applicable deposit insurance.
9. Can a CD be used for emergency savings?
Usually, emergency funds belong in an accessible account because you may need the money before a CD reaches maturity.
Once you understand How Does a CD Work, the next question is whether the term and withdrawal rules fit your own cash needs.
Final Verdict: Does a CD Fit Your Money?
How Does a CD Work is easy to understand once you separate the deposit, term, interest, and maturity date. The harder question is whether you can comfortably leave the money untouched for that period. If the answer is yes, a CD can give planned cash a defined place to earn interest.
Before opening one, keep emergency savings accessible and compare the APY, term, minimum deposit, early withdrawal penalty, and renewal rules. A higher rate is not automatically the better choice if you may need the money sooner.
For a broader look at CD rates, strategies, and account types, explore our
complete 2026 CD guide
.
The right CD is the one that fits your timeline, cash needs, and comfort with limited access—not simply the one showing the biggest number.
Related Resources
These guides can help you compare CD choices with savings accounts, understand APY, and protect your cash before making a deposit.
For official guidance, visit the
FDIC deposit-insurance resources
,
the
CFPB banking resources
,
and
NCUA share-insurance guidance
.
Get Smarter With Your Cash
Get practical banking and personal-finance guides, useful savings ideas, and fresh money tips from FinanceInvestment. No unnecessary noise—just useful information you can put to work.
Questions or suggestions?
subhashr325@gmail.com