Credit Union vs Bank: What’s the Difference?
Credit Union vs Bank: What’s the Difference?
 If you’re comparing a credit union vs bank, the difference goes deeper than the name on your debit card. Both can provide checking accounts, savings accounts, loans and other everyday financial services. The bigger distinction is how each institution is structured and who owns it. Credit unions are member-owned cooperatives, while banks generally operate as for-profit businesses.
That ownership difference can shape the way you experience an account, but it does not tell the whole story. Membership eligibility, interest rates, fees, branch networks, ATM access, digital tools and loan terms can vary widely from one institution to another. A national bank may offer broad access across the country, while a credit union may have a more limited footprint but serve a specific community, employer group or association.
The right comparison starts with your own banking habits. Do you need frequent branch visits? Is a large ATM network important? Are you mainly looking for a checking account, a savings account or a loan? Once you know what matters, comparing the actual account terms becomes much easier. For the broader picture, see our complete Credit Unions Explained guide.
THE BIG IDEA
A bank and a credit union can look similar from a customer’s perspective. The meaningful differences usually appear in ownership, membership, rates, fees, access and account protections.
What You’ll Learn
- How credit unions and banks are structured and owned.
- Why credit union membership can have eligibility requirements.
- How rates, fees, branches and digital banking may differ.
- How NCUA share insurance compares with FDIC deposit insurance.
- Which account features deserve attention before you open an account.
- Common mistakes to avoid when comparing the two.
Quick Answer: Credit Union vs Bank
The simplest credit union vs bank difference is ownership. A credit union is a member-owned cooperative, while a bank generally operates as a for-profit financial institution. Yet both can handle everyday needs such as checking, savings, payments and borrowing. What matters is how the specific institution’s terms fit your needs.
KEY TAKEAWAYS
- Credit unions are member-owned financial cooperatives.
- Banks and credit unions can offer many similar financial products.
- Credit union membership usually depends on eligibility rules.
- Interest rates, fees and account requirements vary by institution.
- Branch, ATM and online banking access can differ significantly.
- Qualifying accounts at federally insured credit unions can receive NCUA share insurance, subject to coverage rules and limits.
BOTTOM LINE
There isn’t one universal answer for every household. Compare the actual rates, fees, account features, access and applicable insurance before deciding where to keep your money.
Credit Union vs Bank at a Glance
A credit union and a bank can look similar when you use them day to day. Both may offer checking, savings, debit cards, online banking and loans. The bigger differences involve ownership, eligibility, governance and insurance.
| Feature | Credit Union | Bank |
|---|---|---|
| Ownership | Member-owned cooperative | Ownership structure varies by bank |
| Eligibility | Usually requires meeting the credit union’s field-of-membership rules | Usually based on the bank’s account-opening requirements |
| Governance | Members elect the board under applicable rules | Governed according to the bank’s corporate or ownership structure |
| Account Terms | Rates, fees and requirements vary by credit union | Rates, fees and requirements vary by bank |
| Federal Insurance | NCUA share insurance may apply at federally insured credit unions | FDIC deposit insurance may apply at FDIC-insured banks |
QUICK TAKE
The institution’s label is only the starting point. Before opening an account, compare the APY, interest rate, fees, minimums, ATM access, digital features and applicable federal insurance for the specific product.
Credit Union vs Bank: Complete Beginner Guide
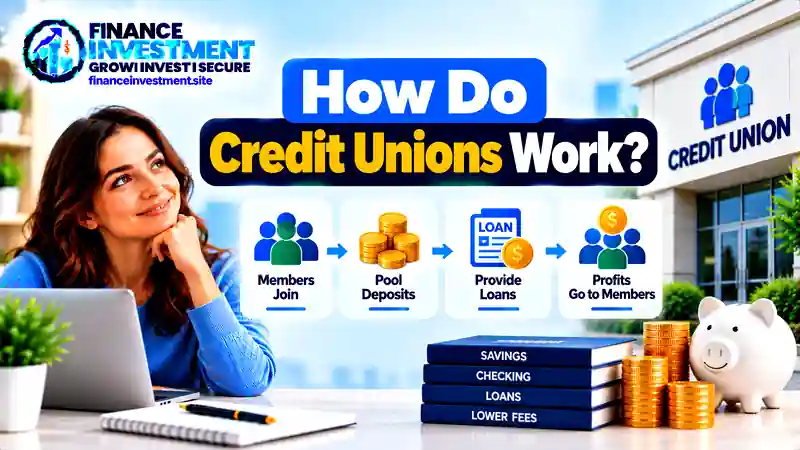 For a beginner, the easiest way to understand a credit union vs bank comparison is to follow the customer journey. You start by finding an institution that fits your needs, open an account, use its services and then compare how well the account works for you over time.
1. Check Whether You Can Join
With a credit union, eligibility comes first. A credit union generally has a defined field of membership. Depending on its charter, eligibility may be connected to where you live, where you work, a family relationship or membership in a qualifying organization. Once you qualify, the institution will explain its membership and account-opening requirements.
2. Compare the Account Before Opening It
Whether you choose a bank or credit union, look at the actual account rather than relying on the institution’s name. Check the monthly fee, minimum balance, opening deposit, transaction rules, ATM access and digital banking features. For checking accounts, our guide to how checking accounts work covers the basics beginners should understand.
3. Use the Account for Everyday Money
After opening an account, your daily routine may look similar at either type of institution. You might receive a debit card, set up direct deposit, pay bills, transfer money, deposit checks and manage your balance through online or mobile banking. The available features depend on the specific institution and account.
4. Apply for Loans When Needed
Banks and credit unions can both provide loans to qualified borrowers. The application process can involve reviewing income, credit history, existing obligations and other information. Rates, fees, approval standards and repayment terms vary by lender, so compare the complete cost rather than focusing only on the advertised rate.
5. Recheck the Fit Over Time
Your banking needs can change. A convenient account today may become less useful if fees increase, your location changes or you need different services. Review your account periodically and compare the rates, fees, access, features and applicable federal insurance with other available options.
BEGINNER TIP
Don’t start with “Which institution is better?” Start with “Which account meets my needs?” That shift makes the comparison more practical and easier to evaluate.
How Credit Unions and Banks Work
A useful way to understand the difference is to look at how each institution is organized and manages money. Both banks and credit unions can hold customer funds, provide payment services and make loans. However, their ownership structures and governing rules are different.
How a Credit Union Works
A credit union operates as a member-owned cooperative. Eligible individuals join under the institution’s field-of-membership rules and may need to maintain a required share account. The credit union manages member shares along with its other funding, investments, liquidity and capital. It can use its financial resources to make loans and provide services, while interest income, fees and other revenue help cover operating costs and support financial strength. Members also have a governance role under applicable rules.
How a Bank Works
A bank also manages deposits, lending, payments and other financial services. Deposits are part of the bank’s broader funding structure, while loans and investments are managed as part of its overall balance sheet. Interest income, fees and other revenue help the bank pay operating expenses and run its business. Banks can range from small community institutions to large national organizations, so the products and services available can vary widely.
Where the Difference Becomes Visible
For customers, the structural difference can show up in practical areas such as eligibility, account terminology, governance, rates, fees and access. Credit unions may also use shared-branch or cooperative ATM networks, while individual banks may operate their own branch and ATM networks or participate in other networks. The actual experience depends on the institution.
THE PRACTICAL DIFFERENCE
Both models manage money through funding, lending, payments and financial services. The key distinction is the structure behind those activities: a credit union is organized as a member-owned cooperative, while a bank follows its own ownership and corporate structure.
Credit Union vs Bank: Benefits & Drawbacks
Both credit unions and banks can be useful for everyday banking. The important point is that the experience can vary significantly between individual institutions. A feature that matters to one household may be less important to another.
Potential Credit Union Benefits
- Member ownership: Eligible members have an ownership interest in the cooperative.
- Member participation: Eligible members may have voting rights under the institution’s governing rules.
- Everyday services: Many credit unions offer checking, savings, cards and lending products.
- Cooperative structure: The institution is organized around its membership rather than outside stockholders.
Potential Credit Union Drawbacks
- Eligibility limits: You may need to meet specific membership requirements.
- Access differences: Branch and ATM availability depends on the institution and its networks.
- Technology differences: Mobile and online banking features can vary.
- Product selection: Some institutions may offer a narrower range of products than larger financial institutions.
AND WHAT ABOUT BANKS?
Banks can offer broad product selections, branch networks and digital services, but those features differ by institution too. Fees, minimum requirements, rates and account features also vary. That is why the most useful comparison is between the actual accounts and services you would use.
Credit Union vs Bank: Side-by-Side Comparison
The basic difference is easy to remember: credit unions are member-owned cooperatives, while banks follow their own ownership and corporate structures. The more useful comparison, however, is what those structures mean for the accounts and services you actually use.
| Feature | Credit Union | Bank |
|---|---|---|
| Ownership | Member-owned cooperative | Ownership structure varies by institution |
| Eligibility | Generally requires meeting the credit union’s field-of-membership rules | Generally requires meeting the bank’s account-opening requirements |
| Governance | Eligible members may vote under applicable governing rules | Governed according to the institution’s ownership and corporate structure |
| Accounts | Checking, savings and other products may use share terminology | Checking, savings and other deposit products are commonly available |
| Rates & Fees | Vary by institution, account and product | Vary by institution, account and product |
| Branch & ATM Access | Depends on the credit union and available networks | Depends on the bank and its branch or ATM networks |
| Digital Banking | Features and tools vary by institution | Features and tools vary by institution |
| Federal Insurance | Qualifying shares at federally insured credit unions may receive NCUA share insurance, subject to coverage rules | Qualifying deposits at FDIC-insured banks may receive FDIC deposit insurance, subject to coverage rules |
What This Means for Your Decision
The ownership difference matters, but it should not be the only thing you compare. If you rarely visit branches, digital features may matter more. If you use ATMs frequently, network access can become important. For borrowing, compare the full APR, fees and repayment terms. For savings, look at the APY and account requirements.
COMPARE THE ACTUAL PRODUCT
Before opening an account, compare the APY, APR, fees, minimum balance, ATM access, branch availability, digital features and applicable federal insurance. Those details tell you more about the account than the words “bank” or “credit union” alone.
Credit Union vs Bank: Costs, Risks & Expert Tips
The words “credit union” or “bank” don’t tell you what an account will cost. Both types of institutions can have fees, minimum requirements and different rates. Before opening an account, review the current fee schedule, account disclosures and terms for the specific product.
Costs to Check
- Monthly maintenance or service fees.
- Minimum balance and opening deposit requirements.
- Out-of-network ATM fees and other transaction charges.
- Overdraft, returned-payment or other account fees.
- Loan origination, late-payment and other borrowing costs.
Risks and Practical Limitations
Access can vary significantly. A credit union may have fewer physical branches than a large bank, although shared-branch arrangements or ATM networks may provide additional access. Banks also differ in branch coverage, ATM availability and digital features. You should also verify the institution’s federal insurance status and understand which accounts qualify for coverage.
Expert Tips Before You Open an Account
- Compare the APY or loan APR with the related fees.
- Check minimum balances and recurring requirements.
- Review ATM, branch and digital access based on your routine.
- Read overdraft and transaction rules before relying on the account.
- Confirm the applicable federal insurance program and coverage terms.
EXPERT TIP
Put the numbers side by side before deciding. A useful comparison includes the rate, recurring fees, one-time charges, access and account requirements for the exact products you are considering.
Common Credit Union vs Bank Mistakes + Illustrative Example
Choosing between a credit union and a bank can become confusing when the institution’s reputation gets more attention than the account itself. A few practical checks can make the comparison much clearer.
Mistakes to Avoid
- Assuming one type always costs less: Rates and fees vary by institution and product.
- Skipping eligibility checks: A credit union may have membership requirements you must satisfy before opening an account.
- Looking only at the headline rate: Check fees, minimum balances and other account conditions too.
- Ignoring everyday access: Consider ATM availability, branches and digital features based on your normal routine.
An Illustrative Example
Suppose Daniel needs a new checking account. He qualifies for a nearby credit union, while a national bank is also available to him. Instead of choosing based on the institution’s name, he compares the monthly fee, minimum balance, ATM access, mobile banking features, overdraft terms and direct-deposit options offered by each account.
That comparison gives Daniel a clearer picture of how each account would fit his routine. The example does not make one institution type the automatic winner. It shows why looking at the actual account terms can be more useful than relying on general assumptions about banks or credit unions.
THE LESSON
Start with your real banking habits. List the features you need, compare the specific accounts and then review their costs, access and applicable protections.
Who Should Choose a Credit Union or Bank?
There is no single option that fits every household. Your priorities may point toward one institution, while someone with different banking habits may choose another. Start by identifying what you need most from the account.
A Credit Union May Fit Your Needs If:
- You meet the institution’s membership eligibility requirements.
- You value having an ownership role in a cooperative institution.
- Its rates, fees and account features match your needs.
- Its branches, ATMs, shared networks or digital services are convenient for you.
A Bank May Fit Your Needs If:
- You need access to a particular bank’s branch or ATM network.
- You prefer the digital tools or account features offered by a specific bank.
- You need a product or service available through that institution.
- Its rates, fees and account requirements work for your situation.
A SIMPLE WAY TO COMPARE
Write down your top three priorities—such as low fees, convenient ATM access, digital banking or competitive loan terms. Then compare actual accounts against those priorities instead of choosing based only on the institution’s name.
Frequently Asked Questions About Credit Unions vs Banks
1. What is the main difference between a credit union and a bank?
The main structural difference is ownership. A credit union is a member-owned cooperative, while a bank operates according to its own ownership and corporate structure. Both can offer many similar financial services.
2. Are credit unions and banks insured in the same way?
No. Qualifying shares at federally insured credit unions may receive NCUA share insurance, while qualifying deposits at FDIC-insured banks may receive FDIC deposit insurance. Coverage depends on the institution, account ownership category, account type and applicable limits.
3. Do credit unions usually have lower fees than banks?
Fees vary by institution and account. Some credit unions may offer competitive fees, but you should compare the actual fee schedule rather than assume one type of institution will always cost less.
4. Can anyone join a credit union?
Not necessarily. Credit unions generally have a defined field of membership. Eligibility may depend on factors such as location, employment, family relationships or membership in a qualifying organization.
5. Are credit union accounts FDIC insured?
No. Federally insured credit unions use NCUA share insurance through the National Credit Union Share Insurance Fund. FDIC insurance applies to qualifying deposits at FDIC-insured banks. These are separate federal insurance programs with their own coverage rules.
6. Can a credit union offer checking and savings accounts?
Yes. Many credit unions offer both. They may use terms such as share savings and share draft accounts for products that function similarly to savings and checking accounts.
7. Which usually has more branches, a credit union or bank?
There is no universal answer. A particular bank may have a large branch network, while a credit union may provide access through its own locations, shared branches or ATM networks. Compare the access available where you live and travel.
8. What should I compare before choosing between a credit union and bank?
Compare eligibility, APY or APR, fees, minimum balances, ATM and branch access, digital banking features, account terms and applicable federal insurance. Then match those details with the way you plan to use the account.
Final Verdict: Credit Union vs Bank
The credit union vs bank comparison is ultimately about how each institution fits your financial needs. A credit union is a member-owned cooperative for eligible members, while a bank operates under its own ownership and corporate structure. Both can provide checking, savings, payments, lending and digital banking services.
The practical differences can appear in membership eligibility, rates, fees, branch and ATM access, digital tools and available products. Insurance also depends on the institution’s federal insurance status, the account involved and the applicable coverage rules.
Before opening an account, compare the specific products you would actually use. Look at the APY or APR, fees, minimum requirements, access, digital features and applicable federal insurance. Those details give you a clearer basis for comparing institutions than the label alone.
BOTTOM LINE
Banks and credit unions can both serve everyday banking needs. Compare the actual institution, account terms and available services against the way you plan to manage your money.
For a broader explanation of membership, accounts, fees and NCUA insurance, continue with our complete Credit Unions Explained guide.
Related Resources & Authority Sources
If you’re comparing banks, credit unions and other account options, these FinanceInvestment guides can help you explore the details that matter beyond the basic ownership difference. Start with the complete Credit Unions Explained guide for a broader look at membership, accounts, fees and NCUA insurance.
FINANCEINVESTMENT GUIDES
- Digital Banks vs. Credit Unions — useful when digital access is an important part of your comparison.
- Online Banks vs. Traditional Banks — explores another important difference in banking access.
- Checking Accounts in the USA — helpful when your main goal is everyday spending and payments.
- What Is an ATM Network? — explains why ATM access can matter when comparing institutions.
- Savings Account vs. Checking Account — useful when deciding which type of account you actually need.
Official Authority Sources
- NCUA Share Insurance FAQs — official information about federal share insurance for qualifying accounts at federally insured credit unions.
- NCUA Field of Membership Resources — explains the rules that determine who may qualify for credit union membership.
- FDIC Deposit Insurance — official information about deposit insurance at FDIC-insured banks.
RESEARCH TIP
Banking terms and account features can change. Before opening an account, check the institution’s current disclosures and official regulator information for rates, fees, eligibility and applicable insurance coverage.
Have a Money Question? Keep Exploring.
Your banking choice is only one part of a larger money plan. Keep exploring the account features, costs, access and protections that can shape your everyday financial decisions.
📩 Get in Touch With FinanceInvestment
Have a personal-finance question or a topic you’d like FinanceInvestment to explain?