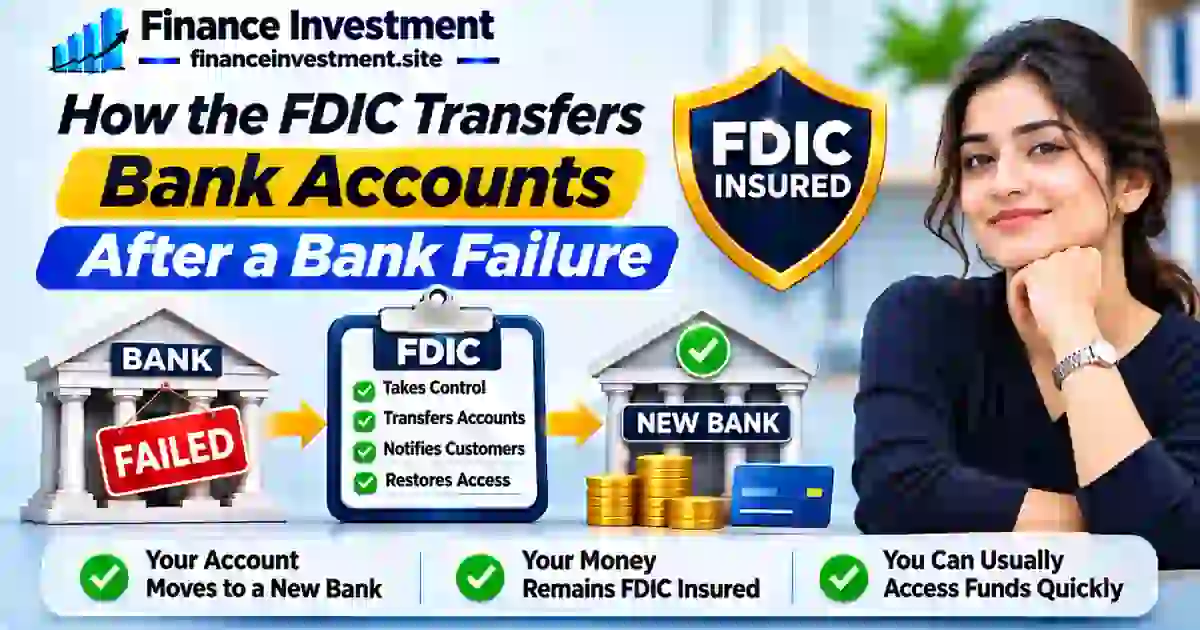
How the FDIC Transfers Bank Accounts After a Bank Failure
 What Happens to Your Bank Account When Another Bank Takes Over?
Your bank closes on Friday. By Monday, another institution may be handling your deposits. But what happens to your paycheck, debit card and automatic bill payments? Understanding how the FDIC transfers bank accounts after a bank failure helps you separate what usually continues from what needs checking.
When regulators close an FDIC-insured bank, the FDIC may arrange for an acquiring bank to assume its deposits. Customers often keep access to familiar banking services during the transition, although account terms and operating arrangements can change. For the broader rules protecting eligible deposits, see our FDIC and NCUA Insurance Explained guide.
What You’ll Learn
- How an FDIC-assisted transfer to an acquiring bank works.
- Whether account numbers, checks and debit cards may continue working.
- What happens to payroll deposits and recurring payments.
- Which account changes require customer action.
- How to verify official notices and your deposit insurance coverage.
Quick Answer: How Does the FDIC Transfer Bank Accounts?
When an FDIC-insured bank fails, the FDIC may arrange for another bank to assume its deposits. Customers generally become depositors of the acquiring bank without opening replacement accounts themselves. However, the transition depends on the specific agreement, and customers should follow official instructions about account services and future changes.
6 Key Takeaways
- Transfer isn’t automatic in every failure: The FDIC may use another resolution method.
- Your deposits may move: An acquiring bank can assume eligible deposit accounts.
- Account details may continue: Existing numbers and checks may work initially, but confirm instructions.
- Payments need attention: Review direct deposits and scheduled bill payments.
- Insurance rules still matter: Coverage depends on ownership categories and deposit totals.
- Official notices come first: Check FDIC and acquiring-bank announcements before making changes.
Bottom Line: An FDIC-arranged transfer can keep banking services running with limited disruption. It does not guarantee that every account feature or payment arrangement will remain unchanged.
At a Glance: FDIC Bank Account Transfers
| Stage | What Happens |
|---|---|
| Closure announced | Regulators close the bank; the FDIC publishes customer instructions. |
| Deposits transferred | If an acquiring bank assumes deposits, affected accounts become its responsibility. |
| Customer transition | Customers follow instructions about access, payments and account changes. |
Quick Take: Many bank resolutions happen over a weekend, but that is not a guaranteed transfer deadline. FDIC insurance limits determine coverage, not how quickly every banking service resumes.
What Happens to Your Existing Bank Account?
You usually don’t need to open a replacement account when another bank assumes your deposits. Your checking, savings or CD balance becomes a deposit liability of the acquiring institution. What changes next depends on the accounts transferred and the new bank’s instructions.
Checking and Savings Accounts
The acquiring bank takes responsibility for assumed deposit balances. Existing checks, account numbers and debit cards may continue working temporarily, but don’t assume every service will remain unchanged. Review notices about fees, online banking and payment instructions.
Certificates of Deposit (CDs)
Transferred CDs require a closer look. Depending on the agreement and applicable rules, the acquiring bank may have options to change certain terms, including interest rates, with required notice and withdrawal rights. Our guide to CDs after a bank failure covers these situations.
What About FDIC Insurance?
If you already bank with the acquiring institution, transferred deposits may receive temporary separate FDIC coverage under applicable rules. This protection isn’t indefinite, and CDs can have special treatment. Learn more in our FDIC insurance at different banks guide.
How the FDIC Transfers Deposits to Another Bank
A failed bank doesn’t simply hand its customer accounts to a competitor. The FDIC follows a formal resolution process, often using a purchase-and-assumption (P&A) agreement. Here’s how that process typically works.
Step 1: The FDIC Evaluates Potential Buyers
Before a possible closure, the FDIC may seek bids from qualified institutions. It evaluates available resolution options under applicable legal requirements, including cost considerations. A buyer isn’t guaranteed.
Step 2: Regulators Close the Failed Bank
The appropriate banking authority closes the institution and appoints the FDIC as receiver. The FDIC then carries out the selected resolution arrangement.
Step 3: An Acquiring Bank Assumes Deposits
Under a P&A agreement, the acquiring bank assumes specified liabilities, including deposits covered by the agreement, and may purchase selected assets. The exact terms determine which obligations transfer.
Step 4: Customers Receive Transition Instructions
The FDIC announces the resolution, while the acquiring bank provides details about branches, accounts and available services. Customers should verify those instructions before changing payment arrangements.
Important distinction: If no suitable transfer is arranged, the FDIC may use another resolution method, including direct payment of insured deposits. A P&A transaction is not the outcome of every bank failure.
Benefits and Drawbacks of an FDIC-Arranged Bank Transfer
Having another bank take over deposits can spare customers the trouble of opening new accounts immediately. But the experience isn’t always seamless, especially when payment services or account terms change.
✓ Potential Benefits
- Fewer steps: Assumed deposits generally transfer without individual applications.
- Possible continuity: Some branches and payment services may keep operating.
- Temporary familiarity: Existing checks and cards may remain usable.
- Identifiable provider: Customers know which institution now holds their transferred deposits.
✕ Possible Drawbacks
- Different terms: Fees, rates or account features may change.
- Service interruptions: Certain transactions may be temporarily unavailable.
- Extra follow-up: Some customers must update payment or account details.
- Insurance complexity: Existing balances at the acquiring bank may require a coverage review.
FDIC Account Transfer vs. Direct Insurance Payout
The FDIC can resolve a failed bank in different ways. An acquiring bank may assume deposits under a transfer agreement, while a direct payout provides insured funds without continuing the original banking relationship.
| Feature | Account Transfer | Direct FDIC Payout |
|---|---|---|
| Deposit treatment | An acquiring bank assumes deposits specified in the agreement, potentially including uninsured balances. | The FDIC pays insured deposits; uninsured amounts are handled through receivership claims. |
| Account continuity | Some account services may continue under the acquiring bank. | The failed-bank account generally stops operating as a regular bank account. |
| Customer action | Review notices and confirm payment instructions. | Follow FDIC instructions for receiving insured funds. |
| Access to money | Available through the acquiring bank according to its transition arrangements. | Provided through the FDIC’s payment process, with timing depending on the circumstances. |
Quick Take: A transfer can preserve parts of your existing banking routine. A direct payout focuses on returning insured deposits. Neither outcome guarantees that every payment service will remain available without interruption.
Account Numbers, Cards, Direct Deposits and Expert Tips
A bank takeover can affect more than your account balance. Before making changes, check how the acquiring bank plans to handle your everyday transactions.
Account Numbers, Routing Numbers and Cards
Existing account numbers, checks and debit cards may continue working initially. Routing numbers and online banking access can change later. Follow the acquiring bank’s instructions rather than assuming old or new details will work indefinitely.
Direct Deposits and Automatic Bills
Payroll deposits, benefits and recurring payments may continue during the transition. Check upcoming transactions and update instructions only when officially required. If an expected payment doesn’t arrive, our late direct deposit guide explains common causes.
Fees and Account Terms
The acquiring bank may eventually change certain fees, rates or services, subject to applicable rules and notice requirements. Read account disclosures before deciding whether to stay.
Expert Tip: Save official transition notices. Check your next deposit and upcoming bills, then update payment details only if the acquiring bank instructs you to do so.
Fraud Warning: Don’t send money or share login credentials in response to an unexpected takeover message. Verify requests using the FDIC’s official failed-bank notice or independently confirmed bank contact details.
Common Mistakes After a Bank Transfer
Even when another bank takes over deposits, customers can create unnecessary problems by acting too quickly—or ignoring important notices.
- Moving money immediately: Confirm where your deposits are held before initiating transfers.
- Ignoring account notices: Review changes to banking access, fees and payment instructions.
- Assuming every payment will work: Check upcoming deposits and scheduled bills.
- Overlooking FDIC limits: Review combined balances if you already bank with the acquiring institution.
- Trusting unexpected messages: Verify takeover instructions through official sources.
Example: A Family With $24,000 in Deposits
Imagine a family has $9,000 in checking and $15,000 in savings at an FDIC-insured bank that fails. An acquiring bank assumes both deposits under its agreement.
The family generally doesn’t need to apply separately to move those balances. However, they should verify their new banking arrangements and confirm that upcoming bills and deposits are processed correctly.
Key lesson: A deposit transfer can simplify the transition, but checking your account details remains important.
Who Should Act First After an FDIC Bank Transfer?
Most customers can begin by reviewing official transition notices. Those with upcoming essential payments or substantial deposits may need to check a few details sooner.
Families With Upcoming Bills
Confirm access to money needed for rent, mortgage payments, utilities and other essential expenses. Check whether scheduled payments require updated instructions.
Retirees Receiving Regular Income
Review upcoming Social Security or pension deposits. If the acquiring bank announces account changes, confirm whether the paying agency needs new details.
Savers With Large Deposits
Check combined balances and ownership categories, especially if you already have deposits at the acquiring bank. Transferred deposits may receive temporary separate FDIC coverage under specific rules. Read our guide to protecting more than $250,000.
Frequently Asked Questions About FDIC Bank Transfers
1. Does the FDIC transfer every failed bank account?
No. Transfers depend on the resolution arrangement. If deposits aren’t assumed by another institution, the FDIC may pay insured amounts directly.
2. Will my bank account number change?
Not necessarily. Existing numbers may work during the transition, but the acquiring bank can announce changes.
3. Can I continue using my debit card and checks?
Possibly. Their availability depends on the acquiring bank’s arrangements and any replacement instructions.
4. What happens to direct deposits?
They may continue under existing instructions. Confirm upcoming payments and update account details if officially required.
5. Are transferred deposits still FDIC-insured?
Eligible deposits remain subject to FDIC limits. Temporary separate coverage may apply when transferred deposits overlap with existing balances at the acquiring bank.
6. When can I access my transferred money?
Access often resumes quickly, but the exact timing and available services depend on the resolution arrangements.
7. Can the acquiring bank change fees or interest rates?
Some terms may change under applicable rules and notices. Certificates of deposit can have additional protections and conditions.
8. Where can I verify the acquiring bank?
Use the FDIC’s official failed-bank notices to confirm the resolution and customer instructions.
Final Verdict: What an FDIC Bank Transfer Means for You
An FDIC-arranged deposit transfer can make a bank failure less disruptive by moving specified deposits to an acquiring institution. However, not every failure results in a transfer, and some banking services or account terms may change.
Before making decisions, verify the acquiring bank, review official customer notices and check essential payments. Those simple steps can help you avoid unnecessary account changes and missed transactions.
Bottom Line: Knowing how deposit insurance works is equally important. Read our FDIC and NCUA insurance guide to understand coverage limits and ownership categories.
Have a Money Question? Keep Exploring.
A bank failure can leave you wondering what happens to your savings, paycheck or upcoming bills. Understanding FDIC deposit transfers and checking official instructions can help you make informed decisions without unnecessary account changes.
Keep learning with our FDIC and NCUA insurance guide, or explore how to verify FDIC insurance before choosing a bank.
Disclaimer: This article is for general educational purposes and is not personalized financial, legal or tax advice. FDIC insurance coverage, deposit transfers and account access depend on applicable rules and the specific bank resolution. Verify current instructions through official FDIC notices or your financial institution.