Tag: 2026 Banking Guide

  • Credit Union Savings vs High-Yield Savings: Which Is Better in 2026?

    Credit Union Savings vs High-Yield Savings: Which Is Better in 2026?

    Credit Union Savings vs High-Yield Savings: Which Is Better in 2026?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 3, 2026
    Updated: October 3, 2026
    Reading Time: 10–12 min

    Credit Union Savings vs High-Yield Savings: How Are They Different?Credit Union Savings vs High-Yield Savings

    Saving money is simple. Choosing the right account can be less so. A credit union savings account and a high-yield savings account can both help your cash earn interest, but the accounts may differ in rates, fees, access, membership requirements, and the institution providing them.

    The key distinction is that a credit union savings account describes an account offered by a member-owned financial cooperative. A high-yield savings account describes a savings account that offers a relatively competitive yield. A HYSA can be offered by a bank or a credit union, so the two terms are not exact opposites.

    If you are new to credit unions, start with our complete guide to credit unions. Then use this comparison to evaluate APY, account access, fees, insurance, and other practical details before deciding where your savings belong.

    What You’ll Learn

    • How credit union savings accounts and high-yield savings accounts work.
    • How APYs, fees, access, and membership rules can differ.
    • How federal insurance can apply to eligible savings accounts.
    • What to compare before moving your savings.

    Quick Answer: Credit Union Savings vs High-Yield Savings

    The right choice depends on the account and your priorities. A credit union savings account may offer member-focused service and access to other credit union products. A high-yield savings account may appeal if a competitive APY and convenient online access are important to you. Since a high-yield account can also be offered by a credit union, compare the actual account terms rather than relying on the label alone.

    Key Takeaways

    • Compare APY when evaluating savings accounts.
    • Check monthly fees, minimum balance requirements, and account rules.
    • Confirm whether the institution provides applicable federal deposit or share insurance.
    • Check whether a credit union has membership eligibility requirements.
    • Consider branch access, digital banking tools, customer service, and transfer convenience.
    Bottom line: Look beyond the account name. APY, fees, insurance, access, and features can all affect how useful a savings account is for you.

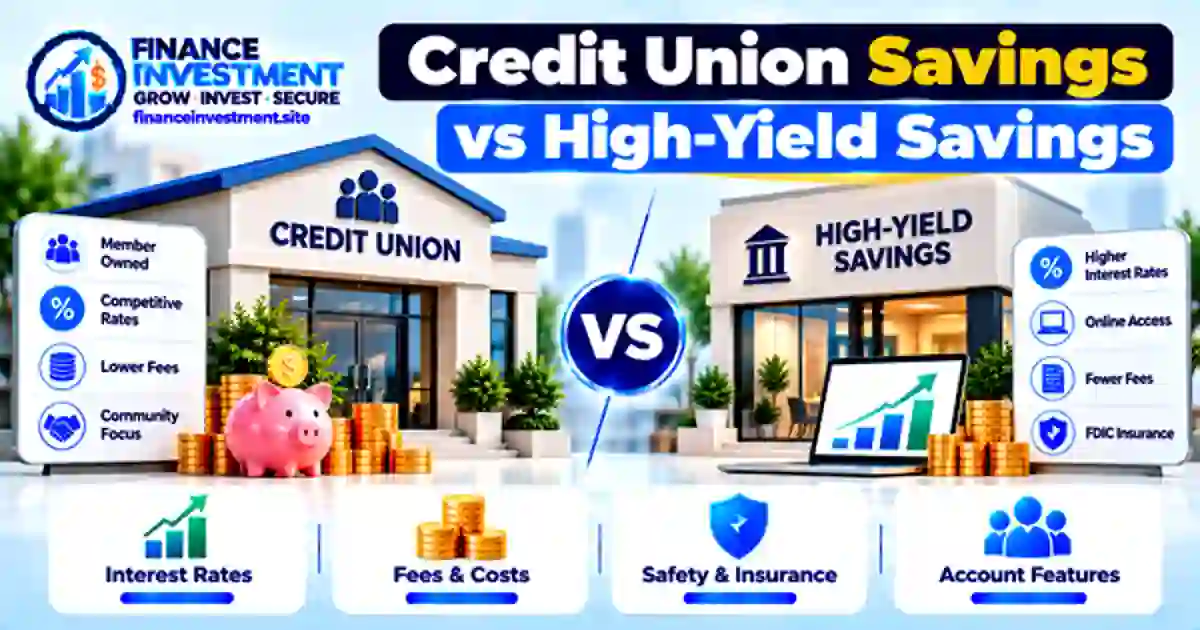
    Credit Union Savings vs High-Yield Savings: At a Glance

    Credit Union SavingsA savings account offered by a member-owned credit union. Membership eligibility may apply.
    High-Yield SavingsA savings account offering a relatively competitive APY. It may be offered by a bank or credit union.
    Federal InsuranceEligible bank deposits may have FDIC insurance, while eligible federal credit union shares may have NCUA share insurance.
    FactorCredit Union SavingsHigh-Yield Savings
    Account typeSavings account offered by a credit unionSavings account marketed around a competitive yield
    MembershipCredit union eligibility may be requiredDepends on the bank or credit union offering the account
    APYVaries by credit union, account, and current rateVaries by provider, account, and current rate
    AccessBranch, ATM, phone, and digital options varyDigital access may be a major feature, depending on the provider
    QUICK TAKE: Compare the specific account rather than assuming one category always offers a better deal. Look at APY, fees, insurance, access, membership requirements, and account features together.

    Credit Union Savings vs High-Yield Savings: A Beginner GuideCredit Union Savings vs High-Yield Savings

    The easiest way to understand this comparison is to separate the institution from the account’s yield. A credit union savings account is offered by a member-owned credit union. You may need to meet the credit union’s membership requirements before opening one.

    A high-yield savings account, or HYSA, is a savings account that offers a relatively competitive APY. “High-yield” describes the account’s earning potential, not who owns the institution. A bank or a credit union can offer a high-yield savings account.

    For beginners, both can be useful places for money needed in the near term. You might use one for an emergency fund, a planned purchase, or cash you want to keep separate from long-term investments. The practical differences usually come down to APY, fees, minimum balance rules, access, membership requirements, and insurance.

    Beginner tip: Compare the full account terms instead of chasing the highest advertised number. Check the current APY, fees, balance requirements, access options, membership rules, and applicable federal insurance before opening an account.

    If credit unions are new to you, our complete credit union guide explains membership, services, and how these institutions work.

    How Credit Union Savings and High-Yield Savings Work

    The basic idea is similar with both accounts: you deposit money, the institution calculates earnings according to the account terms, and you can access your balance subject to its rules. The main differences appear in how the institution is structured, how earnings are described, and what account conditions apply.

    How Credit Union Savings Works

    A credit union savings account is typically tied to membership. After meeting the credit union’s eligibility requirements, you can open an account under its terms. Credit unions may refer to savings earnings as dividends rather than interest. The dividend rate, APY, minimum balance, fees, and access options vary by institution and account.

    How High-Yield Savings Works

    A high-yield savings account works much like a regular savings account, but it is marketed around a relatively competitive APY. You deposit funds and earn interest based on the provider’s current terms. The APY is generally variable, so it can change after you open the account.

    Key point: The account’s current terms matter more than the label. Before opening one, compare APY, fees, balance requirements, access rules, and applicable federal insurance.

    Benefits and Drawbacks of Credit Union Savings vs High-Yield Savings

    Both account types can help you keep short-term money accessible while earning a return. The actual advantages and limitations depend on the institution, account terms, and how you plan to use the money.

    Credit Union Savings

    Potential benefits:

    • Member-owned structure and access to other credit union services.
    • Some credit unions provide branch-based or personalized service.
    • Some accounts may offer competitive dividends or APYs.

    Potential drawbacks:

    • Membership eligibility requirements can apply.
    • Branch, ATM, and digital access vary by credit union.
    • APYs, fees, minimum balances, and other terms differ by account.

    High-Yield Savings

    Potential benefits:

    • May offer a competitive APY compared with some lower-yield savings accounts.
    • Online and mobile tools can make account management convenient.
    • Can be offered by either a bank or a credit union.

    Potential drawbacks:

    • APYs can change over time.
    • Some accounts may have minimum balance, fee, or other account conditions.
    • Branch access may be limited depending on the provider.
    Quick takeaway: APY is only one part of the decision. Compare the account’s fees, access, membership requirements, insurance, minimum balances, and other terms before moving your savings.

    Credit Union Savings vs High-Yield Savings: Detailed Comparison

    The clearest way to compare these accounts is to look at the actual terms. A credit union savings account describes where the account is offered, while “high-yield” describes the account’s earning potential. The two can overlap, so the institution and account details both matter.

    FactorCredit Union SavingsHigh-Yield Savings
    ProviderOffered by a member-owned credit unionCan be offered by a bank or credit union
    APYVaries by credit union and accountVaries by provider and account
    MembershipEligibility requirements may applyDepends on the provider; bank accounts generally do not use credit union membership rules
    FeesVaries by credit union and accountVaries by provider and account
    AccessBranch, ATM, phone, and digital options varyOnline, mobile, ATM, and branch access vary by provider
    Federal insuranceEligible accounts at federally insured credit unions may have NCUA share insuranceEligible deposits at FDIC-insured banks may have FDIC insurance; a credit union HYSA follows applicable NCUA share-insurance rules
    EarningsMay be described as dividends and reported through the account’s APYGenerally earns interest reported through the account’s APY

    What Should You Compare First?

    Start with the APY, fees, and minimum balance requirements. Then look at how easily you can deposit, transfer, and withdraw money. If you are considering a credit union, confirm that you qualify for membership and understand the services available to members.

    Finally, verify the institution’s applicable federal insurance and coverage rules. Checking these details together gives you a clearer picture than comparing the words “credit union” and “high-yield” by themselves.

    Costs, Access, Risks & Practical Tips

    The account with the highest APY is not automatically the most useful one. Before opening an account, look beyond the advertised yield and check the costs, access options, and conditions attached to the account.

    Costs and Account Rules

    Review monthly maintenance fees, minimum balance requirements, and any conditions that affect the account’s APY. Also check the provider’s current terms for transfers, withdrawals, deposits, and other account activity.

    Access and Safety

    Think about how you normally move money. Depending on the provider, you may have branches, ATMs, online transfers, mobile banking, or other deposit options. Before depositing money, verify whether the institution provides applicable NCUA share insurance or FDIC deposit insurance.

    Practical Tips Before You Open

    • Compare the APY with the account’s fees and requirements.
    • Confirm the institution’s applicable federal insurance and coverage rules.
    • Make sure deposits, transfers, and withdrawals are convenient for your needs.
    • Recheck the account terms when rates, fees, or your savings goals change.
    Simple rule: Compare the total account experience, not just the APY. A slightly different rate can matter less than fees, access, or account restrictions.

    Common Mistakes to Avoid

    A savings account can have an attractive APY and still include terms that do not fit your needs. A few simple checks can help you make a more complete comparison.

    • Looking only at APY: Compare the yield with fees, minimum balances, and other account conditions.
    • Overlooking membership rules: A credit union may require you to meet specific eligibility requirements.
    • Assuming every HYSA is online-only: A high-yield savings account can be offered by a bank or credit union, with access options that vary.
    • Skipping the insurance check: Confirm the institution’s applicable federal insurance before placing a large balance in the account.
    • Forgetting that APYs can change: Savings rates are generally variable, so the advertised APY can change after you open the account.

    Real-Life Example

    Illustrative example: Suppose a family has $15,000 set aside as an emergency fund. Account A offers a higher current APY, while Account B offers a different APY along with branch access that is more convenient for the family.

    Instead of comparing the APYs alone, the family reviews fees, minimum balance requirements, insurance, transfer options, and access. They can then weigh the account terms against how they actually expect to use the emergency fund.

    Who Should Choose Which?

    The right account depends on how you plan to use your savings. Consider your access needs, credit union eligibility, desired yield, fees, and the services you expect from the provider.

    Consider Credit Union Savings If…

    • You qualify for membership and want to use the credit union’s other financial services.
    • Branch, ATM, phone, or local service options are important to you.
    • The credit union’s APY, fees, minimum balance, and account rules work for your savings goals.

    Consider a High-Yield Savings Account If…

    • The account’s APY is an important factor in your savings comparison.
    • You are comfortable managing your savings through online or mobile banking.
    • The provider’s fees, access options, insurance, and other terms meet your needs.
    Using both is possible: You can keep one savings account at a credit union and another with a separate provider if each account has a clear purpose. Compare each account on its own terms rather than assuming one category is automatically better.

    Credit Union Savings vs High-Yield Savings: FAQs

    1. Is a credit union savings account the same as a high-yield savings account?

    No. A credit union savings account describes an account offered by a credit union, while high-yield savings describes an account offering a relatively competitive APY. A credit union can also offer a high-yield savings account.

    2. Can a credit union offer a high-yield savings account?

    Yes. “High-yield” describes the account’s earning potential. It does not identify a separate type of financial institution.

    3. Are credit union savings accounts NCUA insured?

    Eligible shares at federally insured credit unions may be covered by NCUA share insurance, subject to applicable coverage rules and limits.

    4. Are high-yield savings accounts FDIC insured?

    An eligible HYSA offered by an FDIC-insured bank may be covered by FDIC deposit insurance, subject to applicable rules and limits. If the account is offered by a credit union, NCUA share-insurance rules may apply instead.

    5. Do credit union savings accounts pay interest?

    Credit unions generally describe earnings on savings shares as dividends rather than interest. The dividend rate and APY depend on the credit union and the account’s current terms.

    6. Can a high-yield savings APY change?

    Yes. Savings APYs are generally variable, so the rate can change after you open the account.

    7. Which is safer: credit union savings or a HYSA?

    The account label alone does not determine safety. Check the institution’s insurance status, the type of account, and the applicable coverage rules. Eligible bank deposits may have FDIC insurance, while eligible shares at federally insured credit unions may have NCUA share insurance.

    8. Can I have both a credit union savings account and a HYSA?

    Yes. You can use separate savings accounts for different purposes. Compare each account’s APY, fees, access, insurance, and other terms.

    Final Verdict: Credit Union Savings vs High-Yield Savings

    The comparison comes down to the specific account, not simply the label. A credit union savings account and a high-yield savings account can have different APYs, fees, access options, membership requirements, and account conditions.

    For a meaningful comparison, review the current APY, fees, minimum balance requirements, transfer and withdrawal options, customer access, and applicable federal insurance. Also remember that a high-yield savings account can be offered by either a bank or a credit union.

    The key takeaway: Compare the actual account terms and how they match your savings needs. A higher APY is only one part of the overall comparison.

    If you are still learning how credit unions work, our complete guide to credit unions explains membership, services, and the basic structure of these financial institutions.
    Have a Money Question? Keep Exploring.

    Keep learning with practical FinanceInvestment guides on savings, credit unions, cash management, and everyday investing decisions.

    Before opening or switching an account, compare the current APY, fees, access options, account requirements, and applicable insurance coverage.
  • Best Savings Accounts for Families in 2026: Compare Top Family Savings Options

    Best Savings Accounts for Families in 2026: Compare Top Family Savings Options


    FI

    FinanceInvestment Editorial Team

    Independent personal finance researchers dedicated to helping American families make smarter banking, saving, and investing decisions through accurate, practical, and easy-to-understand financial guides.


    ✍ Written by FinanceInvestment Editorial Team   Subhash                Rukade.


    ✔ Reviewed by Financial Research Team


    ✓ Fact Checked


    📅 Updated: July 23, 2026


    ⏱ Reading Time: 12 Minutes


    🛡 Editorial Integrity Reviewed

    This guide was researched using publicly available information from reputable financial institutions and government resources. Our editorial team evaluates savings account features, interest rates, fees, accessibility, and consumer protections to provide unbiased recommendations for families in the United States.


    Best Savings Accounts for Families in 2026

    Best Savings Accounts for FamiliesFinding the best savings accounts for families isn’t just about earning a higher interest rate. It’s about choosing an account that helps your household save for both everyday needs and long-term goals. Whether you’re building an emergency fund, planning a family vacation, saving for your child’s education, or preparing for retirement, the right savings account can make managing money much easier.

    With so many banks offering different APYs, fees, mobile apps, and family-friendly features, deciding where to keep your savings can feel overwhelming. Some accounts reward larger balances, while others focus on flexibility, digital banking, or automatic savings tools. Knowing what matters most can help you avoid unnecessary fees and earn more from your money.

    This guide is designed to simplify the process. You’ll learn how best savings accounts for families work, which features deserve your attention, how to compare banks confidently, and the common mistakes families should avoid before opening an account. We’ll also explain how high-yield savings accounts compare with traditional bank accounts and what to consider before making a final decision.

    By the end of this guide, you’ll have the knowledge to choose a savings account that fits your family’s financial goals, keeps your money secure, and helps every dollar work harder for your future.


    💡 Quick Answer

    If you’re looking for the best savings accounts for families, focus on more than just the highest APY. A great family savings account should offer competitive interest rates, no monthly maintenance fees, FDIC insurance, easy online access, and tools that make saving for multiple goals simple. The right account can help your family grow an emergency fund, prepare for future expenses, and keep your savings secure while earning interest.

    📌 Key Takeaways

    • Choose accounts with competitive APYs and no monthly maintenance fees.
    • Make sure the bank offers FDIC insurance for eligible deposits.
    • Compare mobile banking features, automatic savings tools, and account accessibility.
    • Look for flexible options that support both short-term and long-term family goals.
    • Review balance requirements and withdrawal rules before opening an account.
    • Compare several banks instead of selecting the first account you find.

    Bottom Line: The best savings accounts for families combine strong returns, low costs, and convenient banking features, making it easier to build financial security for every stage of family life.


    Table of Contents

    1. What Are Family Savings Accounts?
    2. How Family Savings Accounts Work
    3. Benefits and Drawbacks
    4. Comparison of Popular Savings Account Options
    5. Costs, Risks, and Expert Tips
    6. Common Mistakes to Avoid
    7. Who Should Open a Family Savings Account?
    8. Frequently Asked Questions
    9. Final Verdict


    Best Savings Accounts for Families at a Glance

    The best savings accounts for families help households save for both planned and unexpected expenses while earning interest on their money. Whether you’re building an emergency fund, saving for your children’s education, planning a vacation, or preparing for retirement, choosing the right account can make reaching those goals much easier.

    Not every savings account offers the same value. Some banks focus on higher Annual Percentage Yields (APYs), while others provide better digital banking tools, lower fees, or features designed for busy families. Comparing these details before opening an account can help you maximize your savings and avoid unnecessary costs.

    FeatureQuick Overview
    Best ForFamilies building emergency funds and long-term savings.
    Interest EarningsCompetitive APYs help savings grow faster than many traditional accounts.
    Monthly FeesMany top accounts charge no monthly maintenance fee.
    SafetyLook for FDIC-insured banks to protect eligible deposits.
    Digital FeaturesMobile apps, automatic transfers, and savings goal trackers.
    Ideal Savings GoalsEmergency funds, education, home improvements, vacations, and future family expenses.

    Quick Summary: The best savings accounts for families offer a balance of competitive interest rates, low fees, convenient online banking, and secure FDIC protection. Choosing an account that matches your family’s financial goals can make saving easier and more rewarding over time.


    Complete Beginner’s Guide to Family Savings Accounts

    Best Savings Accounts for FamiliesIf you’ve never opened a family savings account before, don’t worry. The process is simpler than many people expect. The best savings accounts for families are designed to help households save money safely while earning interest. They also make it easier to prepare for both planned expenses and unexpected emergencies.
    A family savings account can be used for many financial goals. Some families save for a home down payment, while others build an emergency fund, set aside money for their children’s education, plan vacations, or prepare for major life events. Keeping these savings separate from everyday spending can make budgeting much easier.

    When comparing accounts, don’t focus only on the advertised APY. A higher interest rate is valuable, but you should also look at monthly maintenance fees, minimum balance requirements, withdrawal policies, customer service, and mobile banking features. Many online banks offer competitive rates along with helpful tools such as automatic transfers, savings goals, and spending alerts.

    Security is another important factor. Choose a bank that offers FDIC insurance for eligible deposits so your family’s savings remain protected. It’s also helpful to select an account with a simple mobile app that allows you to monitor balances, schedule transfers, and track your progress toward financial goals.

    The best savings accounts for families are those that fit your household’s needs, encourage consistent saving, and provide easy access when you need your money. Starting with regular monthly deposits—even small ones—can create healthy financial habits and help your savings grow steadily over time.


    How Family Savings Accounts Work

    The best savings accounts for families work much like a standard savings account, but they’re used to help households save for shared financial goals. After opening an account, you can deposit money whenever it fits your budget. As your balance grows, the bank pays interest based on the account’s Annual Percentage Yield (APY), allowing your savings to increase over time.

    Many families set up automatic transfers from their checking account every payday. This simple habit makes saving consistent and removes the need to remember monthly deposits. Even modest contributions can add up over time, especially when interest is earned on the growing balance.

    Most banks also provide online and mobile banking, making it easy to check your balance, schedule transfers, track savings goals, and monitor account activity from anywhere. Some accounts even include budgeting tools and savings trackers that help families stay focused on their financial plans.

    While the best savings accounts for families make it easy to access your money when needed, they’re designed for saving rather than everyday spending. Keeping these funds separate from your regular checking account can reduce unnecessary spending and help you stay on track toward important goals such as building an emergency fund, paying for education, or planning future family expenses.


    Benefits and Drawbacks of Family Savings Accounts

    The best savings accounts for families can help households build financial security while keeping money easily accessible for future needs. However, like any financial product, they have both advantages and limitations. Understanding both sides can help you choose an account that matches your family’s goals.

    ✅ Pros

    • Earn interest while keeping your money available when needed.
    • Many accounts have no monthly maintenance fees.
    • FDIC insurance protects eligible deposits.
    • Automatic transfers make regular saving easier.
    • Mobile banking apps help families track balances and savings goals.
    • Suitable for emergency funds, education savings, vacations, and other long-term family goals.

    ❌ Cons

    • Interest rates may change over time.
    • Some banks require a minimum balance to earn the highest APY.
    • Certain accounts may limit specific types of withdrawals or transfers.
    • Returns are generally lower than long-term investment options.
    • Account features and digital tools vary between banks.

    Overall, the best savings accounts for families provide a safe and flexible way to build savings. Comparing fees, interest rates, and account features before opening an account can help your family receive the greatest long-term value.


    Compare Different Family Savings Account Options

    Choosing the best savings accounts for families becomes easier when you compare the features that matter most. While every family has different financial goals, factors such as interest rates, monthly fees, digital banking tools, account accessibility, and FDIC protection can make a significant difference over time.

    The table below highlights the key differences you should evaluate before opening a family savings account.

    FeatureTraditional BankOnline BankBest Choice
    Interest Rate (APY)Usually lowerOften more competitiveOnline Bank
    Monthly FeesMay applyOften no monthly feeOnline Bank
    Branch AccessExcellentLimited or noneTraditional Bank
    Mobile BankingGoodExcellentOnline Bank
    Automatic Savings ToolsAvailable at some banksCommon featureOnline Bank
    FDIC InsuranceYes (eligible deposits)Yes (eligible deposits)Both

    For many households, the best savings accounts for families are those that balance competitive interest rates, low fees, reliable customer service, and convenient digital banking. Comparing these features before opening an account can help your family choose a solution that supports both short-term needs and long-term financial goals.


    Costs, Risks, and Expert Tips

    The best savings accounts for families are often affordable, but it’s still important to understand the costs before opening an account. Many banks offer family savings accounts with no monthly maintenance fee, while others may charge fees if your balance falls below a required minimum. Reviewing the fee schedule can help you avoid unnecessary expenses.

    Interest rates are another factor to watch. A bank may advertise an attractive APY today, but savings rates can increase or decrease as market conditions change. It’s also worth checking whether the account has withdrawal limits, balance requirements, or conditions for earning the highest interest rate.

    💡 Expert Tip: Don’t choose the best savings accounts for families based only on the highest APY. Look for a combination of competitive interest rates, low fees, FDIC insurance, strong mobile banking, automatic savings tools, and reliable customer support. These features can provide greater value over the long term than a slightly higher interest rate alone.

    Comparing several banks before making a decision can help your family find an account that supports both your everyday needs and your future financial goals.


    Common Mistakes Families Make When Choosing a Savings Account

    Opening a savings account is an important step toward financial security, but choosing the wrong account can reduce the benefits over time. The best savings accounts for families should support your household’s goals, not create unnecessary costs or limitations. Avoiding a few common mistakes can help your savings grow more efficiently.

    Common Mistakes to Avoid

    • Focusing only on the highest APY: A high interest rate is attractive, but monthly fees, minimum balance requirements, and account features are just as important.
    • Ignoring fees: Even small maintenance fees can slowly reduce your family’s savings if you’re not paying attention.
    • Not comparing different banks: Checking several online and traditional banks often leads to better rates and more useful features.
    • Skipping automatic savings: Setting up recurring transfers makes it easier to save consistently without relying on memory.
    • Using savings for everyday spending: Keeping emergency savings separate from daily expenses helps protect your long-term financial goals.

    Real-Life Example

    The Johnson family wanted to build a stronger emergency fund after unexpected home repairs affected their budget. Instead of choosing the first bank they found, they compared several options and selected one of the best savings accounts for families with no monthly fees, a competitive APY, and automatic monthly transfers. By saving a fixed amount every payday, they steadily grew their emergency fund and felt more prepared for future expenses without making major changes to their lifestyle.


    Who Should Choose a Family Savings Account?

    The best savings accounts for families are a smart choice for households that want to build financial stability while keeping their money safe and accessible. Whether you’re saving for short-term expenses or planning years ahead, the right account can help you stay organized and reach your financial goals with confidence.

    • Parents with young children: Ideal for building emergency savings, education funds, or future family expenses.
    • Couples managing shared finances: A great way to save together for a home, vacations, or other major life goals.
    • Families creating an emergency fund: Keeping dedicated savings separate from everyday spending provides extra financial security.
    • New homeowners: Perfect for setting aside money for home maintenance, repairs, and unexpected costs.
    • Retirees supporting family members: Helpful for managing savings while remaining prepared for future financial needs.

    The best savings accounts for families offer competitive interest rates, low fees, FDIC protection, and convenient online banking. If your goal is to grow savings steadily while maintaining easy access to your money, opening a family savings account can be a practical step toward stronger long-term financial health.


    Frequently Asked Questions

    1. What is a family savings account?

    A family savings account is a bank account designed to help households save money for shared financial goals. Families often use these accounts to build emergency funds, save for vacations, children’s education, home improvements, or other future expenses while earning interest on their balance.

    2. What should I look for in the best savings accounts for families?

    When comparing the best savings accounts for families, look beyond the advertised APY. Consider monthly fees, minimum balance requirements, FDIC insurance, mobile banking features, customer service, and automatic savings tools. Choosing an account that fits your family’s lifestyle is just as important as earning a competitive interest rate.

    3. Are family savings accounts safe?

    Yes. If the account is held at an FDIC-insured bank, eligible deposits are protected up to the applicable federal insurance limits. This helps provide peace of mind while your family works toward its financial goals.

    4. Can I access my money whenever I need it?

    In most cases, yes. Savings accounts are designed to give you access to your funds when needed, although some banks may have policies regarding certain types of withdrawals or transfers. Always review the account terms before opening one.

    5. Do online banks offer better savings accounts?

    Many online banks offer higher APYs and lower fees because they have lower operating costs than traditional banks. However, the best choice depends on your family’s preferences for branch access, customer support, and digital banking features.

    6. Can I open more than one savings account?

    Absolutely. Many families use multiple savings accounts to organize different goals, such as emergency savings, vacations, holiday spending, or future education costs. Separating your savings can make budgeting easier.

    7. How much should a family keep in savings?

    The ideal amount depends on your income, monthly expenses, and financial goals. Many financial professionals recommend building an emergency fund that can cover several months of essential living expenses while continuing to save for future needs.

    8. Are family savings accounts better than keeping money in a checking account?

    For long-term savings, yes. The best savings accounts for families usually earn more interest than standard checking accounts while encouraging better saving habits and helping your money grow over time.


    Final Verdict

    The best savings accounts for families can play an important role in building long-term financial security. Whether you’re creating an emergency fund, saving for your children’s future, planning a family vacation, or preparing for unexpected expenses, the right savings account gives your money a safe place to grow while remaining accessible when you need it.

    Before opening an account, compare more than just the advertised APY. Review monthly fees, minimum balance requirements, FDIC insurance, mobile banking features, customer service, and automatic savings tools. A slightly lower interest rate may still offer greater overall value if the account provides better flexibility and fewer fees.

    The best savings accounts for families are those that match your household’s financial goals and encourage consistent saving over time. By choosing wisely and making regular deposits, your family can build stronger financial habits, stay prepared for life’s unexpected costs, and move confidently toward future milestones with greater peace of mind.


    📩 Stay One Step Ahead with Smarter Family Finance Tips

    If this guide on the Best Savings Accounts for Families helped you, join the FinanceInvestment newsletter for practical advice on saving, banking, retirement planning, investing, and building long-term wealth. Every guide is written to help you make confident financial decisions with simple, reliable information.


    📧 Subscribe Free

    ✔ Weekly Money Tips   •   ✔ Free Guides   •   ✔ Unsubscribe Anytime

    Continue Reading

  • Best Savings Accounts for Kids in 2026: Top Options to Help Your Child Build Smart Money Habits

    Best Savings Accounts for Kids in 2026: Top Options to Help Your Child Build Smart Money Habits

    👨‍💼

    FinanceInvestment Editorial Team

    Written by : Subhash Rukade, • Reviewed by • Fact Checked

    ✔ Editorial Integrity

    📅 Updated July 23,2026

    ⏱ 12 Min Read

    ✓ Fact Checked

    🇺🇸 Updated for july 23,2026

    Our editorial team researches trusted banking institutions, financial regulations, and savings products to create reliable, easy-to-understand content for American families. Every guide is reviewed for accuracy, transparency, and practical value so parents can confidently choose the best financial products for their children.

    Best Savings Accounts for Kids: Top Kid-Friendly Bank Accounts for 2026

    Best Savings Accounts for KidsOpening one of the best savings accounts for kids is a simple way to help children build healthy money habits from an early age. Whether they’re saving birthday gifts, allowance, or money earned from small jobs, a dedicated savings account teaches the value of setting goals, saving consistently, and watching money grow over time.

    Many parents choose the first account their local bank offers without comparing important features such as interest rates, fees, minimum balance requirements, and digital banking tools. The right account can make saving more rewarding while giving parents the ability to monitor and guide their child’s financial progress.

    In this guide, you’ll learn how kids’ savings accounts work, which features matter most, and how to compare the best options available in the United States. We’ll also cover common mistakes to avoid, practical saving tips for families, and ways to encourage lifelong financial responsibility.

    If you’re exploring more ways to grow your family’s savings, read our High-Yield Savings Accounts USA Guide. You can also compare digital and traditional banking in our Online Banks vs Traditional Banks guide before choosing the right account.

    Quick Answer: Best Savings Accounts for Kids

    Quick Answer: The best savings accounts for kids help children develop smart money habits while giving parents a safe place to save on their behalf. The best accounts typically offer no monthly maintenance fees, low or no minimum balance requirements, competitive interest rates, and easy online access for parents to monitor progress.

    Key Takeaways

    • Start saving early to help children build lifelong financial habits.
    • Look for accounts with no monthly maintenance fees.
    • Compare APYs, minimum balance requirements, and account features.
    • Choose an FDIC-insured bank to protect eligible deposits.
    • Parental controls and online access make managing savings easier.
    • Regular deposits, even small ones, can help children understand the value of consistent saving.

    Bottom Line: The best savings accounts for kids make learning about money simple, practical, and rewarding. Choosing the right account today can help children build confidence with money while creating healthy financial habits that can benefit them for years to come.

    Table of Contents

    1. Kids Savings Accounts at a Glance
    2. Complete Beginner Guide
    3. How Kids Savings Accounts Work
    4. Benefits and Drawbacks
    5. Comparison Table
    6. Costs, Risks, and Expert Tips
    7. Common Mistakes to Avoid
    8. Who Should Open a Kids Savings Account?
    9. Frequently Asked Questions
    10. Final Verdict and Related Resources

    Best Savings Accounts for Kids at a Glance

    The best savings accounts for kids are designed to help children learn smart money habits while giving parents a safe and convenient way to manage their savings. Whether the money comes from birthday gifts, allowances, chores, or special occasions, a dedicated savings account teaches children that saving regularly is just as important as spending wisely. Starting at a young age also helps build confidence with money before they become teenagers or young adults.

    Quick Facts

    • Best For: Children, parents, grandparents, and guardians who want to build lifelong saving habits.
    • Monthly Fee: Many kid-friendly savings accounts charge no monthly maintenance fee.
    • Minimum Balance: Often low or not required.
    • Interest: Many accounts earn competitive APYs that help savings grow over time.
    • Security: Eligible deposits are protected by FDIC insurance at participating banks.

    Kids Savings Account Snapshot

    FeatureWhat to Look For
    Monthly FeeNo monthly maintenance fee
    Minimum BalanceLow or no balance requirement
    Interest (APY)Competitive interest rate
    Parental AccessEasy account monitoring and controls
    Mobile BankingSimple online account management
    SecurityFDIC-insured institution

    Summary: The best savings accounts for kids combine low fees, competitive interest rates, parental oversight, and easy digital banking. Comparing these features before opening an account helps families choose a savings option that supports both financial education and long-term savings goals.

    Complete Beginner Guide to the Best Savings Accounts for Kids

    Choosing one of the best savings accounts for kids is a great way to introduce children to the basics of money management. A savings account gives them a safe place to keep their money while helping them understand the importance of setting goals, saving regularly, and watching their balance grow over time. These lessons can build confidence and create healthy financial habits that last into adulthood.

    Parents or legal guardians usually open the account on behalf of the child and manage it until the child reaches the required age. During that time, families can use the account to save birthday money, holiday gifts, allowance, or earnings from small jobs. Making regular deposits, even in small amounts, teaches children that saving is a habit rather than a one-time event.

    When comparing accounts, don’t focus only on the interest rate. Look for features such as no monthly maintenance fees, low or no minimum balance requirements, parental account access, mobile banking, and FDIC insurance. These benefits make it easier to manage the account while helping children learn responsible financial behavior.

    If your goal is to earn more on your family’s savings, read our guide on How High-Yield Savings Accounts Work. You can also compare digital and branch banking in our Online Banks vs Traditional Banks guide before choosing an account.

    The best savings accounts for kids make saving fun, simple, and educational while giving families a practical way to prepare children for future financial success.

    How Kids Savings Accounts Work

    The best savings accounts for kids are designed to help children learn how saving works while allowing parents or guardians to supervise the account. In most cases, an adult opens the account, manages it, and gradually teaches the child how to save, track their balance, and understand basic banking concepts.

    Money can be added through birthday gifts, holiday cash, allowance, rewards for chores, or regular deposits from parents. Many banks also offer online and mobile banking, making it easy for families to check balances, review transactions, and monitor savings progress together. Seeing the balance grow over time can motivate children to continue saving instead of spending every dollar they receive.

    Most accounts earn interest based on the Annual Percentage Yield (APY). Although the amount earned may be small in the beginning, children learn an important lesson about how money can grow over time. This also creates a natural opportunity for parents to explain compound interest and the value of long-term saving.

    Before opening an account, compare important features such as APY, monthly fees, minimum balance requirements, parental controls, mobile banking, and FDIC insurance. The best savings accounts for kids combine safety, convenience, and financial education, helping children develop smart money habits that can benefit them well into adulthood.

    Benefits and Drawbacks of Kids Savings Accounts

    The best savings accounts for kids do more than hold money. They give children an opportunity to learn important financial skills while allowing parents to guide them every step of the way. Although these accounts offer many advantages, it’s also helpful to understand a few limitations before choosing one.

    ✅ Advantages

    • Teaches children the importance of saving from an early age.
    • Many accounts have no monthly maintenance fee.
    • Low or no minimum balance requirements make them easy to maintain.
    • Parents can monitor account activity and guide spending decisions.
    • Competitive APYs help savings grow over time.
    • Eligible deposits are protected by FDIC insurance at participating banks.

    ❌ Drawbacks

    • Interest earnings may be modest when the account balance is small.
    • Some accounts require a parent or guardian to remain a joint owner.
    • Features and educational tools vary from one bank to another.
    • Special youth account benefits may end when the child reaches a certain age.
    • Optional banking services may still include separate fees.

    💡 Expert Tip

    When comparing the best savings accounts for kids, look beyond the interest rate. Choose an account that combines low fees, parental controls, mobile banking, educational tools, and a trusted FDIC-insured bank. The right account should help your child learn healthy financial habits while making saving simple and enjoyable.

    Comparison: How to Choose the Best Savings Accounts for Kids

    Not every children’s savings account offers the same features. Some banks focus on higher interest rates, while others provide better educational tools, easier parental controls, or lower fees. Before opening an account, compare the features that will benefit both you and your child. The best savings accounts for kids should make saving simple while encouraging lifelong financial responsibility.

    FeatureExcellent ChoiceBasic Choice
    Monthly FeeNo monthly maintenance feeMonthly fee may apply
    Minimum BalanceNo or low balance requirementHigher balance requirement
    Interest (APY)Competitive APYAverage APY
    Parental ControlsFull account monitoring and managementLimited account access
    Mobile BankingEasy online access with alertsBasic online banking
    Educational ToolsSavings goals and financial learning featuresFew or no educational tools
    SecurityFDIC-insured institutionStandard banking protection

    Key Insight

    The best savings accounts for kids offer much more than a place to store money. A great account combines competitive interest rates, low fees, strong parental controls, educational features, and secure online banking. Comparing these benefits before opening an account can help families choose a savings option that encourages responsible money habits while preparing children for long-term financial success.

    Costs, Potential Risks, and Expert Tips

    Best Savings Accounts for KidsThe best savings accounts for kids are usually affordable and easy to manage, but parents should still review the account terms before opening one. Many children’s savings accounts have no monthly maintenance fee, yet some banks may charge for optional services such as paper statements, wire transfers, or other special banking requests.

    Interest rates can also change over time. While some accounts offer competitive APYs, the rate isn’t guaranteed to remain the same. It’s also worth checking whether the account automatically converts to a standard savings account when the child reaches a certain age, as fees or account features may change at that point.

    Before choosing an account, compare APYs, monthly fees, minimum balance requirements, parental controls, online banking features, and FDIC insurance. Taking a little extra time to compare different banks can help you find an account that supports both your child’s financial education and your family’s long-term savings goals.

    💡 Expert Tip: The best savings accounts for kids don’t just help children save money—they help them build lifelong financial habits. Look for an account that combines low fees, educational tools, parental oversight, and competitive interest rates to create the best learning experience.

    Common Mistakes Parents Make When Opening a Kids Savings Account

    Opening a savings account for your child is an excellent way to introduce money management, but choosing the wrong account can reduce its long-term value. By avoiding a few common mistakes, families can get the most from the best savings accounts for kids while helping children build healthy financial habits from an early age.

    Common Mistakes

    • Choosing the nearest bank without comparing options: Convenience is helpful, but comparing APYs, fees, and account features can lead to a much better choice.
    • Ignoring monthly maintenance fees: Even small fees can reduce a child’s savings over time. Look for accounts with no monthly maintenance charges.
    • Doing all the saving yourself: Encourage your child to make regular deposits from allowance, gifts, or small earnings so they learn the value of saving consistently.
    • Not setting savings goals: Saving for a bicycle, gaming console, college fund, or family trip helps children stay motivated and understand the importance of planning ahead.
    • Overlooking educational tools: Many banks provide savings trackers, goal-setting features, and mobile apps that make learning about money more engaging.

    Real-Life Example

    Emma’s parents opened one of the best savings accounts for kids when she turned eight. Every month, Emma deposited part of her allowance and birthday money into the account while tracking her progress through the bank’s mobile app. After a year of consistent saving, she reached her goal of buying a new bicycle. More importantly, she learned that patience, regular saving, and smart financial decisions can help achieve long-term goals.

    Who Should Open a Kids Savings Account?

    The best savings accounts for kids are an excellent choice for families who want to teach children the value of saving from an early age. Learning how to manage money while growing up can build confidence and create healthy financial habits that last well into adulthood.

    • Parents: Ideal for parents who want to help their children save birthday money, allowance, or holiday gifts in a secure account.
    • Grandparents and relatives: A thoughtful way to contribute toward a child’s future while encouraging long-term saving instead of short-term spending.
    • Children with financial goals: Perfect for kids saving for a bicycle, computer, school activities, or future education expenses.
    • Families teaching money management: A savings account provides real-life experience with budgeting, goal setting, and responsible financial decisions.
    • Young savers preparing for the future: Starting early helps children understand the benefits of regular saving and compound interest over time.

    The best savings accounts for kids combine low fees, competitive interest rates, parental oversight, and easy banking tools. Choosing the right account today can help children develop smart money habits while creating a strong financial foundation for the future.

    Frequently Asked Questions

    1. What is a kids savings account?

    A kids savings account is a bank account created to help children save money while learning basic financial skills. Most accounts are opened and supervised by a parent or legal guardian until the child reaches the required age.

    2. What is the best age to open a savings account for a child?

    There isn’t a perfect age. Many parents open an account when their child begins receiving allowance, birthday money, or cash gifts. Starting early gives children more time to develop healthy saving habits.

    3. Do kids savings accounts earn interest?

    Yes. Many of the best savings accounts for kids earn interest based on the account’s Annual Percentage Yield (APY). Although balances may start small, regular deposits and interest can help savings grow over time.

    4. Are kids savings accounts safe?

    Yes. When the account is opened at an FDIC-insured bank, eligible deposits are protected up to the applicable federal insurance limits. This provides families with added peace of mind.

    5. Can parents monitor the account?

    Yes. Most children’s savings accounts allow parents or legal guardians to manage the account, monitor transactions, review balances, and guide their child’s saving decisions through online or mobile banking.

    6. What should parents compare before opening an account?

    Compare monthly maintenance fees, APYs, minimum balance requirements, parental controls, mobile banking features, customer service, and FDIC insurance. The best savings accounts for kids combine these features to create both a safe banking experience and a valuable learning opportunity.

    7. Can family members contribute to a child’s savings account?

    In many cases, yes. Parents, grandparents, and other relatives can often contribute money to help a child save for future goals such as education, special purchases, or long-term financial security, depending on the bank’s policies.

    8. Why is opening a savings account for a child important?

    A savings account helps children understand budgeting, goal setting, delayed gratification, and responsible money management. Learning these skills at an early age can build confidence and create financial habits that benefit them throughout adulthood.

    Final Verdict

    The best savings accounts for kids do much more than provide a safe place to store money. They give children an opportunity to learn valuable financial skills while helping parents encourage responsible saving habits from an early age. Small deposits made consistently can teach lessons about patience, goal setting, and the importance of planning for the future.

    Before opening an account, compare more than just the advertised APY. Look at monthly maintenance fees, minimum balance requirements, parental controls, online banking features, educational tools, and FDIC insurance. Choosing an account that is easy to manage and designed for families can make saving both simple and enjoyable.

    The best savings accounts for kids combine safety, flexibility, and practical learning opportunities. By choosing the right account and encouraging regular saving, parents can help their children build strong financial habits that support future goals, from buying their first bicycle to preparing for college and beyond.

    📩 Build Smarter Money Habits for the Whole Family

    Enjoyed this guide on the Best Savings Accounts for Kids? Subscribe to the FinanceInvestment newsletter for expert tips on saving, banking, investing, and family finances. Get practical advice, new guides, and money-saving strategies delivered straight to your inbox.


    📧 Subscribe Free

    ✔ Free Newsletter   •   ✔ No Spam   •   ✔ Unsubscribe Anytime

    Continue Reading